Author: shaleenmahtani

  • FHA Loans Explained: Requirements, Benefits, and Costs

    FHA Loans Explained: Requirements, Benefits, and Costs

    Buying a home can feel challenging when you have limited savings or a credit history that needs improvement. FHA loans offer an option for eligible homebuyers who want to purchase a home with a relatively small down payment. Backed by the Federal Housing Administration (FHA), these mortgages are designed to make homeownership more accessible for qualified borrowers.

    Understanding FHA loan requirements, benefits, and costs can help you decide whether this mortgage option fits your financial situation.

    What Are FHA Loans?

    FHA loans are mortgages issued by approved private lenders and insured by the Federal Housing Administration, a division of the U.S. Department of Housing and Urban Development (HUD). The government does not lend money directly to borrowers. Instead, FHA insurance reduces the lender’s risk, helping eligible buyers access mortgage financing.

    These loans are particularly popular among first-time homebuyers and people who may not qualify for conventional financing on favorable terms. However, you do not have to be a first-time buyer to qualify.

    FHA Loan Requirements

    Before applying, it is important to understand the basic FHA loan eligibility guidelines.

    Credit Score and Down Payment

    FHA guidelines generally allow a minimum down payment of 3.5% for borrowers with a credit score of 580 or higher. Borrowers with scores between 500 and 579 may qualify with a down payment of at least 10%, subject to FHA requirements and lender approval.

    For example, a 3.5% down payment on a $300,000 home equals $10,500. You will still need to budget for closing costs and other expenses.

    Keep in mind that individual lenders may establish stricter credit score requirements.

    Income and Debt-to-Income Ratio

    Lenders review your income, existing debts, employment history, and ability to afford monthly mortgage payments. They generally verify your financial information through documents such as pay stubs, tax returns, bank statements, and employment records.

    Your debt-to-income ratio (DTI) helps lenders assess how much of your gross monthly income goes toward debt payments. FHA financing offers flexibility, but approval depends on your overall financial profile and the lender’s underwriting assessment.

    Property Requirements

    FHA loans generally require the home to serve as your primary residence. Eligible properties can include single-family homes, certain condominiums, and properties with two to four units, provided they meet applicable occupancy and program requirements.

    The property must also satisfy FHA appraisal standards. An appraisal helps establish the home’s value and evaluate whether it meets applicable property requirements.

    Benefits of FHA Loans

    FHA financing offers several advantages for eligible homebuyers.

    • Low down payment: Qualified borrowers may purchase a home with as little as 3.5% down.
    • Flexible credit guidelines: FHA requirements may accommodate borrowers with lower credit scores than many conventional mortgage programs.
    • Multiple property options: Eligible buyers can finance different types of owner-occupied residential properties.
    • Accessible financing: FHA loans can help buyers who have limited savings or are building their credit history explore homeownership.

    Although these benefits can make purchasing a home more achievable, borrowers should compare FHA financing with conventional mortgages before making a decision.

    What Costs Should You Expect With FHA Loans?

    A low down payment does not mean an FHA mortgage is free from additional expenses. Understanding the total cost is essential before committing to a loan.

    Mortgage insurance premiums: FHA loans generally require an upfront mortgage insurance premium (UFMIP) and an annual premium, typically paid in monthly installments. The upfront premium is generally 1.75% of the base loan amount and may be financed into the mortgage. Annual mortgage insurance costs vary depending on factors such as the loan amount, term, and loan-to-value ratio.

    Closing costs: These may include lender fees, appraisal charges, title services, prepaid taxes, and homeowners insurance. The exact amount depends on the transaction and location.

    Monthly housing expenses: Your payment may include principal, interest, property taxes, homeowners insurance, and mortgage insurance. Homeowners association fees may also apply.

    Because mortgage insurance adds to the overall cost, compare loan estimates rather than focusing only on the down payment.

    Are FHA Loans Right for You?

    FHA loans may be a good fit if you want to buy a home with a smaller down payment or need more flexible credit requirements. However, borrowers with stronger credit and larger down payments may find that conventional mortgages offer lower overall costs.

    Before choosing, compare interest rates, mortgage insurance, closing costs, and long-term payments from multiple lenders.

    Ready to Explore Your FHA Loan Options?

    Finding the right mortgage starts with understanding your budget, credit profile, and available loan programs. If you are considering FHA loans, contact Shaleen Mahtani at 201-745-3426 or email shaleenmahtani@gmail.com to discuss your mortgage options, review your eligibility, and understand the costs involved. Get personalized guidance to help you take the next step toward homeownership with confidence.
  • Alternative Mortgage Options When You Are Self-Employed

    Alternative Mortgage Options When You Are Self-Employed

    Buying a home when you are self-employed can be challenging, especially if your tax returns show less income than you actually earn. Unlike salaried employees, freelancers, independent contractors, and business owners often have fluctuating income and business deductions that can complicate mortgage approval.

    Fortunately, Alternative mortgage options may help self-employed borrowers qualify for home financing when traditional income documentation does not reflect their full financial situation. Understanding these options can help you find a mortgage that suits your income, financial goals, and homeownership plans.

    Why Is Getting a Mortgage Difficult When You Are Self-Employed?

    Mortgage lenders need to verify that borrowers can afford their monthly payments. They typically review income records, tax returns, credit history, and existing debts.

    Business owners often use tax deductions to reduce their taxable income. Although these deductions can benefit a business financially, they may also reduce the income lenders use to determine mortgage eligibility.

    According to Fannie Mae’s guidelines for self-employed borrowers, lenders evaluate income stability and the financial health of the business.

    When traditional income calculations create challenges, exploring alternative financing may be worthwhile.

    5 Alternative Mortgage Options for Self-Employed Borrowers

    1. Bank Statement Loans

    Bank statement loans allow eligible self-employed borrowers to demonstrate income through personal or business bank statements rather than relying primarily on tax returns.

    Lenders may review 12 to 24 months of statements to assess deposits and cash flow. Some also apply an expense factor to business deposits when calculating qualifying income.

    These loans may suit freelancers, consultants, and business owners with consistent deposits but relatively low taxable income. However, interest rates, fees, and down payment requirements vary by lender.

    2. Profit and Loss Statement Loans

    A profit and loss (P&L) statement loan may help business owners demonstrate their earnings through financial statements showing revenue, expenses, and net profit.

    Depending on the program, lenders may require a statement prepared or reviewed by an accountant, along with bank statements or other business records.

    This option may benefit borrowers who maintain organized financial records but struggle to qualify using conventional tax-return calculations. Ask the lender which documents are required and how qualifying income is determined.

    3. Asset-Based Mortgage Options

    Some mortgage programs consider eligible financial assets when evaluating a borrower’s ability to repay a loan. These assets may include savings, investment accounts, and certain retirement funds, depending on the program.

    This approach may suit entrepreneurs with substantial assets but irregular monthly income. Lenders establish specific requirements for eligible assets, reserves, and documentation.

    Asset-based qualification does not guarantee approval, so compare program requirements before applying.

    4. 1099 Income Mortgage Programs

    Independent contractors and freelancers who receive Form 1099 income may qualify for specialized mortgage programs that consider their contractor earnings.

    Depending on the lender, documentation may include 1099 forms, bank statements, tax returns, or other income records.

    These programs may benefit consultants, gig workers, and professionals who earn income from multiple clients. However, lenders still evaluate credit history, existing debts, income consistency, and overall financial stability.

    5. Conventional Mortgages

    Alternative financing is not always necessary. Self-employed borrowers may qualify for conventional mortgages through programs associated with Fannie Mae or Freddie Mac.

    Lenders generally review tax returns and other financial records to calculate qualifying income. Certain borrowers may qualify with one year of tax returns if they meet applicable eligibility requirements.

    If your business has a stable income history, ask a mortgage professional whether a conventional loan could offer more favorable terms than a specialized mortgage program.

    How to Improve Your Chances of Mortgage Approval

    Before applying, take these steps to strengthen your mortgage application:

    • Organize financial records: Keep tax returns, bank statements, and business financial documents accessible.
    • Separate business and personal finances: Clear records can make income verification easier.
    • Reduce existing debt: Lower monthly debt payments may improve your debt-to-income ratio.
    • Save for a down payment: Additional savings can help cover upfront costs and potential reserves.
    • Compare lenders: Review interest rates, fees, documentation requirements, and repayment terms before choosing a loan.

    Explore Your Alternative Mortgage Options

    Being self-employed does not mean homeownership is out of reach. The right mortgage program may help you qualify based on your financial circumstances and income documentation.

    Contact Shaleen Mahtani to discuss your situation and explore available mortgage programs. With lending services available in all 50 states, you can get guidance on finding a suitable financing solution. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your mortgage options.

  • How Construction Permanent Financing Works for Homebuyers

    How Construction Permanent Financing Works for Homebuyers

    Building a home gives you the freedom to choose a layout, features, and finishes that fit your needs. However, financing a new construction project can be more complicated than purchasing an existing property. Construction permanent financing offers a practical solution by combining the funds needed to build a home with a long-term mortgage.

    This financing option can simplify the borrowing process and help homebuyers plan for the transition from construction to homeownership. Understanding how it works, its benefits, and its requirements can help you decide whether it suits your homebuying goals.

    What Is Construction Permanent Financing?

    Construction permanent financing, also called a construction-to-permanent loan, is a mortgage option that covers the cost of building a home and provides long-term financing after construction is complete.

    Instead of arranging a short-term construction loan and then applying for a separate mortgage, borrowers may be able to combine both stages into one financing arrangement.

    During construction, the lender releases funds to pay for approved building expenses. Once the home is completed and the lender’s requirements are met, the construction loan converts into a permanent mortgage.

    According to Fannie Mae, borrowers can use either a single-closing or a two-closing structure, depending on their financing arrangements.

    How Does Construction Permanent Financing Work?

    The process generally involves several steps, although specific requirements vary by lender and loan program.

    1. Apply for the Loan

    The first step is to submit a mortgage application. Lenders typically review your credit history, income, employment, existing debts, and available funds to determine whether you qualify.

    You may also need to provide construction plans, a project budget, a building contract, and details about the property or land.

    2. Get Approval for Your Construction Project

    The lender evaluates the proposed home, estimated construction costs, and other project details. An appraisal may be required to estimate the property’s expected value after completion.

    The lender also reviews the builder or contractor and confirms that the project meets its lending requirements.

    3. Receive Construction Funds

    After closing, the lender releases money in stages as construction progresses. These payments are often called draws and may depend on completed work, inspections, and the loan agreement.

    During this phase, borrowers may make interest-only payments on the amount disbursed. However, payment arrangements vary by lender and loan terms.

    4. Convert to a Permanent Mortgage

    Once construction is complete, the lender verifies that the home meets the required conditions. Depending on the loan structure, the construction financing then converts into a long-term mortgage or is replaced by a new mortgage at a second closing.

    With a single-closing loan, the permanent mortgage terms are generally established at the initial closing. A two-closing arrangement requires borrowers to complete a separate closing for permanent financing.

    Single-Closing vs. Two-Closing Financing

    Homebuyers should understand the difference between these two options before choosing a loan.

    Single-closing financing: You close once for both construction and permanent financing. This can reduce duplicate closing expenses and simplify paperwork. Depending on the lender and loan terms, you may also secure your permanent mortgage interest rate upfront.

    Two-closing financing: You close once to obtain construction funding and again to secure the permanent mortgage. This may offer more flexibility when selecting a lender for the long-term mortgage, but it can involve additional closing costs and underwriting.

    Compare both options carefully to understand the total cost and requirements.

    Benefits of Construction Permanent Financing

    Construction permanent financing offers several potential advantages for homebuyers:

    • Simplified financing: Combining construction and permanent financing can reduce the need to arrange separate loans.
    • Potential cost savings: A single closing may help lower overall closing expenses compared with two separate closings.
    • Long-term planning: Knowing the permanent mortgage terms can help you estimate future housing payments.
    • Flexible home design: You can finance the construction of a home tailored to your preferences and needs.

    However, these benefits depend on the lender, loan structure, and your financial circumstances.

    What Are the Requirements?

    Qualification requirements vary, but lenders commonly evaluate creditworthiness, income, debt-to-income ratio, down payment, and available cash reserves.

    You may also need approved building plans, a detailed construction budget, a qualified builder, and documentation showing ownership of the land or how it will be acquired.

    Remember that construction delays, unexpected expenses, and changes in your financial situation can affect the project. Maintaining a realistic budget and understanding your loan agreement are important steps toward managing these risks.

    Plan Your Home Construction Financing With Confidence

    Construction permanent financing can make building a home more manageable by connecting construction funding with long-term mortgage financing. Before choosing a loan, compare closing costs, interest rates, down payment requirements, and conversion terms to find an option that fits your budget.

    If you are planning to build a home, contact Shaleen Mahtani at 201-745-3426 or shaleenmahtani@gmail.com to discuss your mortgage options. Lending services are available in all 50 states, subject to applicable loan requirements and approval.

  • Surging insurance costs are deepening affordability strain

    Surging insurance costs are deepening affordability strain

    While mortgage rates are grabbing big headlines, homeowners insurance has quietly become one of the most significant costs squeezing today’s buyers.

    Over the past seven years, average premiums have climbed sharply across the country. According to the National Association of Insurance Commissioners (NAIC), the Southeast carries the highest average annual premium at $1,818, while the Northeast sits lowest at $1,396. Based on Bureau of Labor Statistics data tracked by the National Association of REALTORS® (NAR), premiums have risen 7% since the start of 2025.

    Insurance experts point to climate-related risk and rising rebuilding costs as key drivers, with insurers passing much of this added risk on to consumers. Combined with a stubborn affordability crisis and inflation that has remained above the Federal Reserve’s 2% target for years, the costs are adding up. The NAR estimates that homebuying power today is roughly 10% lower than it would be had insurance costs simply kept pace with inflation.

    The strain hits lower-income households the hardest. Many are dropping coverage altogether to save money, leaving their homes—typically their largest assets—exposed in the event of a disaster.

    Insurers are also pulling back more aggressively, declining to renew policies when the risk no longer justifies the reward. Since 2018, nonrenewal rates have jumped nationwide, from 96% in the Southeast to as much as 216% in the West. As NAIC researchers Jeffrey Czajkowski and Paula Harms recently summarized, the market looks stable on the surface but is clearly under growing strain.

    For your clients, understanding these trends can help set realistic expectations around total homeownership costs. I am more than happy to talk through how insurance costs are affecting buyers or sellers in your market.

    Mortgage Rates Come Down From Long-Term Highs

    What a difference a week can make” is an expression that is used all-too-frequently in the mortgage industry. Last week delivered a seven-day stretch that certainly warranted its use.

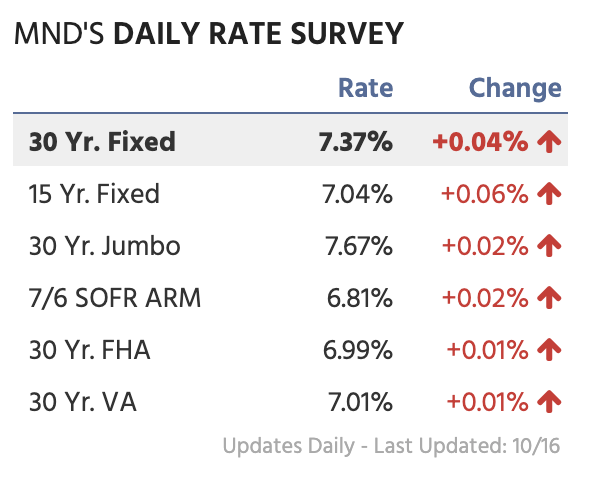
    The average top-tier 30-year fixed rate dropped to 7.33% last Thursday, more than 0.25% below the long-term highs hit just last week. The turnaround began in dramatic fashion on Wednesday. Hotter-than-expected inflation data pushed lenders’ first-rate sheets 0.1% higher, a big move for a single day. Approximately 30 minutes later, the bond market started a steady recovery as stocks sold off hard, posting their worst day in over two months. Many investors moved money out of stocks and into bonds, which helps push rates down. By the end of the day, the average lender was 0.01% lower than 24 hours earlier, an outcome that looked nearly impossible that morning.

    Thursday built on this positive momentum, driven largely by growing worries in the tech sector. Concerns that trouble at certain AI-related companies, such as CoreWeave, could spread to others weighed on investor sentiment. A cooling tech sector could slow economic growth, and a souring appetite for AI-related corporate debt would mean less new debt competing with Treasuries and mortgage bonds for investor dollars.

    Yields also climbed high enough to potentially attract buyers. Some investors see 10-year Treasury yields above 5.2% as an attractive entry point, much as they did when yields reached 5% in 2023.

    Behind this week’s rate swings were two closely watched inflation reports, and both pointed in the same uncomfortable direction.

    Inflation runs hot as both the consumer and wholesale level

    Wednesday’s Consumer Price Index (CPI) showed prices rose 0.6% in September. The annual inflation rate climbed to 3.7% from 3.4% in August, slightly above the 3.6% economists forecasted. Core CPI, which strips out volatile food and energy costs, rose 0.3% for the month, topping the 0.2% estimate. Its annual rate moved up to 2.6% from 2.4%, also above the 2.5% forecast.

    Once again, energy was the main culprit. The energy index jumped 5.2% and gasoline surged 9.1%, accounting for roughly half of the overall increase. Over the past year, gasoline is up 34.2% and fuel oil is up a staggering 74.2%.

    However, energy was not the entire story. Food prices were flat for the month, shelter costs rose 0.4%, used car and truck prices climbed 0.7%, and apparel, a category sensitive to tariffs, increased 0.3%. A strategist at Carson Group noted that core inflation ran at a 3.7% annualized pace in September and warned that the full impact of higher diesel prices and the AI boom has yet to show up in the data.

    Thursday’s Producer Price Index (PPI), which tracks what businesses pay to produce goods and services, told a similar story. Wholesale prices rose 0.6% in September, pushing the annual rate to 6.3%, the highest level since late 2022. Core PPI, which excludes food and energy, jumped 0.7% for the month and is up 5% from a year ago. All the report’s key numbers came in well above economists’ expectations.

    The PPI is often seen as a preview of what’s coming for consumer prices. According to the Bureau of Labor Statistics, half of the monthly increase came from gasoline. Diesel, jet fuel, fresh and dry vegetables, residential electricity, and crude oil all rose as well.

    Economists have singled out diesel as the most worrying increase, since it powers farming, trucking, and shipping, and higher costs there tend to ripple through nearly every category of consumer goods. Unlike earlier in the year, when price spikes were concentrated in fuel-exposed sectors, the increases are now spreading across the broader economy.

    The two reports mean the Federal Reserve is now facing a delicate balancing act. The central bank raised its benchmark rate by a quarter point in September, taking the range to 3.75%–4%. Several officials have said there’s no need to rush another increase, though most still expect one before year’s end. Markets are leaning toward a pause in October and a hike in December, but this week’s data raised the odds of a faster move.

    Existing home sales edge upward

    According to the National Association of REALTORS® (NAR) Existing Home Sales report, sales rose 1.5% in September to a seasonally adjusted annual rate of 3.99 million. Monthly sales climbed in the South and West and dipped in the Northeast, while every region posted an annual decline.

    NAR Chief Economist Lawrence Yun noted that August and September were the two slowest months for sales this year, with rising mortgage rates shrinking the pool of buyers who qualify.

    Inventory reached 1.6 million units, a 4.8-month supply, which Yun said is giving buyers more negotiating power. The median price hit $417,500, up 1.3% from last year and the 39th straight month of annual gains. Affordability slipped from a year ago, with only the West improving.

  • Shaleen Mahtani Champions Building Professional Credibility Through Knowledge and Experience

    Shaleen Mahtani Champions Building Professional Credibility Through Knowledge and Experience

    A professional in the modern age of information relies as much on their professional credibility as they do on their actual skillset, which means perception is nearly as important as reality. This phenomenon comes with a hard consequence: people’s pre-existing biases and expectations can get between them and the perfect person to solve their problems. As an experienced mortgage professional, Shaleen Mahtani has experienced this phenomenon first-hand. Her advice to the business world is simple: don’t rely on titles or first impressions; expertise eventually speaks for itself. 

    Since starting her journey as a mortgage banking assistant in 1999, Shaleen Mahtani has consistently stood apart from her peers by virtue of her expertise, dedication, and unwavering commitment to excellence. That excellence was recognized when she was tapped by Wells Fargo to develop their Private Mortgage Banking Division in New Jersey—a division that expanded to 36 direct reports and achieved a top 10% national ranking in growth and profitability under her leadership. It’s an achievement predicated on her work ethic, immigrant values, and strategic insights in a competitive field.

    Yet, despite these successes, Mahtani has faced challenges in the workplace born of assumptions about her knowledge and capability, all because she’s a woman, a minority, and an immigrant. These assumptions never survive longer than the first impressions, as clients and referral partners change their perception quickly upon working with her. While the initial assumptions are themselves a problem, the outcome is itself proof that first impressions and initial biases are worthless in the face of real credibility built through knowledge and experience. 

    “It is interesting that there is an inherent bias on me being a minority and a woman, that I would be less experienced or knowledgeable than my male counterparts,” Mahtani says. “After an individual, clients or referral partners start speaking to me, they quickly recognize my knowledge, experience and expertise.” 

    Strengthened By Personal Perspective

    The irony behind some of the misconceptions and biases Shaleen Mahtani has had to overcome is that the very labels and categories others have dismissed her for are some of the strongest roots of her professional strength. Mahtani is deeply influenced by her values as an immigrant, having come to the United States at 14 years of age and immediately having to work through both High School and University. Her mother’s guidance, support, and mentorship have been a guiding light for her as well; her parents modeled the sacrifices and resilience needed to build a better life, and those lessons have never faded. 

    “I have never believed in getting a free ride,” Mahtani says. “I believe in hard work, focus, dedication, and taking things slow and steady. I deeply believe in always doing the right thing, never taking what I haven’t earned, and making my own way in life. I remember growing up how little my family had, but I knew the only way to succeed was to work hard and be focused. I don’t quit; I am the first one in at work and the last to leave. Nothing has come for free to me, everything has come through pure hard work and dedication.”

    These are the values and experiences Mahtani carried as she pushed through the various challenges of life, including family drama and food insecurity. Her work ethic and financial acumen helped her excel in school, eventually graduating with a BBA in Finance from the University of Georgia. After being advised that being a woman and a minority would all but bar her from Wall Street, she leapt into mortgage banking and built the success she’s known for today.

    Building Credibility Through Excellence

    Mortgage banking is a competitive, even cutthroat industry. There are no normal 9-to-5 hours in an industry where clients and referral partners might need their mortgage banker at any time, which means work can easily carry into the late evening, weekends, and vacations. Peers are often apathetic or hostile rather than collaborative. Yet, since starting in 1999, Shaleen Mahtani has consistently performed at the highest levels of professional excellence, to the point of being ranked in the top 1% in the United States. In the face of that success, everything else falls to the wayside. 

    “True success comes not from the title you hold but from the integrity you uphold,” Mahtani says. “When the road gets tough, remember why you started and who inspired you. Success is the sum of small efforts repeated day in and day out.”

    Currently, the industry is experiencing one of the most challenging years since Shaleen Mahtani started working as a mortgage banker. In prior years, where mortgage value was coming in at a robust and steady pace, the focus was on catering to all clients and converting as much business as possible. Now, with volume significantly lower than usual, working to generate future volume is more important. Even in this challenging time, Mahtani is working toward success. 

    “The key is not about the amount of volume generated and closed, it is about having the mental stamina and fortitude to continue to do the activities to drive business,” she explains. “Prior to making an important decision, I analyze the possible outcomes and don’t waste time in doing so. I am my biggest critic and best advocate. Therefore, in order to accomplish the outcome I desire, I must be focused.”

    Staying Grounded Amidst Soaring Success

    Shaleen Mahtani has well-established herself as a successful mortgage banker in her industry, with an impressive professional record that speaks for itself. However, she takes care to make sure that success and confidence doesn’t cross the line into arrogance. Staying grounded and having humility amidst her achievements is a crucial part of staying at the top of her game. 

    “Our business has had its incredible highs and lows, when things are going well, volume is rapid, and the income stream is high, it is very high to develop an over inflated sense of confidence. Therefore, I truly try to maintain humility in everything I do.”

    Outside of the office, Mahtani takes great pride in her three children, and her loving family, and works to give back to her community. She works with Children’s Hope India and Habitat for Humanity to drive positive change outside the boardroom, and aims to pass on her legacy to her children and future generations. 

  • Are Multifamily Homes a Good Idea to Purchase?

    Are Multifamily Homes a Good Idea to Purchase?

    Buying a property is a major financial decision, especially when you want to build long-term wealth. While single-family homes remain a popular choice, multifamily homes offer an alternative for buyers seeking to earn rental income and invest in real estate. These properties contain two or more separate housing units, allowing owners to live in one unit and rent out the others, or to lease all units to tenants.

    However, purchasing a multifamily property requires careful planning. Understanding the benefits, costs, and potential risks can help you decide whether this type of real estate investment suits your financial goals.

    What Are Multifamily Homes?

    Multifamily homes are residential properties designed to accommodate multiple households in separate living units. Common examples include duplexes, triplexes, fourplexes, and apartment buildings.

    Each unit typically has its own living space, kitchen, and bathroom. Depending on the property’s layout, tenants may share certain areas, such as parking spaces or outdoor spaces.

    These properties can appeal to first-time investors and experienced real estate buyers. Some buyers purchase a duplex and live in one unit while renting out the other. Others invest in larger buildings to generate income from several tenants.

    Benefits of Purchasing Multifamily Homes

    Before investing, consider how multifamily properties may support your financial goals.

    1. Earn Rental Income

    One of the biggest advantages of multifamily homes is the opportunity to earn rental income from multiple units. Instead of depending on a single tenant, you can collect rent from several households.

    This income may help cover mortgage payments, property taxes, insurance, and maintenance expenses. If the rental income exceeds your operating costs and financing expenses, the property may generate positive cash flow.

    However, rental income is not guaranteed. Vacancy periods, late payments, and unexpected repairs can affect your earnings.

    2. Reduce Your Housing Expenses

    Multifamily properties can be attractive to buyers who want to own a home while building an investment. For example, you could purchase a duplex, live in one unit, and rent out the second.

    The rental income may help offset your monthly mortgage payment and other housing expenses. This strategy, often called house hacking, can make property ownership more manageable.

    Before purchasing, check the property’s financing requirements, rental restrictions, and expected operating costs.

    3. Build Long-Term Wealth

    Real estate may increase in value over time, although appreciation is never guaranteed. Multifamily homes offer the potential to benefit from property appreciation while earning rental income.

    As you pay down the mortgage, you may also build equity in the property. Over the long term, rental income, mortgage principal reduction, and appreciation could contribute to your overall wealth.

    4. Spread Vacancy Risk Across Units

    Owning a single-family rental means losing all rental income when the property becomes vacant. With multifamily homes, other occupied units may continue generating income when one tenant moves out.

    This can make income less dependent on an individual tenant. Nevertheless, several vacant units or major repairs can still create financial pressure.

    Potential Challenges of Multifamily Properties

    Despite their benefits, multifamily homes require more management than many single-family properties.

    Higher upfront costs: Purchasing a multifamily property may require a larger down payment, closing costs, and cash reserves, depending on the property and loan program.

    Ongoing maintenance: Multiple units can mean more plumbing issues, appliance repairs, and general maintenance responsibilities.

    Tenant management: Owners may need to handle lease agreements, rent collection, complaints, and tenant turnover. Hiring a property manager can reduce the workload but adds another expense.

    Financing requirements: Lenders may evaluate your credit, income, debt, reserves, and the property’s rental potential. Loan eligibility and down payment requirements vary by property type and occupancy.

    How to Decide If a Multifamily Home Is Right for You

    Start by reviewing your budget and investment goals. Calculate expected rental income and subtract mortgage payments, property taxes, insurance, maintenance, utilities, vacancy allowances, and management fees.

    Research local rental demand and compare similar properties before making an offer. You should also inspect the building, review its financial records, and keep emergency savings for unexpected expenses.

    If you plan to live in one unit, consider whether the location, layout, and monthly costs suit your household.

    Ready to Explore Multifamily Homes?

    Multifamily homes can be a good investment for buyers looking to earn rental income, build equity, and benefit from potential property appreciation. Before purchasing, research local rental demand, calculate your expected expenses, and review your financing options. 

    If you are planning to buy a multifamily property, contact Shaleen Mahtani at 201-745-3426 or shaleenmahtani@gmail.com to discuss your mortgage options and take the next step toward your real estate investment goals.

  • Purchasing an Investment Property: 7 Tips for Smart Investors

    Purchasing an Investment Property: 7 Tips for Smart Investors

    Purchasing an investment property can be a valuable way to build long-term wealth, earn rental income, and diversify your financial portfolio. However, real estate investing requires careful planning, market research, and a clear understanding of the costs involved. Whether you are buying your first rental property or expanding your existing portfolio, making informed decisions can help you avoid costly mistakes.

    Before purchasing an investment property, consider these seven practical tips to help you evaluate opportunities and make a confident investment decision.

    1. Define Your Investment Goals

    Start by deciding what you want to achieve with your investment property. Some investors focus on generating monthly rental income, while others prioritize long-term appreciation or a combination of both.

    Your goals will influence the type of property you choose, its location, and your financing strategy. For example, a property in an established rental market may appeal to investors seeking consistent rental income. Meanwhile, an area experiencing economic growth may offer potential for future property value increases.

    Set realistic expectations and choose an investment strategy that matches your financial situation and long-term objectives.

    2. Research the Local Real Estate Market

    Location plays an important role in the success of a real estate investment. Before purchasing a property, research the local housing market, rental demand, employment opportunities, and neighborhood development.

    Compare property prices and rental rates in different neighborhoods. Consider access to public transportation, schools, shopping centers, and major employment areas, as these factors may influence tenant demand.

    It is also helpful to review vacancy rates and recent property sales. Thorough research can help you identify potential opportunities and avoid paying more than a property is worth.

    3. Calculate Your Budget and Additional Costs

    The purchase price is only one part of the total investment. You should also account for the down payment, closing costs, property taxes, insurance, maintenance, and possible homeowners association fees.

    If you plan to rent out the property, include expenses such as property management, advertising, repairs, and periods without tenants.

    Create a realistic budget before making an offer. Maintaining emergency savings is also important because unexpected repairs or vacancies can affect your cash flow.

    Understanding the full cost of ownership helps you determine whether a property fits your financial goals.

    4. Explore Your Financing Options

    Financing an investment property can differ from financing a primary residence. Lenders may apply different eligibility requirements, down payment expectations, interest rates, and reserve requirements.

    Before applying for a mortgage, review your credit profile, income, existing debts, and available savings. Compare loan options and evaluate how each payment structure affects your expected rental income.

    You should also account for the possibility of changes in interest rates if you choose an adjustable-rate mortgage.

    Speaking with a qualified mortgage professional can help you understand the available financing options and identify a loan structure that fits your investment plans.

    5. Evaluate Potential Rental Income

    A property’s rental income should be sufficient to support its operating expenses and financing costs. Research comparable rental properties to estimate a realistic monthly rent rather than relying on optimistic projections.

    Subtract expected expenses, including mortgage payments, taxes, insurance, maintenance, management fees, and vacancy allowances, from your projected rental income.

    For example, a property with attractive rent may still generate negative cash flow if its purchase price and ongoing expenses are too high.

    Reviewing these figures before purchasing an investment property helps you compare opportunities and understand their potential financial performance.

    6. Inspect the Property Carefully

    A property that looks attractive during a viewing may have hidden maintenance problems. Arrange a professional inspection before completing the purchase, where appropriate, and review the property’s condition carefully.

    Pay attention to the roof, plumbing, electrical systems, heating and cooling equipment, foundation, and signs of water damage. Ask about the age of major systems and any previous repairs.

    You should also review local zoning rules, rental regulations, insurance availability, and any restrictions that could affect your intended use.

    Identifying potential problems early can help you estimate repair costs and negotiate more effectively.

    7. Plan for Long-Term Management

    Owning an investment property involves responsibilities beyond purchasing it. You must find suitable tenants, collect rent, coordinate maintenance, and respond to tenant concerns while following applicable housing laws.

    Decide whether you will manage the property yourself or hire a professional property manager. Self-management may reduce expenses, but it requires time and consistent attention. Professional management adds costs but can simplify daily operations.

    Also, review your investment periodically. Changes in rental demand, expenses, property values, and personal financial goals may affect whether holding or selling the property makes sense.

    Make an Informed Investment Decision

    Purchasing an investment property requires careful planning, realistic financial expectations, and a clear understanding of the real estate market. With the right strategy, you can make informed decisions that support your long-term investment goals.

    If you need guidance on mortgage financing for your next investment property, Shaleen Mahtani can help you explore your options. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your mortgage needs. 

  • How Changes in the Mortgage Appraisal Process Affect Homebuyers in 2026

    How Changes in the Mortgage Appraisal Process Affect Homebuyers in 2026

    The Mortgage Appraisal Process is an important step when buying a home in the United States. It helps lenders determine whether a property’s market value supports the amount a buyer wants to borrow. In 2026, updates to appraisal reporting standards and the use of digital tools are changing how property valuations are handled, making it important for homebuyers to understand what these changes mean for their mortgage applications.

    For homebuyers, these developments may make the mortgage process more efficient, but understanding the changes is still important. Knowing what to expect can help you prepare for possible delays, understand your financing options, and make informed decisions when purchasing a home.

    What Is a Mortgage Appraisal?

    Before exploring the latest changes, it is helpful to understand the purpose of a mortgage appraisal. This process allows lenders to evaluate a property’s market value before approving a home loan.

    An appraiser considers several factors, including the property’s location, size, condition, features, and recent sales of comparable homes. The final valuation helps the lender assess whether the property provides sufficient collateral for the requested mortgage.

    A mortgage appraisal is different from a home inspection. An appraisal focuses on market value, while a home inspection examines the property’s physical condition and potential maintenance issues.

    What’s Changing in the Mortgage Appraisal Process in 2026?

    Mortgage appraisal procedures are evolving as the industry adopts more standardized reporting and digital tools. These developments aim to improve the consistency of property information and help lenders evaluate homes more efficiently.

    One important update is the introduction of the Uniform Appraisal Dataset (UAD) 3.6 and redesigned appraisal forms by Fannie Mae and Freddie Mac. According to Fannie Mae’s official guidelines for UAD 3.6, the new format is designed to capture property details in a more consistent and structured way. The new reporting standard is scheduled to become mandatory for new appraisal submissions on November 2, 2026. Eligible lenders may qualify for a temporary policy exception during the transition.

    Technology is also changing how some properties are evaluated. Depending on the loan and property, lenders may use desktop appraisals, digital property data collection, or eligible appraisal alternatives instead of requiring a traditional on-site appraisal in every case.

    These options do not remove the need for reliable property information. Instead, they change how that information may be collected and reviewed.

    How These Changes May Affect Homebuyers

    Understanding these updates can help buyers prepare for what may happen during the mortgage process. The impact will depend on the lender, property type, loan program, and valuation method used.

    1. A Potentially Faster Mortgage Process

    Digital tools and standardized reporting may help lenders review property information more efficiently. In eligible cases, alternative valuation options may also reduce the need for a traditional appraisal appointment.

    However, faster processing is not guaranteed. The timeline still depends on the lender, property documentation, and whether additional reviews are necessary.

    2. More Detailed Property Information

    Modern appraisal reporting is designed to capture property characteristics in a more structured format. Depending on the valuation method, this may include photographs, measurements, floor plans, and other relevant property details.

    For buyers, more consistent information may help lenders evaluate properties and identify potential concerns. However, an appraisal does not replace a professional home inspection.

    3. Different Appraisal Options

    Not every mortgage requires the same type of property valuation. Some eligible applications may qualify for alternatives, such as value acceptance or value acceptance with property data, depending on lender requirements and property eligibility.

    Buyers should not assume that every property qualifies for an appraisal waiver or alternative valuation. Ask your mortgage lender which option is available for your specific transaction.

    4. A Possible Impact on Closing Timelines

    Appraisal requirements can affect how quickly a mortgage moves toward closing. Scheduling issues, missing property information, or questions about the estimated value may require additional work.

    The transition to updated reporting standards may also require lenders and appraisal professionals to adjust their systems and procedures. Preparing documents early and responding promptly to lender requests can help prevent avoidable delays.

    What Should Homebuyers Do to Prepare?

    Although buyers cannot control every part of the appraisal process, taking a few practical steps can help make the experience smoother. Preparing early can also help you identify potential issues before they affect your closing date.

    • Ask your lender early: Find out which appraisal method your mortgage requires and whether an alternative is available.
    • Understand the valuation: Discuss the results with your lender if the appraised value differs from the purchase price.
    • Keep your documents ready: Provide requested property and transaction information promptly.
    • Plan your closing timeline: Allow enough time for appraisal reviews and additional lender requirements.
    • Consider a home inspection: An appraisal may not identify every maintenance issue or hidden defect.

    Make Your Homebuying Journey Easier in 2026

    Mortgage appraisal changes are bringing more standardized reporting and technology into property valuation. While these developments may improve efficiency, appraisal requirements will continue to depend on the property, loan program, and lender.

    Working with an experienced mortgage professional can help you understand your options, prepare for the next steps, and avoid common surprises during the homebuying process.

    If you’re planning to buy a home in 2026, contact Shaleen Mahtani at 201-745-3426 or shaleenmahtani@gmail.com to discuss your mortgage options. Lending services are available in all 50 states.

  • Mortgage Prequalification: How It Works and Why It Matters 

    Mortgage Prequalification: How It Works and Why It Matters 

    Buying a home is a major financial decision, and knowing how much you can borrow can make the process easier. Mortgage prequalification is one of the first steps many homebuyers take before starting their home search. It can give you an early estimate of your potential loan amount and help you understand what price range may fit your finances.

    What Is Mortgage Prequalification?

    Mortgage prequalification is an initial assessment of your financial situation by a mortgage lender. The lender typically asks about information such as your income, debts, assets, and estimated credit profile. Based on the information you provide, the lender can estimate how much you may qualify to borrow.

    Unlike a full mortgage application, prequalification is generally an early-stage process. It does not mean that your mortgage has been approved or that the lender is guaranteeing you a loan.

    The exact process can vary between lenders. Some may rely mainly on information you provide, while others may review financial documents or perform a credit check.

    Why Is Mortgage Prequalification Important?

    Getting prequalified can be helpful before you begin seriously looking at homes. One of the biggest advantages is that it gives you a better idea of your potential budget.

    For example, if a lender estimates that you may qualify for a $400,000 mortgage, you can focus your home search around a realistic price range instead of looking at properties that may be outside your budget.

    Mortgage prequalification can also help you identify potential financial issues early. If your income, debts, credit history, or available funds could affect your borrowing ability, discussing them with a mortgage professional before making an offer may give you more time to plan.

    What Information Is Needed for Prequalification?

    The information required depends on the lender, but you may be asked about:

    • Annual or monthly income
    • Employment history
    • Monthly debt payments
    • Estimated credit score
    • Savings and other assets
    • Down payment funds
    • Desired loan amount
    • Estimated home purchase price

    Providing accurate information is important. Your prequalification estimate is only as useful as the financial information behind it.

    Mortgage Prequalification vs. Preapproval

    Mortgage prequalification and preapproval are often confused, but they are not the same.

    • Prequalification is generally an early estimate based on information about your financial situation. It can help you understand your potential borrowing range before moving further into the homebuying process.
    • Mortgage preapproval usually involves a more detailed review of your finances and documentation. Depending on the lender, this may include verifying income, assets, debts, employment, and credit information.

    A preapproval can carry more weight when you are ready to make an offer, but it is still not the same as final loan approval. The mortgage process continues after an offer is accepted, and the lender may require additional documentation and property-related information.

    Does Prequalification Affect Your Credit Score?

    Whether mortgage prequalification affects your credit depends on the lender and the type of credit inquiry they use. Some lenders may provide an estimate without a hard credit inquiry, while others may check your credit as part of the process.

    Before proceeding, ask the lender whether prequalification requires a hard or soft credit inquiry. This can help you understand what to expect.

    When Should You Get Prequalified?

    Many buyers choose to get prequalified before beginning their home search. Starting early can help you establish a realistic budget and understand what factors may influence your mortgage options.

    However, remember that a prequalification is an estimate, not a guarantee. Your final loan terms can change after the lender completes a full review of your application and supporting documents.

    Start Your Homebuying Journey With Confidence

    Mortgage prequalification can be a useful first step toward buying a home. It helps you understand your potential borrowing range, plan your budget, and approach the home search with clearer expectations.

    If you’re planning to buy a home, Shaleen Mahtani can help you understand the mortgage prequalification process and explore financing options that may fit your situation. Lending services are available in all 50 states. To discuss your home financing goals, call Shaleen at 201-745-3426 or email shaleenmahtani@gmail.com.

  • Mortgage Prequalification vs. Preapproval: What’s the Difference?

    Mortgage Prequalification vs. Preapproval: What’s the Difference?

    If you’re planning to buy a home, you may hear the terms mortgage prequalification and mortgage preapproval used interchangeably. While both can help you understand your potential borrowing power, they are not the same. Knowing the difference between mortgage prequalification vs. preapproval can help you choose the right step before you start shopping for a home.

    What Is Mortgage Prequalification?

    Mortgage prequalification is generally an early step in the homebuying process. It gives you an estimate of how much you may be able to borrow based on information you provide about your income, debts, assets, and financial situation.

    Depending on the lender, prequalification may involve a basic review of your financial information. In some cases, the lender may not verify all of the information at this stage. Because of this, a prequalification is usually an estimate rather than a firm commitment to lend.

    Prequalification can still be useful when you are just beginning to explore your options. It can give you a general idea of your potential price range and help you understand what monthly mortgage payment may fit your budget.

    What Is Mortgage Preapproval?

    Mortgage preapproval is a more detailed step. A lender typically reviews financial information and supporting documents to determine how much you may be eligible to borrow. This can include reviewing your income, assets, debts, credit history, and other information needed for the mortgage application.

    A preapproval can give you a stronger idea of your potential loan amount and may make you a more competitive buyer when you are ready to make an offer.

    However, mortgage preapproval does not mean your mortgage is guaranteed. The final loan approval can still depend on factors such as the property, appraisal, title, documentation, and other underwriting requirements.

    Mortgage Prequalification vs. Preapproval

    The main difference between mortgage prequalification and preapproval is the level of financial review involved.

    Prequalification is typically more informal and can be useful when you are at the beginning of your home search. It helps you estimate your potential borrowing range without going through the full mortgage process.

    Preapproval generally involves a more thorough review of your financial information. Because it provides a more detailed assessment, sellers and real estate agents may view a preapproval more favorably when you are ready to submit an offer.

    Both can be helpful, but they serve different purposes. If you are still considering whether to buy and want a general estimate, prequalification may be a good starting point. If you are actively looking at homes and preparing to make offers, getting preapproved can be a more practical next step.

    Which One Should You Get First?

    The right choice depends on where you are in the homebuying process. If you are researching the market, comparing mortgage options, or trying to understand your potential budget, prequalification can help you get started.

    If you are serious about buying a home soon, preapproval can provide a clearer picture of your financing options before you begin making offers. It can also help you set a realistic home price range and show sellers that you have taken steps to arrange financing.

    Keep in mind that the amount you may qualify for is not necessarily the amount you should spend. Your budget should also account for property taxes, homeowners insurance, maintenance, closing costs, and other homeownership expenses.

    Get Help Understanding Your Mortgage Options

    Understanding the difference between mortgage prequalification vs. preapproval can make the homebuying process less confusing. Whether you are just starting to explore your options or are ready to purchase, getting guidance from an experienced mortgage professional can help you make informed decisions.

    For personalized mortgage guidance, contact Shaleen Mahtani at 201-745-3426 or shaleenmahtani@gmail.com. Lending services are available in all 50 states.

  • Mortgage Preapproval: What It Is and Why It Matters When Buying a Home 

    Mortgage Preapproval: What It Is and Why It Matters When Buying a Home 

    Buying a home is a major financial decision, and knowing how much you can afford is an important first step. A mortgage preapproval can help you understand your potential borrowing power before you start making offers. It can also show sellers that you are a serious and financially prepared buyer.

    What Is Mortgage Preapproval?

    Mortgage preapproval is a process in which a lender reviews your financial information to estimate how much you may be able to borrow for a home. The lender typically considers factors such as your income, employment, credit history, debts, assets, and down payment.

    If you meet the lender’s requirements, you may receive a preapproval letter stating the approximate loan amount you may qualify for. Keep in mind that preapproval is not the same as final mortgage approval. Your loan will still need to go through the full underwriting process before closing.

    Why Is Mortgage Preapproval Important?

    Getting preapproved before shopping for a home can make the buying process easier. One of the biggest benefits is that it gives you a clearer idea of your potential home-buying budget.

    A mortgage preapproval can also make your offer more attractive to sellers. When multiple buyers are interested in a property, a seller may prefer an offer from someone who has already spoken with a lender and demonstrated that they are prepared to finance the purchase.

    Preapproval can also help you move faster when you find the right home. Instead of starting the financing process after making an offer, you have already completed an important part of the initial mortgage process.

    What Documents Are Needed for Preapproval?

    The exact requirements vary by lender and borrower, but you may need to provide documents such as:

    • Recent pay stubs
    • W-2 forms or tax returns
    • Bank and investment account statements
    • Information about existing debts
    • Employment information
    • Identification
    • Documentation related to other sources of income or assets

    Providing accurate and complete information can help make the preapproval process more efficient.

    Does Preapproval Affect Your Credit?

    A lender may review your credit as part of the mortgage preapproval process. Depending on the lender and the type of credit inquiry, this may involve a hard credit inquiry, which can have a temporary effect on your credit score.

    Because mortgage shopping may involve contacting multiple lenders, it is helpful to understand how credit inquiries are handled and to complete your mortgage shopping within an appropriate timeframe.

    How Long Does Mortgage Preapproval Last?

    A mortgage preapproval is generally valid for a limited period, although the timeframe varies by lender. If you do not purchase a home before the preapproval expires, the lender may need to update your financial information and issue a new preapproval.

    Your financial situation can also affect your preapproval. Avoid taking on significant new debt, changing jobs unnecessarily, or making major financial changes without discussing them with your mortgage professional.

    Mortgage Preapproval vs. Prequalification

    Preapproval and prequalification are sometimes used interchangeably, but they are not always the same. Prequalification may provide an initial estimate based on information you provide, while preapproval generally involves a more detailed review of your financial situation.

    If you are serious about buying a home, asking your lender exactly what their preapproval process includes can help you understand how strong your financing position is.

    Start Your Homebuying Journey With Confidence

    A mortgage preapproval can help you understand your potential budget, strengthen your offer, and prepare you for the homebuying process. Before beginning your home search, speak with a qualified mortgage professional to review your financial situation and available loan options.

    For personalized mortgage guidance, contact Shaleen Mahtani at 201-745-3426 or shaleenmahtani@gmail.com. Lending services are available in all 50 states.

  • Why Mortgage Rates Change Daily: What Homebuyers Should Know

    Why Mortgage Rates Change Daily: What Homebuyers Should Know

    If you are shopping for a home, you may notice that mortgage rates change daily. A rate you see in the morning may be different later that day or the next time you check. This can make it difficult to know when to apply for a mortgage or lock in your rate.

    Financial markets, economic conditions, inflation expectations, and other factors influence mortgage rates. Understanding why mortgage rates change daily can help you make more informed decisions during the homebuying process.

    Mortgage Rates Follow Financial Markets

    One of the main reasons mortgage rates change is that they are connected to the broader financial markets. Mortgage loans are often packaged into mortgage-backed securities (MBS), which are bought and sold by investors.

    The prices and yields of these securities can change as investors respond to economic news and market conditions. Mortgage rates generally have a close relationship with Treasury yields, although they do not always move at exactly the same pace.

    When market conditions change, lenders may adjust the rates they offer to borrowers.

    Inflation Can Affect Mortgage Rates

    Inflation is another important factor behind changes in mortgage rates. When inflation remains high or investors expect inflation to increase, interest rates can come under upward pressure.

    The Federal Reserve also plays an important role in the interest-rate environment. While the Federal Reserve does not directly set the rate you receive on a 30-year fixed mortgage, its monetary policy can influence financial markets and borrowing conditions.

    Mortgage rates can also move based on expectations about future Federal Reserve decisions, rather than only after a policy change actually occurs.

    Economic News Can Move Rates

    Mortgage rates can respond quickly to new economic information. Reports about employment, inflation, economic growth, consumer spending, and other financial indicators can change investor expectations.

    For example, stronger-than-expected economic data may affect expectations about future interest rates, while weaker economic data may produce a different market reaction. Because investors continually respond to new information, mortgage rates can change throughout the week.

    This is one reason two rate quotes received on different days may not be identical.

    Your Loan Details Also Matter

    Market conditions are only part of the story. The mortgage rate offered to you can also depend on factors related to your financial situation and the loan you choose.

    According to the Consumer Financial Protection Bureau, factors that can affect mortgage pricing include credit score, loan amount, down payment, loan term, property location, loan type, and whether the mortgage has a fixed or adjustable rate.

    This means two borrowers could receive different mortgage rates even when they apply around the same time.

    Why Mortgage Rates Can Change During the Same Day

    Mortgage rates do not necessarily update only once each morning. Lenders can adjust pricing as market conditions change.

    If financial markets move significantly during the day, lenders may change their pricing accordingly. This is why a mortgage rate quote should be treated as a current offer rather than a permanent number unless the rate has been locked.

    The Consumer Financial Protection Bureau notes that mortgage interest rates can change daily and sometimes hourly.

    What Is a Mortgage Rate Lock?

    A mortgage rate lock is an agreement that keeps your interest rate from changing for a specified period, provided you meet the conditions of the lock and close within the agreed timeframe.

    Rate locks are commonly available for periods such as 30, 45, or 60 days, although options vary by lender. If your rate is not locked, it can change before closing.

    Before locking your rate, ask your lender about the lock period, extension costs, and what could cause the rate to change.

    Talk to a Mortgage Professional

    Understanding why mortgage rates change daily can make the homebuying process easier to navigate. Instead of focusing on a single daily rate, consider your loan type, financial situation, closing timeline, and the overall cost of the mortgage.

    If you are planning to buy a home or refinance, Shaleen Mahtani can help you understand your mortgage options and current market conditions. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your mortgage needs.

  • What Is a Digital Mortgage and How Does It Work?

    What Is a Digital Mortgage and How Does It Work?

    Buying a home involves several steps, from comparing loan options to submitting financial documents and completing the closing process. A digital mortgage can make many of these steps faster and more convenient by allowing borrowers to complete much of the mortgage process online.

    Instead of handling every document in person or through paper forms, borrowers can use digital tools to submit information, upload documents, review disclosures, and communicate with their mortgage lender.

    What Is a Digital Mortgage?

    A digital mortgage is a home loan process that uses online technology to simplify and automate parts of the mortgage application and approval process. It does not necessarily mean that every step happens completely online. Some parts may still require a borrower to speak with a mortgage professional, provide additional documentation, or complete certain closing requirements.

    The main goal of a digital mortgage is to reduce paperwork and make the overall mortgage process more efficient.

    How Does a Digital Mortgage Work?

    The process can vary between lenders, but a digital mortgage generally follows several common steps.

    1. Complete an Online Application

    The borrower starts by completing a mortgage application online. This typically includes information about income, employment, assets, debts, and the property being purchased or refinanced.

    Some digital mortgage platforms may allow borrowers to securely provide financial information electronically, which can reduce the need to enter the same information multiple times.

    2. Upload Financial Documents

    Borrowers may be able to upload documents such as pay stubs, bank statements, tax documents, and identification through a secure online portal.

    In some cases, lenders may also use electronic verification systems to confirm certain financial or employment information.

    3. Review and Underwriting

    Once the application and required documents are submitted, the lender reviews the borrower’s financial information. Technology can help organize documents and identify information needed for underwriting.

    However, digital technology does not replace the need for appropriate mortgage review. The lender still evaluates the borrower’s financial situation and the loan requirements before making a lending decision.

    4. Electronic Disclosures and Closing

    Digital mortgage platforms may allow borrowers to receive and sign certain disclosures electronically. Depending on the lender, loan type, and state requirements, some closing documents may also be completed electronically.

    The exact closing process varies, so borrowers should understand which steps can be completed online and which may require an in-person appointment.

    Benefits of a Digital Mortgage

    A digital mortgage can offer several potential benefits for homebuyers and homeowners. Online applications can make it easier to submit information from home, while electronic document management can reduce paperwork.

    Digital tools may also make it easier to track the progress of a mortgage application and communicate with the lending team. For borrowers who prefer online services, this can make the mortgage process more convenient.

    However, a digital mortgage does not automatically mean a faster approval or better loan terms. The timeline depends on factors such as the borrower’s financial situation, documentation, property, loan type, and lender’s process.

    Is a Digital Mortgage Right for You?

    A digital mortgage may be useful if you prefer managing documents and communication online. Still, choosing a mortgage involves more than selecting a convenient application process. It is important to understand the loan program, interest rate, costs, repayment terms, and other requirements before making a decision.

    If you are considering buying a home or refinancing, Shaleen Mahtani can help you understand your mortgage options and guide you through the lending process. For personalized mortgage guidance, call 201-745-3426 or email shaleenmahtani@gmail.com. 

  • What Are Nonbank Mortgage Lenders and How Do They Work?

    What Are Nonbank Mortgage Lenders and How Do They Work?

    When looking for a home loan, you may come across the term nonbank mortgage lenders. These companies provide mortgage financing but are not traditional banks. They have become an important part of the mortgage industry and give homebuyers another option when searching for the right loan.

    Understanding how nonbank mortgage lenders work can help you compare different financing options and make a more informed decision when buying or refinancing a home.

    What Is a Nonbank Mortgage Lender?

    A nonbank mortgage lender is a company that provides home loans without operating as a traditional bank. Unlike banks, these lenders generally focus on mortgage lending rather than offering services such as checking accounts, savings accounts, or credit cards.

    Some nonbank lenders operate primarily online, while others work through mortgage loan officers who guide borrowers through the application and financing process.

    Nonbank lenders can offer a variety of mortgage products, depending on their business model and lending programs. These may include conventional loans, FHA loans, jumbo loans, and other mortgage options for qualified borrowers.

    How Do Nonbank Mortgage Lenders Work?

    The mortgage process with a nonbank lender is generally similar to the process at a traditional bank.

    The borrower begins by submitting a mortgage application and providing information about income, employment, assets, debts, credit history, and the property being purchased. The lender then reviews the borrower’s financial information to determine eligibility.

    If the application moves forward, the lender may request additional documentation, verify income and assets, and arrange a property appraisal when required. The loan then goes through underwriting, where the lender evaluates the borrower’s financial situation and the details of the mortgage.

    Once the loan requirements are satisfied, the borrower can move toward closing.

    It is also important to understand that the company that originates your mortgage may not always be the same company that services it after closing. Mortgage servicing typically involves collecting payments, managing escrow accounts, and handling other day-to-day tasks related to the loan.

    How Are Nonbank Mortgage Lenders Different From Banks?

    The biggest difference is the type of financial services each company provides.

    Traditional banks typically offer mortgages along with checking and savings accounts, credit cards, personal loans, and other banking products. Nonbank mortgage lenders generally concentrate more heavily on home financing.

    Because mortgage lending is their primary business, nonbank lenders may have specialized mortgage teams and a range of loan programs designed for different types of borrowers.

    However, there is no single mortgage option that is right for everyone. Rates, fees, loan programs, eligibility requirements, and customer service can vary from one lender to another.

    What Should You Compare When Choosing a Lender?

    Whether you are considering a traditional bank or a nonbank mortgage lender, it is important to look beyond the advertised interest rate.

    Before choosing a mortgage, compare:

    • Interest rate and Annual Percentage Rate (APR)
    • Loan terms and repayment period
    • Closing costs and lender fees
    • Down payment requirements
    • Mortgage insurance requirements
    • Fixed-rate and adjustable-rate options
    • Monthly payment
    • Loan eligibility requirements

    Comparing these details can help you understand the overall cost of borrowing rather than focusing on one number.

    You may also want to compare the level of communication and guidance you receive during the mortgage process. Having a mortgage professional who clearly explains your options can make the process easier to understand.

    Are Nonbank Mortgage Lenders Right for You?

    Nonbank mortgage lenders provide an alternative to traditional banks for borrowers looking for home financing. Their mortgage-focused approach and variety of loan programs can make them worth considering when comparing lenders.

    Before making a decision, review the complete terms of each mortgage and consider how the loan fits your financial situation and long-term goals.

    If you are planning to buy a home or refinance an existing mortgage, Shaleen Mahtani can help you explore your mortgage options. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your financing needs.

  • Adjustable-Rate Mortgage (ARM): How It Works and What to Know

    Adjustable-Rate Mortgage (ARM): How It Works and What to Know

    An adjustable-rate mortgage (ARM) is a home loan with an interest rate that can change over time. Unlike a fixed-rate mortgage, which generally keeps the same interest rate throughout the loan term, an ARM usually starts with a fixed rate for a specific period. After that period ends, the rate can adjust based on market conditions.

    Understanding how an adjustable-rate mortgage works can help homebuyers decide whether this type of loan fits their financial plans and long-term goals.

    What Is an Adjustable-Rate Mortgage (ARM)?

    An adjustable-rate mortgage (ARM) is a mortgage where the interest rate can change after an initial fixed-rate period. ARMs are commonly described with two numbers, such as 5/1 ARM or 7/1 ARM.

    The first number represents how many years the initial interest rate remains fixed. The second number indicates how often the interest rate can adjust after that period. For example, with a 5/1 ARM, the rate typically remains fixed for the first five years and may then adjust once each year.

    The specific terms, adjustment schedule, and limits depend on the mortgage program and loan agreement.

    How Does an ARM Work?

    An ARM typically has three important components: the initial interest rate, the index, and the margin.

    During the initial period, borrowers make payments based on the starting interest rate. Once the fixed period ends, the mortgage rate may change according to the terms of the loan.

    The new rate is generally calculated using an index plus a margin set by the lender. While the index can change with market conditions, the margin typically remains the same throughout the loan.

    ARMs also commonly include rate caps, which limit how much the interest rate can increase or decrease at each adjustment and over the life of the loan. These caps can help borrowers understand the potential range of future payments.

    Potential Benefits of an Adjustable-Rate Mortgage

    One potential advantage of an adjustable-rate mortgage is that the initial interest rate may be lower than the rate available on some fixed-rate mortgages. This can result in lower initial monthly payments.

    An ARM may also make sense for borrowers who expect to move or refinance before the adjustable period begins. However, future rates and refinancing opportunities cannot be guaranteed.

    For some buyers, the lower initial rate can provide greater flexibility during the early years of homeownership.

    Risks to Consider With an ARM

    The main risk of an adjustable-rate mortgage is that the interest rate can increase after the initial fixed period. If rates rise, monthly mortgage payments may also increase.

    This can make budgeting more difficult, especially for homeowners who plan to keep the mortgage for many years.

    Borrowers should also understand the loan’s adjustment frequency, initial and subsequent rate caps, lifetime cap, index, margin, and other terms before choosing an ARM. Looking only at the initial interest rate may not provide a complete picture of the loan’s long-term cost.

    Is an Adjustable-Rate Mortgage Right for You?

    An adjustable-rate mortgage may be worth considering if you understand how the loan works and are financially prepared for possible payment changes. It can be particularly relevant for buyers who expect to sell or refinance before the rate begins adjusting, although those plans may change.

    Before choosing an ARM, compare it with fixed-rate mortgage options and consider how higher future payments could affect your budget.

    A mortgage professional can help you review different loan options, understand the terms, and determine how each option fits your financial situation.

    Explore Your Adjustable-Rate Mortgage Options

    If you are considering an adjustable-rate mortgage, getting a clear understanding of the loan terms and potential payment changes is an important first step. Shaleen Mahtani can help you review your mortgage options and understand how an ARM may fit your home financing goals. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your options.

  • Credit Score for Mortgage: What Score Do You Need to Buy a Home?

    Credit Score for Mortgage: What Score Do You Need to Buy a Home?

    Your credit score is one of the key factors lenders consider when you apply for a mortgage. It can affect your loan eligibility, interest rate, down payment requirements, and overall borrowing costs. Understanding the credit score for mortgage requirements can help you prepare financially before you start shopping for a home.

    What Credit Score Do You Need for a Mortgage?

    There is no single credit score required for every mortgage. Different loan programs have different guidelines, and lenders may also consider your income, debt, employment history, down payment, and overall financial profile.

    Some conventional mortgage programs may accept borrowers with credit scores around 620, while government-backed loans can have different minimum requirements. However, meeting a minimum score does not automatically guarantee approval. A stronger credit profile may give you access to more mortgage options and potentially better loan terms.

    How Your Credit Score Affects Your Mortgage

    Your credit score helps lenders assess how you have managed credit in the past. A higher score generally indicates a lower perceived credit risk, while a lower score may make lenders more cautious.

    Your score can influence the interest rate offered on your mortgage. Even a small difference in your interest rate can affect your monthly payment and the total amount of interest you pay over the life of the loan.

    Because of this, improving your credit before applying for a mortgage may help you qualify for more favorable financing terms.

    Credit Score Requirements by Loan Type

    Mortgage requirements vary depending on the type of loan you choose. Conventional loans often have stricter credit requirements than some government-backed programs.

    FHA loans may allow borrowers with lower credit scores to qualify under certain circumstances, while VA and USDA loans have their own eligibility and lender requirements. Keep in mind that lenders can apply additional requirements beyond the basic program guidelines.

    Before applying, ask your lender which credit score requirements apply to the specific mortgage program you are considering.

    How to Improve Your Credit Before Buying a Home

    If your credit score is lower than you would like, taking steps to improve it before applying for a mortgage can be beneficial. Start by reviewing your credit reports and checking for inaccurate information.

    Pay your bills on time and try to reduce outstanding credit card balances. Avoid applying for several new credit accounts in a short period, as multiple credit inquiries may affect your credit profile.

    It is also important to avoid taking on unnecessary debt while preparing to purchase a home. Giving yourself several months to improve your finances may put you in a stronger position when you apply for a mortgage.

    Does a Higher Credit Score Mean a Better Mortgage?

    A higher credit score can make it easier to qualify for certain mortgage options and may help you receive more competitive interest rates. However, your credit score is only one part of the mortgage approval process.

    Lenders typically review your debt-to-income ratio, income, employment, assets, down payment, and other financial information. Two borrowers with similar credit scores may receive different loan terms because their overall financial situations are different.

    Check Your Credit Before Applying

    Before submitting a mortgage application, review your credit profile and understand where you stand. Knowing your credit score for mortgage eligibility can help you identify potential issues and determine whether you may benefit from improving your credit first.

    If you are unsure which mortgage option fits your financial situation, speaking with a qualified mortgage professional can help you understand the available programs, credit requirements, and potential loan terms. Taking time to prepare can make the home-buying process more informed and manageable.

    Ready to Explore Your Mortgage Options?

    Your credit score is an important part of the home-buying process, but it is not the only factor lenders consider. If you have questions about your mortgage options or want to understand how your credit profile may affect your home financing, contact Shaleen Mahtani at 201-745-3426 or shaleenmahtani@gmail.com. Lending services are available in all 50 states.

  • How Much Should You Save Before Buying a House?

    How Much Should You Save Before Buying a House?

    Buying a house is a major financial decision, and knowing how much to save before buying a house can help you prepare with confidence. While many buyers focus on the down payment, there are several other costs to consider, including closing costs, moving expenses, and emergency savings.

    The amount you need depends on the home price, loan type, lender requirements, and your personal financial situation. Planning for these expenses in advance can make the homebuying process smoother and help you avoid financial stress.

    Start With Your Down Payment

    The down payment is usually one of the biggest upfront expenses when buying a home. A common target is 20% of the purchase price, but you may not always need that much.

    Some mortgage programs allow qualified buyers to purchase a home with a lower down payment. For example, certain conventional loans may require as little as 3%, while FHA loans can require as little as 3.5% for eligible borrowers.

    A lower down payment can make homeownership more accessible, but it may also result in additional costs, such as mortgage insurance. Talk with your lender to understand which loan options fit your situation.

    Don’t Forget Closing Costs

    When calculating how much to save before buying a house, remember to budget for closing costs. These expenses can include lender fees, appraisal costs, title services, recording fees, and other charges related to finalizing your mortgage and purchase.

    Closing costs often add several percent to the purchase price, although the exact amount varies by location, lender, loan program, and transaction.

    For example, if you purchase a $400,000 home, even a few percent in closing costs can represent thousands of dollars. Ask your lender for a Loan Estimate early in the process so you have a better idea of your expected expenses.

    Keep an Emergency Fund

    It can be tempting to put all your savings toward buying a house, but having cash left after closing is important. Homeowners can face unexpected expenses, including repairs, maintenance, appliance replacement, or changes in income.

    Ideally, maintain an emergency fund separate from the money you plan to use for your down payment and closing costs. Many financial experts recommend keeping several months of essential expenses available, although the right amount depends on your income, job stability, debts, and household needs.

    Budget for Moving and Initial Expenses

    Your homebuying savings should also account for costs that may come after closing. Moving expenses, furniture, utility deposits, repairs, and other immediate needs can add up quickly.

    You may also want to make small improvements before fully settling into your new home. Creating a separate budget for these expenses can help prevent you from relying on credit cards or loans immediately after purchasing the property.

    How Much Should You Save Before Buying a House?

    There is no single savings amount that works for every buyer. A practical goal is to have enough for your expected down payment and closing costs while keeping an emergency fund and some additional cash for moving and initial home expenses.

    For example, if you are considering a $400,000 home, you might need to plan for a down payment, several thousand dollars in closing costs, moving expenses, and emergency savings. Your lender can provide more specific estimates based on your mortgage program and financial profile.

    Plan Your Savings Before You Start House Hunting

    Knowing how much to save before buying a house can help you set a realistic budget and avoid surprises. Start by reviewing your income, monthly expenses, debts, credit profile, and available savings.

    If you’re planning to buy a home and want to understand your financing options, speaking with an experienced mortgage professional can help you determine what you may need upfront and which loan programs may be available to you.

    Ready to plan your home purchase? Contact Shaleen Mahtani at 201-745-3426 or shaleenmahtani@gmail.com to discuss your mortgage options and take the next step toward homeownership.

  • Shaleen Mahtani’s Journey in Mortgage Banking

    Shaleen Mahtani’s Journey in Mortgage Banking

    When I look back at my career in mortgage banking, I realize that my journey has been shaped by much more than professional milestones. It has been shaped by hard work, family, challenges, resilience, and the people I have had the opportunity to serve.

    I have spent more than two decades in the mortgage industry, but the lessons that guide me today began long before I entered the business. My experiences growing up, working while attending school, and watching my parents make sacrifices for our family taught me the value of dedication and perseverance.

    Those lessons continue to influence how I approach my career and my clients today.

    Learning the Value of Hard Work

    I moved to the United States when I was 14 years old. I started working while attending high school and continued working throughout college. Those early experiences taught me the importance of showing up, taking responsibility, and making the most of every opportunity.

    My parents made many sacrifices to give my brother and me better opportunities. My mother, in particular, has always been an important source of inspiration for me.

    When our family faced difficult circumstances, I watched my mother continue to move forward and support us. Her strength taught me that difficult situations do not have to define your future. Sometimes, you simply have to keep going and do the best you can with what you have.

    That lesson has stayed with me throughout my career.

    Finding My Path Into Mortgage Banking

    I earned my BBA in Finance from the University of Georgia. Initially, I thought I would pursue a career in investment banking. However, my professional path eventually took me in a different direction.

    In 1999, after the birth of my second child, I entered the mortgage industry as a mortgage banking assistant. Starting at the ground level allowed me to learn the business step by step.

    I learned how the mortgage process worked, developed my industry knowledge, and gained an understanding of what clients need when making major financial decisions.

    After two years, I moved into an independent banking role and continued building my career.

    My professional journey, including the experiences and values that shaped my career, has also been discussed in a published profile about my career, resilience, and professional legacy.

    Growing Through Leadership

    In 2003, I joined Wells Fargo and helped develop its Private Mortgage Banking Division in New Jersey.

    At that point in my career, I was not only focused on my own growth. I was also learning what it meant to lead a team, build relationships, and create an environment where people could succeed.

    During my time there, the division grew from three people to 36 direct reports. My group also received recognition for growth and profitability, and I received recognition through the bank’s Leaders Club and Presidents Club programs.

    While I am proud of those accomplishments, I believe the most valuable part of that experience was everything I learned along the way.

    Starting as an assistant and eventually moving into leadership gave me a broader understanding of mortgage banking. It taught me to appreciate every part of the process and the people who make it work.

    What Resilience Has Taught Me

    Mortgage banking can be demanding. Market conditions change, transactions can become complicated, and clients sometimes face unexpected challenges.

    Over the years, I have learned not to let a difficult situation stop me. Instead, I try to understand what is happening, look at the available options, and focus on finding a practical path forward.

    I believe that approach is just as important when working with clients. Buying a home or securing financing can feel overwhelming, especially when someone is unfamiliar with the process. My role is to listen, explain the options clearly, and help clients move forward with greater understanding.

    The mortgage industry is also changing rapidly. Technology and artificial intelligence are creating new opportunities to improve and automate parts of the mortgage process. I believe continuing to learn and adapt will remain important as the industry evolves.

    Building a Professional Legacy

    At this stage of my career, I think about my professional legacy differently.

    It is not only about the positions I have held or the recognition I have received. I want my work to reflect hard work, integrity, resilience, and a genuine commitment to the people I serve.

    I also hope that, when the time is right, I can pass my business on to the next generation. To me, that would be a meaningful way to continue the values my parents passed down to me.

    Today, I continue helping clients navigate their mortgage and home financing options. Every client and every transaction brings an opportunity to learn something new and make the process a little easier to understand.

    Looking back, I am grateful for the challenges that helped shape me, the people who supported me, and the clients who trusted me throughout my career.

    If you are considering buying a home, refinancing, or exploring mortgage options, I would be happy to discuss your financing needs. Contact me at 201-745-3426 or shaleenmahtani@gmail.com. Lending services are available in all 50 states.

  • What Nearly 27 Years in Mortgage Banking Taught Me About Serving Clients

    What Nearly 27 Years in Mortgage Banking Taught Me About Serving Clients

    A mortgage is more than a financial transaction. For many people, buying a home is one of the biggest financial decisions they will make. After nearly 27 years in mortgage banking, I have learned that helping clients successfully navigate this process requires more than understanding numbers and loan programs. It requires communication, patience, responsiveness, and trust.

    My career in mortgage banking has been shaped by many experiences, but some of my most important lessons began long before I entered the industry.

    Hard Work Starts With the Right Example

    My mother has always been one of my biggest influences. She brought our family to the United States when I was 14 and worked hard to give my brother and me opportunities for a better future.

    When my father became seriously ill, my mother had to take on even more responsibility. Watching her continue moving forward during difficult times taught me the importance of perseverance.

    Those lessons have stayed with me throughout my career. I learned early that success does not happen overnight. It comes from showing up, staying focused, learning from challenges, and continuing to move forward.

    Experience Has Taught Me the Importance of Communication

    Mortgage lending involves financial terms, paperwork, deadlines, and decisions that can sometimes feel overwhelming to clients. One of the biggest lessons I have learned is that knowledge is only useful when you can explain it clearly.

    Clients should not feel that they need to understand complicated mortgage terminology before they can make informed decisions.

    My role is to help explain the process in straightforward language, answer questions, and make sure clients understand what is happening at each stage of their mortgage journey.

    After nearly three decades in the business, I have seen that clear communication can make a complicated process easier to understand.

    Being Responsive Matters

    Mortgage questions do not always happen during traditional business hours. A client may have a question about an offer, financing, documentation, or an unexpected development when they are trying to make an important decision.

    That is why responsiveness has become such an important part of how I serve clients.

    Being responsive does not mean rushing through every question. It means listening carefully, understanding the situation, providing accurate information, and helping clients understand their options.

    A timely and thoughtful response can make a meaningful difference when someone is already dealing with the uncertainty that can come with buying or refinancing a home.

    Challenges Are Part of the Journey

    Nearly 27 years in mortgage banking have also taught me that unexpected challenges are part of the process.

    When something does not go according to plan, I believe in taking a step back, understanding the situation, and deciding what needs to happen next. Staying calm allows you to focus on solutions rather than becoming overwhelmed by the problem.

    That mindset has helped me throughout my career and continues to shape how I work with clients today.

    Technology Will Continue to Change Mortgage Lending

    Technology and artificial intelligence are changing many industries, including mortgage banking. Automation can make certain parts of the process faster and can give people access to information more efficiently.

    However, technology does not replace the value of human communication and experience.

    A mortgage decision is connected to an individual’s financial situation, goals, and circumstances. Clients may still need someone who can explain information, answer questions, understand the bigger picture, and provide guidance throughout the process.

    I believe technology will continue to evolve, but trust and personal service will remain important parts of mortgage lending.

    Building Relationships Beyond the Transaction

    One of the most rewarding parts of mortgage banking is the opportunity to work with people during important moments in their lives.

    Every client has a different situation. Some may be purchasing their first home, while others may be moving, refinancing, purchasing new construction, or looking for financing that fits a more complex situation.

    After nearly three decades in the industry, I have learned that every client deserves to be treated with respect, honesty, and attention to their individual needs.

    My goal has always been to provide professional service while making the mortgage process easier to understand.

    The Lessons I Carry Forward

    My career has taught me that success is not simply about reaching the next milestone. It is about how you work, how you treat people, and how you respond when circumstances become difficult.

    Hard work, perseverance, clear communication, responsiveness, and integrity have remained important throughout my mortgage career.

    As mortgage technology continues to evolve, I believe these principles will remain just as important as ever.

    If you are considering buying a home, refinancing, purchasing new construction, or exploring mortgage financing options, I am here to help you understand the process and your available options. You can reach me at 201-745-3426 or shaleenmahtani@gmail.com to discuss your mortgage needs. Lending services are available in all 50 states.

  • Mortgage Interest Rates Rise as Housing Market Moves Toward Balance

    Mortgage Interest Rates Rise as Housing Market Moves Toward Balance

    The U.S. housing market is showing signs of balance, but rising mortgage interest rates are creating new challenges for homebuyers. After several years of tight housing conditions, recent data suggests that buyers and sellers are finally moving toward more even footing. At the same time, higher borrowing costs are making financing an important part of every homebuying decision.

    Housing Market Conditions Are Becoming More Balanced

    According to the latest housing market survey, 44% of real estate professionals described their local market as balanced in the second quarter, compared with 30% when the survey began in the third quarter of last year. Sellers also appear to be adjusting their pricing strategies.

    The percentage of agents reporting at least one price cut on active listings declined from 89% to 57%. Contract cancellations also eased, with 40% of real estate professionals reporting at least one deal that fell through in the second quarter, down from 51% in the first quarter.

    Although inventory remains below historical levels, it is no longer the biggest concern for many buyers. Mortgage rates have become a more significant issue, with 37% of agents identifying rates as the top concern for buyers.

    Mortgage Rates Reach Their Highest Level Since May 2025

    Mortgage interest rates moved significantly higher last week. The average 30-year fixed mortgage rate increased from 6.97% to 7.07%, marking a substantial move in a short period and bringing rates to their highest level since May 2025.

    Several factors contributed to the increase. Treasury market activity played an important role because mortgage-backed securities are closely connected to Treasury market movements. A smaller-than-expected Treasury buyback program provided less support for Treasury demand, contributing to upward pressure on rates.

    Inflation concerns also added to the pressure. Wholesale prices increased 0.4% in August, while annual Producer Price Index inflation reached 5.4%. Energy prices increased 4.2%, including a sharp 24.1% rise in diesel prices. At the same time, crude oil prices moved above $100 per barrel.

    These developments pushed the 10-year Treasury yield to its highest level since November 2023, contributing to the rise in mortgage rates.

    Higher Rates Affect Home Sales

    Rising mortgage interest rates are also being reflected in home sales. Existing home sales declined 2% month over month and 1.2% year over year in August. Sales fell to a seasonally adjusted annual rate of 3.98 million, marking the first time they dropped below four million since June 2025.

    However, the broader housing market continues to have some support. Year-to-date home sales remain up 1.6%. Wage growth of 3.1% in August and 643,000 net new jobs added since the beginning of the year may continue to support housing demand despite elevated borrowing costs.

    More Inventory Gives Buyers Room to Negotiate

    One positive development for buyers is the continued growth in housing inventory. Total housing supply reached 1.62 million units, up 3.2% from July. This was the first time inventory exceeded 1.6 million units since November 2019.

    Supply increased to 4.9 months, the highest level in more than a decade. More inventory can give buyers additional choices and greater negotiating power, particularly in markets where sellers are adjusting prices.

    Despite these changes, home prices continue to rise. The median existing home price reached $429,100, representing a 1.6% increase from a year earlier and the 38th consecutive month of annual price gains.

    What This Means for Buyers and Sellers

    The current market highlights the importance of having a clear financing strategy. Buyers should consider how current mortgage interest rates affect their monthly payments and overall budget, while sellers should pay close attention to pricing and buyer affordability.

    The week ahead will bring additional economic data, including Retail Sales, the Federal Reserve meeting, and New Residential Construction. These developments could provide further insight into the direction of mortgage rates and the housing market.

    If you are considering buying or selling a home, understanding current mortgage rates and market conditions can help you make a more informed decision. For guidance on your mortgage options, contact Shaleen Mahtani at 201-745-3426 or shaleenmahtani@gmail.com.

  • Why Home Prices in The Villages Are Falling: What Buyers Should Know

    Why Home Prices in The Villages Are Falling: What Buyers Should Know

    Home prices in The Villages, Florida, have been declining for several years after reaching record levels during the pandemic. The trend is attracting attention because The Villages is one of the largest master-planned 55-and-older communities in the United States.

    For buyers considering a home there, the falling prices and growing inventory may create more opportunities. However, understanding why home prices in The Villages are falling is important before making a real estate decision.

    Home Prices Have Declined Since 2022

    Home prices in The Villages reached a 10-year high in 2022 as demand surged during the COVID-19 pandemic. According to Realtor.com listing data, the median listing price reached approximately $436,850 that year.

    Since then, prices have steadily moved lower. By August 2026, the median listing price had fallen to about $377,784.

    Although this represents a significant decline from the 2022 peak, local real estate professionals describe the change as part of a broader market correction rather than a sign that demand for the community has disappeared.

    The pandemic created unusually strong demand for homes, pushing prices sharply higher. As market conditions normalized, prices began moving back toward more sustainable levels.

    More Homes Are Coming Onto the Market

    One of the biggest reasons behind the decline is the increase in housing inventory.

    In 2022, only about 153 homes were available for sale in The Villages, a 10-year low. Inventory later increased substantially, reaching 651 homes in 2025. By August 2026, around 586 homes were on the market.

    When buyers have more properties to choose from, sellers may need to price their homes more competitively. This increased supply can put downward pressure on home prices, particularly when buyer demand does not grow at the same pace.

    For prospective buyers, however, greater inventory can mean more choices and potentially stronger negotiating opportunities.

    An Aging Population Is Affecting Housing Supply

    The Villages has attracted residents for decades, and many homeowners who purchased properties years ago are now reaching an age when their housing needs are changing.

    Some homeowners may decide to move closer to children, other relatives, or medical services. Others may sell their homes after a spouse passes away, particularly when family members do not plan to keep the property.

    This natural transition is common in 55-and-older communities. However, The Villages has a large population of long-term residents who entered the community around similar periods. As more of these homeowners decide to sell, the number of resale properties can increase.

    New Construction Is Adding More Competition

    Another factor affecting home prices in The Villages is continued new-home construction.

    The community’s developer continues to build and introduce new properties, adding to the supply of homes available to buyers. When new construction increases while demand remains relatively stable, sellers of existing homes may face greater competition.

    However, new construction does not necessarily replace demand for resale homes. Location, upgrades, neighborhood preferences, and proximity to friends or family can all influence a buyer’s decision.

    Some buyers may prefer an existing home in an established part of The Villages, while others may prioritize a newer property that offers modern features and customization options.

    What Falling Prices Mean for Buyers

    For buyers, the current market may offer more flexibility than during the pandemic housing boom. Increased inventory can provide additional choices and more time to compare properties.

    Still, buyers should look beyond the listing price. Mortgage rates, property taxes, insurance, maintenance costs, and the condition and location of the home should all be considered when calculating the total cost of homeownership.

    Ultimately, home prices in The Villages are falling largely because the market is rebalancing after the exceptional price increases of the pandemic years. Growing resale inventory, aging homeowners, and continued new construction have increased supply.

    For buyers and sellers alike, understanding these market conditions can help them make more informed real estate decisions.

    Need Help Financing Your Next Home?

    If you are considering buying a home and want to understand your financing options, working with an experienced mortgage professional can help you evaluate your choices and buying power. Shaleen Mahtani can help you explore mortgage options based on your goals and financial situation. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your home financing options. 

  • The Best Week to Buy a Home in 2026 Could Save Buyers $14K

    The Best Week to Buy a Home in 2026 Could Save Buyers $14K

    If you are planning to buy a home this fall, timing could make a difference. The best week to buy a home in 2026 is expected to be September 27 through October 3. This period could offer buyers a better selection of homes, less competition, and greater negotiating power.

    For financially prepared buyers, this fall window may provide an opportunity to find the right home while avoiding some of the intense competition seen during the spring and summer months.

    Why September 27 to October 3 May Be the Best Week to Buy

    The 2026 housing market is expected to offer nearly 32% more active listings during this week compared with the beginning of the year. More inventory means buyers may have more homes to compare instead of feeling pressured to make a quick decision.

    Prices may also work more in favor of buyers. A median-priced home of about $416,000 could potentially cost around $14,000 less than during the summer market peak. This does not mean every home will be discounted by that amount, but the overall market conditions could create more opportunities for buyers to negotiate.

    More Time to Compare and Negotiate

    Another advantage of the best week to buy is a slower market pace. Buyers may have about 13 additional days compared with the fastest pace of the year, giving them more time to evaluate properties and consider their options.

    Buyer interest can also be lower during this period. Property views per listing are roughly 30% lower than the summer peak and about 14% below an average week. With fewer competing buyers watching the same properties, you may have more room to make a thoughtful offer.

    Look for Homes That Have Been on the Market

    Buyers should not focus only on newly listed homes. Properties that have been available for two weeks or longer may deserve a closer look.

    Some sellers may become more flexible after a home has been on the market for an extended period. Price reductions can also create potential opportunities. During the highlighted buying period, about 5.7% of listings have historically offered discounts.

    This does not mean every seller will accept a lower offer. However, buyers may have more negotiating power when a property has been sitting on the market or has already had multiple price reductions.

    Prepare Before the Best Week to Buy

    Waiting until September 27 to start preparing could mean missing an opportunity. Buyers should consider getting mortgage pre-approved, reviewing their budget, and identifying the neighborhoods and home features that matter most.

    It is also important to remember that the national best week to buy a home does not apply equally to every market. Buying conditions can vary between cities, with some areas reaching their strongest buyer opportunities earlier or later in the fall.

    Ultimately, the right time to buy depends on your finances, goals, and local housing market. A favorable week can create opportunities, but buying a home should still fit comfortably within your budget.

    Ready to Prepare for Your Home Purchase?

    If you are planning to buy a home this fall, getting your financing ready early can help you move confidently when the right property comes along. Contact Shaleen Mahtani at 201-745-3426 or shaleenmahtani@gmail.com to discuss your mortgage options and take the next step toward homeownership.

  • How Mortgage Debt Consolidation Can Help You Manage Debt

    How Mortgage Debt Consolidation Can Help You Manage Debt

    Managing multiple debts can make your monthly finances feel complicated. Credit cards, personal loans, and other high-interest balances can quickly add up, making it harder to stay on track with your financial goals. For homeowners, mortgage debt consolidation may be one option to consider when looking for a simpler way to manage debt.

    Mortgage debt consolidation involves using the equity in your home or a mortgage-related financing option to pay off other debts. Instead of making several payments to different lenders, you may be able to combine some debts into one monthly payment. However, it is important to understand how the process works, along with its potential benefits and risks, before making a decision.

    What Is Mortgage Debt Consolidation?

    Mortgage debt consolidation is a strategy that allows homeowners to use mortgage financing or home equity to consolidate certain existing debts. Depending on your financial situation and the loan program available, this may involve refinancing your current mortgage or using a home equity loan or line of credit.

    The goal is generally to simplify debt payments and potentially reduce the interest rate on higher-interest debt. Since mortgage rates can be lower than credit card rates, consolidating certain debts may reduce the amount of interest you pay. However, the total cost depends on the loan terms, fees, interest rate, and repayment period.

    How Does Mortgage Debt Consolidation Work?

    The process typically starts with reviewing your current mortgage, home value, outstanding debts, income, credit profile, and available home equity. A mortgage professional can then help determine which financing options may fit your circumstances.

    If you qualify for a suitable option, funds from the new financing may be used to pay off eligible debts. You would then make payments according to the terms of the new loan.

    For example, if you have several credit card balances with relatively high interest rates, consolidating them through an appropriate mortgage or home equity strategy could replace multiple payments with a single payment. This can make your monthly finances easier to organize.

    Potential Benefits of Consolidating Debt

    One major benefit of mortgage debt consolidation is simplicity. Managing one payment instead of several can make budgeting easier and reduce the chance of missing a payment.

    Another potential benefit is a lower interest rate compared with some unsecured debts, particularly credit cards. A lower rate may help reduce interest costs over time. Depending on the financing structure, consolidation could also provide a more predictable repayment schedule.

    However, homeowners should look beyond the monthly payment. Extending repayment over a longer period can increase the total interest paid, even if the monthly payment is lower.

    Risks to Consider Before Consolidating

    While mortgage debt consolidation can offer advantages, it is not right for everyone. When you use your home as collateral for financing, failing to make payments can put your home at risk.

    You should also consider closing costs, loan fees, interest rates, and the total repayment amount. Consolidating debt does not eliminate the debt itself. It simply changes how the debt is financed.

    It is also important to avoid building new high-interest debt after consolidation. Otherwise, you could end up with both the new mortgage-related debt and additional credit card balances.

    Is Mortgage Debt Consolidation Right for You?

    The right strategy depends on your income, credit, existing mortgage, home equity, debt balances, interest rates, and long-term financial goals. Comparing the costs and benefits before moving forward can help you make a more informed decision.

    If you are considering mortgage debt consolidation, speaking with a qualified mortgage professional can help you understand your available options and determine whether consolidation makes financial sense for your situation.

    Ready to Explore Your Mortgage Options?

    If managing multiple debts has become challenging, exploring your mortgage and home equity options may help you create a more manageable financial plan. Shaleen Mahtani can help you review potential mortgage solutions based on your financial goals and circumstances.

    Whether you are considering debt consolidation, refinancing, or another mortgage solution, getting professional guidance can help you understand your choices before making a major financial decision. Contact Shaleen Mahtani at 201-745-3426 or shaleenmahtani@gmail.com to discuss your mortgage options. 

  • How to Calculate Mortgage Affordability Before Buying a Home

    How to Calculate Mortgage Affordability Before Buying a Home

    Buying a home is an exciting milestone, but knowing how much you can comfortably afford is one of the most important steps before starting your search. Mortgage affordability is not simply about how much a lender is willing to approve. It is about finding a monthly payment that fits comfortably within your income, expenses, savings, and long-term financial goals.

    Understanding your mortgage affordability can help you set a realistic homebuying budget and avoid taking on more debt than you can comfortably manage.

    What Is Mortgage Affordability?

    Mortgage affordability refers to the amount of home you can reasonably afford based on your income, existing debts, down payment, credit profile, interest rate, and other financial factors.

    A lender may evaluate your financial situation to determine how much you qualify to borrow. However, your personal budget may suggest a lower amount. For example, a mortgage payment that a lender considers manageable may leave you with less money for savings, emergencies, insurance, utilities, or other household expenses.

    That is why it is important to consider both loan qualification and personal affordability before deciding on a home price.

    Start With Your Monthly Income

    The first step in calculating mortgage affordability is determining your reliable monthly income. Include your regular employment income and other consistent sources of income that may be considered when applying for a mortgage.

    Next, review your monthly expenses. These can include:

    • Car payments and student loans
    • Credit card payments
    • Utilities and groceries
    • Insurance premiums
    • Childcare or education expenses
    • Existing housing costs
    • Regular savings contributions

    Knowing where your money goes each month gives you a clearer picture of how much you can reasonably allocate toward housing.

    Consider Your Debt-to-Income Ratio

    Your debt-to-income ratio (DTI) is an important factor lenders use when evaluating mortgage applications. It compares your monthly debt obligations with your gross monthly income.

    For example, if you earn $8,000 per month before taxes and have $2,400 in monthly debt payments, your DTI is 30%.

    A lower DTI generally indicates that you have more room in your budget for a mortgage payment. However, lenders have different requirements, and other factors such as credit history and loan type can also affect approval.

    Estimate Your Total Monthly Housing Cost

    When calculating mortgage affordability, don’t focus only on the principal and interest payment. Your total monthly housing cost may also include:

    • Property taxes
    • Homeowners insurance
    • Private mortgage insurance (PMI), if applicable
    • Homeowners association (HOA) fees
    • Maintenance and repair costs

    A home that appears affordable based on the mortgage payment alone may cost considerably more once these additional expenses are included.

    Factor in Your Down Payment and Interest Rate

    Your down payment can significantly affect how much you need to borrow. A larger down payment may reduce your loan amount and monthly payment, although you should avoid using all of your savings just to increase your down payment.

    Your mortgage interest rate also plays an important role. Even a small difference in the rate can change your monthly payment and the total interest paid over the life of the loan.

    Getting a mortgage pre-approval can give you a better understanding of the loan amount and terms you may qualify for before you begin making offers.

    Build a Comfortable Homebuying Budget

    Once you understand your income, debts, down payment, and estimated housing expenses, you can create a realistic homebuying budget. Consider leaving room for emergency savings, future expenses, home repairs, and changes in your financial situation.

    The goal of mortgage affordability should not simply be to determine the maximum amount you can borrow. It should help you identify a home price that allows you to enjoy homeownership while maintaining financial flexibility.

    Make Your Mortgage Affordability Work for You

    Calculating mortgage affordability before buying a home can help you make a more confident and informed decision. By reviewing your income, debts, down payment, interest rate, and total housing expenses, you can establish a budget that fits your financial goals.

    If you’re planning to buy a home and want help evaluating your mortgage options, Shaleen Mahtani can help you understand your financing choices and find an approach that fits your goals. Contact Shaleen at 201-745-3426 or shaleenmahtani@gmail.com to discuss your mortgage needs. 

  • Mortgage Points: What They Are, How They Work, and If They’re Worth It

    Mortgage Points: What They Are, How They Work, and If They’re Worth It

    When you’re getting a mortgage, even a small change in your interest rate can affect your monthly payment and the total amount you pay over the life of the loan. One option borrowers may consider is mortgage points, which can help lower the interest rate on a home loan in exchange for an upfront payment.

    But are mortgage points worth the cost? The answer depends on your loan amount, how long you plan to stay in the home, and how much you can afford to pay upfront.

    What Are Mortgage Points?

    Mortgage points, also called discount points, are fees paid directly to the lender at closing in exchange for a lower mortgage interest rate. Generally, one point costs 1% of the total mortgage amount.

    For example, if you take out a $400,000 mortgage, one point would typically cost $4,000. In return, the lender may reduce your interest rate by a certain amount. The exact reduction varies by lender, loan type, market conditions, and other factors.

    It’s important to remember that paying one point does not automatically mean your interest rate will decrease by a specific percentage. Always ask your lender how much the points will reduce your rate before making a decision.

    How Do Mortgage Points Work?

    The basic idea behind mortgage points is simple: pay more upfront to potentially save money on interest over time.

    Suppose you have a $400,000 mortgage and your lender offers you a lower interest rate if you pay $4,000 in discount points. Your monthly principal and interest payment could decrease because of the lower rate.

    The savings continue each month you make your mortgage payments. However, you need to consider the upfront cost and how long it will take for your monthly savings to recover that cost.

    This is known as the break-even point.

    How to Calculate the Break-Even Point

    The break-even point helps determine how long you need to keep the mortgage before your savings exceed the amount you paid for points.

    For example, if you pay $4,000 in mortgage points and save $100 per month on your payment, your break-even period would be:

    $4,000 ÷ $100 = 40 months

    That means you would generally need to keep the mortgage for about 40 months to recover the upfront cost through monthly savings.

    If you expect to sell or refinance before reaching your break-even point, paying for points may not make financial sense.

    Are Mortgage Points Worth It?

    Mortgage points can be worthwhile for borrowers who plan to stay in their home for many years and want to reduce their monthly mortgage payment and long-term interest costs.

    They may be less attractive if you have limited cash available for closing or expect to move or refinance within a relatively short period.

    Before buying points, compare the upfront cost with the expected monthly savings. You should also consider other ways to use your cash, such as increasing your down payment, maintaining emergency savings, or covering other homeownership expenses.

    What to Consider Before Buying Mortgage Points

    Before deciding, ask your lender for a detailed comparison of your loan with and without points. Consider:

    • The total cost of the points
    • Your new interest rate
    • Your estimated monthly savings
    • Your expected time in the home
    • Your break-even period
    • Your available cash for closing

    A mortgage professional can help you evaluate these numbers based on your specific loan rather than relying on a general estimate.

    Make the Right Choice With Mortgage Points

    Mortgage points can help lower your interest rate and potentially reduce your long-term interest costs, but they require an upfront payment. Understanding the cost of mortgage points, your potential monthly savings, and your break-even point can help you decide whether paying points makes sense for your financial goals.

    If you’re considering buying mortgage points and want to understand how they could affect your loan, Shaleen Mahtani can help you compare your mortgage options based on your goals and financial situation. You can reach out at 201-745-3426 or shaleenmahtani@gmail.com to discuss your home financing needs. 

  • First-Time Homebuyers Are Driving Recent Housing Market Momentum

    First-Time Homebuyers Are Driving Recent Housing Market Momentum

    The housing market is showing renewed activity, and first-time homebuyers are playing an important role in this recent momentum. After facing high home prices and elevated mortgage rates, many entry-level buyers are finding new opportunities as housing affordability improves in some areas.

    Recent housing data shows that lower-priced homes are experiencing stronger gains in both listings and sales activity. This trend is particularly important for first-time buyers, who often begin their homeownership journey in the entry-level segment of the market.

    First-Time Homebuyers Are Becoming More Active

    The entry-level housing market is seeing increased activity as more buyers look for affordable opportunities. Recent data shows that existing home sales increased 5.9% year over year, while newly pending sales rose 7.6%. Lower-priced homes recorded some of the strongest improvements in both new listings and sales activity.

    This could be encouraging news for first-time homebuyers who previously delayed their plans because of affordability concerns. Instead of waiting for major changes in home prices or mortgage rates, some buyers may be choosing to explore the options currently available to them.

    For buyers who have been sitting on the sidelines, understanding their purchasing power and available mortgage options can be an important first step.

    Lower Monthly Payments May Improve Affordability

    Mortgage affordability remains one of the biggest concerns for prospective homebuyers. However, recent changes in typical monthly payments may be creating more opportunities for some buyers.

    The source data reports that the typical monthly mortgage payment fell to $1,884, down 2.5% from a year earlier.

    For first-time buyers working with a specific monthly budget, even a modest reduction in housing costs can make a difference. A lower payment may help some buyers feel more comfortable exploring homeownership.

    However, buyers should look beyond the mortgage payment itself. Property taxes, homeowners insurance, maintenance, closing costs, and the down payment can all affect the overall cost of buying a home.

    Home Prices Are Still Rising, But at a Slower Pace

    Home prices remain an important consideration for first-time buyers. According to the source data, the median home value reached $372,057, representing a 1.1% increase compared with the previous year.

    Slower price growth at the entry level may give some buyers more time to evaluate properties and financing options. When prices are not increasing rapidly, buyers may have more opportunity to compare homes and make decisions based on their financial goals.

    Still, affordability varies from one market to another. A home that fits a buyer’s budget in one area may be significantly more expensive in another. This makes it important for first-time buyers to understand local housing conditions before making an offer.

    Housing Inventory Remains an Important Factor

    Although the market is becoming more balanced, inventory growth has slowed. Housing stock increased just 0.9% year over year, while 25.8% of listings had price reductions. At the same time, 30.3% of May home sales closed above the asking price.

    These numbers suggest that first-time homebuyers may have more opportunities than they did during periods of rapidly rising prices, but competition still exists.

    Buyers should be prepared when they find a property that meets their needs and budget. Getting pre-approved for a mortgage can help buyers understand their potential purchasing power and demonstrate that they are prepared to move forward.

    What This Means for First-Time Homebuyers

    The recent housing market momentum is an important reminder that changing market conditions can create opportunities for buyers who previously believed homeownership was out of reach.

    Lower monthly payments, slower price growth at the entry level, and increased sales activity could encourage more first-time homebuyers to enter the market. However, the right time to buy depends on each person’s financial situation, including income, savings, credit profile, down payment, and long-term goals.

    First-time buyers should also avoid making a purchase based solely on market predictions. Instead, focus on what fits your current financial situation and whether the monthly payment is comfortable for your budget.

    Start Planning Your First Home Purchase

    If you are considering buying your first home, understanding your mortgage options can help you approach the process with greater confidence. Reviewing your finances, determining your purchasing power, and exploring available loan programs can help you build a realistic homebuying plan.

    If you have questions about mortgage financing or want to discuss your homebuying options, contact Shaleen Mahtani at 201-745-3426 or email shaleenmahtani@gmail.com. Taking the time to understand your financing options today can help you make a more informed decision when the right home comes along.

  • Should You Pay Cash or Get a Mortgage When Buying a Home? 

    Should You Pay Cash or Get a Mortgage When Buying a Home? 

    When purchasing real estate, one of the biggest financial questions buyers face is whether to pay cash or get a mortgage. Paying cash can help you avoid mortgage interest and monthly payments, while financing allows you to keep more of your money available for investments, emergencies, or other financial goals. Understanding the advantages and drawbacks of both options can help you make a decision that fits your financial situation.

    What Does It Mean to Pay Cash for Real Estate?

    Paying cash means purchasing a property without borrowing money through a mortgage. Instead, you use your available savings or other liquid assets to cover the entire purchase price.

    One major advantage is that you don’t have to make monthly mortgage payments or pay interest over the life of a loan. A cash purchase can also make your offer more attractive to sellers because there is no mortgage approval contingency, potentially making the transaction simpler and faster.

    However, paying cash requires a substantial amount of available capital. Putting most of your savings into a property could leave you with less money for emergencies, investments, maintenance, or other financial needs.

    What Are the Benefits of Getting a Mortgage?

    Choosing a mortgage allows you to purchase real estate while keeping some of your cash available. Rather than using all your savings for the property, you make a down payment and finance the remaining balance.

    This approach can provide greater financial flexibility. The cash you retain could be used for an emergency fund, investments, business expenses, renovations, or other priorities. Depending on your financial circumstances, maintaining liquidity may be more valuable than eliminating mortgage debt.

    A mortgage can also allow you to take advantage of leverage. If the property increases in value, you may benefit from appreciation while having invested only a portion of the purchase price upfront. However, real estate values can decline, and investment returns are never guaranteed.

    Pay Cash or Get a Mortgage: What Should You Consider?

    The decision to pay cash or get a mortgage depends on more than simply having enough money to buy a property outright. Consider your mortgage interest rate, income stability, emergency savings, investment opportunities, risk tolerance, and long-term financial goals.

    For example, if paying cash would significantly reduce your savings, taking a mortgage may provide a stronger financial cushion. On the other hand, if you have substantial assets and prefer to avoid debt and mortgage interest, paying cash could be appealing.

    You should also consider the opportunity cost of using your money. Cash invested in a property is less liquid than cash kept in savings or other investments.

    Is Paying Cash Always Better Than a Mortgage?

    Not necessarily. A cash purchase eliminates mortgage interest, but it doesn’t automatically mean it is the most financially beneficial option for every buyer. Your money may have other potential uses, and keeping sufficient liquid assets can be important for financial security.

    Similarly, taking a mortgage isn’t always the better choice. Interest costs, closing expenses, and monthly payments can increase the overall cost of owning the property.

    The best decision depends on your personal circumstances and how each option fits into your broader financial plan.

    Make the Right Choice for Your Real Estate Goals

    When deciding whether to pay cash or get a mortgage, look at the complete financial picture rather than focusing on one factor. Compare the cost of borrowing with the benefits of keeping your money available, and consider how the decision could affect your long-term goals.

    If you’re unsure which approach makes sense, speaking with a mortgage professional can help you understand your financing options. Shaleen Mahtani can help you evaluate mortgage solutions based on your homeownership and financial goals. To discuss your options, call 201-745-3426 or email shaleenmahtani@gmail.com.

  • Waiving Financing Contingency: What Homebuyers Should Know

    Waiving Financing Contingency: What Homebuyers Should Know

    When buying a home, a financing contingency can provide important protection if you need a mortgage to complete the purchase. It allows buyers to secure financing and, depending on the contract terms, potentially exit the deal without losing their earnest money if they cannot obtain a loan. However, some buyers may consider waiving financing contingency to make their offer more attractive in a competitive housing market.

    Before making this decision, it is important to understand what a financing contingency does, what risks come with waiving it, and when it may or may not make sense.

    What Is a Financing Contingency?

    A financing contingency is a provision in a home purchase agreement that makes the purchase dependent on the buyer obtaining mortgage financing under specified conditions. It can protect buyers if their mortgage application is denied or financing cannot be secured within the agreed timeframe.

    For example, if you make an offer with a financing contingency and your lender ultimately cannot approve the loan, the contingency may allow you to cancel the contract according to its terms. Without this protection, you could face financial consequences if you cannot obtain the necessary financing.

    Why Would a Buyer Waive Financing Contingency?

    In a competitive market, sellers often compare multiple offers. A buyer who agrees to waive financing contingency may appear more attractive because the seller has greater confidence that the transaction will move forward.

    Waiving the contingency can potentially strengthen an offer, especially when several buyers are competing for the same property. However, it also shifts more risk to the buyer. Even if you have been pre-approved, final mortgage approval is not always guaranteed.

    Changes in your financial situation, property-related issues, appraisal results, or lender underwriting requirements could affect your ability to close.

    What Are the Risks of Waiving Financing Contingency?

    The biggest concern with waiving financing contingency is that you may still be obligated to purchase the property even if your mortgage does not come through.

    If you cannot secure financing after waiving the contingency, you could potentially lose your earnest money deposit or face other contractual consequences. The exact risks depend on the purchase agreement and applicable state laws.

    Another consideration is that pre-approval is not the same as final loan approval. Your lender may still need to verify income, assets, credit, employment, and property details before issuing final approval.

    Should You Waive Financing Contingency?

    There is no one-size-fits-all answer. Buyers with strong finances, substantial cash reserves, reliable income, and a high level of confidence in their financing may have more flexibility. However, buyers who are relying heavily on mortgage approval may benefit from keeping the contingency.

    Before waiving financing contingency, discuss the decision with your real estate agent, mortgage professional, and attorney. They can help you understand the contract, evaluate your financial position, and determine whether the additional risk is appropriate for your situation.

    Ready to Make a Confident Home Financing Decision?

    If you’re considering waiving a financing contingency or want to understand which mortgage option may best fit your financial goals, Shaleen Mahtani is here to help. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your financing options and prepare for your home purchase. Lending services are available in all 50 states.

  • How Rising Median Home Prices Affect Homebuyers

    How Rising Median Home Prices Affect Homebuyers

    Buying a home has become a major financial decision for many Americans, especially as housing costs continue to change. Understanding the median home price can help buyers set realistic expectations, estimate their purchasing power, and prepare for the costs associated with homeownership. When median prices rise, buyers may need to adjust their budgets and consider how higher prices could affect their mortgage payments.

    Why Home Prices Matter When You’re Buying

    The price of a home affects much more than the amount you pay at closing. It can influence your down payment, loan amount, monthly mortgage payment, property taxes, homeowners’ insurance, and overall housing expenses.

    For example, if you planned to purchase a $400,000 home with a 10% down payment, you would need $40,000 upfront, excluding closing costs. If the same type of home costs $450,000, a 10% down payment would increase to $45,000. A higher purchase price can also mean borrowing more money, potentially increasing your monthly payment.

    This is why keeping an eye on housing prices is important when planning your home purchase.

    Rising Prices Can Change Your Buying Power

    When home prices increase faster than your income, the amount of home you can comfortably afford may decrease. You might qualify for a larger mortgage based on your financial profile, but that does not necessarily mean a higher payment is the right choice for your budget.

    Buyers should consider their monthly expenses, existing debts, savings, and future financial goals before deciding how much to spend. A mortgage payment that looks manageable today should also leave room for other homeownership costs and unexpected expenses.

    Getting mortgage pre-approval can be useful because it gives you a clearer idea of how much you may be able to borrow before you start seriously shopping for a property.

    A Larger Down Payment May Require More Savings

    One of the most noticeable effects of rising home prices is the potential increase in the amount needed for a down payment.

    Although some mortgage programs allow qualified buyers to purchase a home with a relatively small down payment, putting more money down can reduce the amount you need to borrow. However, saving a larger amount may take additional time, particularly in higher-priced markets.

    Buyers should also remember that the down payment is not the only upfront expense. Closing costs, moving expenses, inspections, and other costs can add to the cash needed to complete a purchase.

    Location Can Make a Big Difference

    The national median home price does not tell the complete story. Real estate prices vary significantly from one city, state, and neighborhood to another.

    Some markets may have relatively affordable homes, while others can have prices far above the national median. Local factors such as housing supply, employment opportunities, population growth, interest rates, and buyer demand can all influence prices.

    For this reason, buyers should focus not only on national housing trends but also on the market where they intend to purchase.

    Should You Wait for Home Prices to Fall?

    It can be tempting to postpone buying while waiting for prices to decline. However, predicting exactly when home prices will fall and by how much is difficult.

    Waiting could potentially give you more time to save for a down payment or improve your credit profile. On the other hand, home prices, mortgage rates, or local market conditions could change while you wait.

    Instead of trying to perfectly time the market, consider whether purchasing a home fits your current financial situation, lifestyle, and long-term goals.

    How Buyers Can Prepare for Higher Prices

    If rising home prices are affecting your plans, there are several steps you can take. Start by reviewing your budget and determining how much you can comfortably spend each month. Improving your credit, reducing existing debt, building savings, and comparing mortgage options can also strengthen your overall financial position.

    It may also help to consider different neighborhoods, property types, or home sizes that fit your budget. Being flexible can open up more opportunities without requiring you to take on an uncomfortable monthly payment.

    Make Your Homebuying Plan Work for You

    Rising home prices can make purchasing a property more challenging, but they don’t necessarily mean homeownership is out of reach. Understanding the median home price, reviewing your finances, and exploring appropriate mortgage options can help you make a more informed decision.

    If you’re considering buying a home and want to understand your financing options, Shaleen Mahtani can help you evaluate your mortgage choices based on your goals and financial situation. You can reach out at 201-745-3426 or shaleenmahtani@gmail.com to discuss your home financing needs.

  • How Community Lending Can Turn Mortgage-Ready Renters Into Homeowners

    How Community Lending Can Turn Mortgage-Ready Renters Into Homeowners

    Homeownership remains a significant financial goal for many Americans, but an increasing number of younger households are struggling to make the transition from renting to owning. According to the source material, the U.S. homeownership rate reached 65.6% in 2024, yet younger generations, particularly Gen Z and Millennials, continue to fall behind older generations.

    For mortgage lenders, this gap represents an opportunity. Many renters may already have the financial foundation needed to qualify for a mortgage but simply have not taken the next step. Community lending can help connect these potential buyers with the education, resources, and guidance they need.

    Understanding the Mortgage-Ready Renter

    Not every renter is far away from homeownership. The source estimates 7.9 million “mortgage-ready” families nationwide. These households may have the credit profile, income, and debt-to-income ratio needed to qualify for a mortgage under current standards but have not yet purchased a home.

    The first step for lenders is to understand who these potential buyers are in their local markets. Reviewing Home Mortgage Disclosure Act (HMDA) data, connecting with local nonprofits, and looking at areas with low mortgage application activity can help identify communities with ready but hesitant buyers.

    Use Education to Build Buyer Confidence

    One of the biggest barriers to homeownership can be a lack of knowledge. Renters may believe they need a 20% down payment, perfect credit, or a higher income to qualify for a mortgage.

    Effective community lending education can address these misconceptions. Instead of focusing only on how to apply for a mortgage, lenders can explain the financial and emotional benefits of owning versus renting, discuss common mortgage myths, and introduce potential buyers to available resources.

    Starting these conversations before someone submits a loan application can make the homebuying process feel more approachable and help renters become more confident about their options.

    Build Strong Community Partnerships

    Lenders do not have to reach potential homeowners alone. Partnerships with housing counselors, employers, schools, nonprofits, and faith-based organizations can extend the reach of community lending efforts.

    For example, housing counselors can help renters prepare their credit, save for a down payment, and understand the homebuying process. Employers can provide mortgage education in the workplace, while community organizations can host educational workshops for residents.

    These partnerships create trusted channels for reaching people who may not otherwise seek information directly from a lender.

    Address the Barriers to Homeownership

    Successful community lending strategies should address more than just loan qualification. The source identifies four major obstacles: knowledge, trust, market availability, and resources.

    Addressing these barriers requires collaboration among lenders, nonprofits, government agencies, real estate professionals, and other community partners. Programs modeled on collaborative initiatives such as CONVERGENCE demonstrate how different organizations can work together to close homeownership gaps.

    Helping More Renters Take the Next Step

    Millions of potential buyers may be closer to homeownership than they realize. By identifying mortgage-ready renters, providing clear education, and building meaningful community partnerships, lenders can help turn hesitation into action.

    If you are considering buying a home and want to better understand your mortgage options, professional guidance can help you take the next step with greater confidence.

    Are You Ready to Move From Renting to Homeownership? 

    If you are renting but believe you may be ready to buy, you do not have to navigate the process alone. Shaleen Mahtani can help you understand your mortgage options, assess your homebuying readiness, and identify financing solutions that fit your goals.

    Call 201-745-3426 or email shaleenmahtani@gmail.com to start the conversation. Lending services are available in all 50 states.

  • Waiving Appraisal Contingency: What Homebuyers Should Know

    Waiving Appraisal Contingency: What Homebuyers Should Know

    Buying a home often involves several contingencies designed to protect the buyer during the transaction. One of the most important is the appraisal contingency. However, in a competitive housing market, some buyers may consider waiving appraisal contingency to make their offer more attractive to sellers.

    While this strategy can strengthen an offer, it also comes with financial risks. Understanding how an appraisal contingency works and what happens when you waive it can help you make a more informed decision.

    What Is an Appraisal Contingency?

    An appraisal contingency is a provision in a purchase agreement that allows a buyer to respond if the home’s appraised value is lower than the agreed purchase price. Because mortgage lenders typically base the loan amount on the property’s appraised value, a low appraisal can create a financing gap.

    For example, suppose you agree to purchase a home for $500,000, but the appraisal comes in at $475,000. Depending on the loan program and your financing, the lender may not provide a mortgage based on the full $500,000 purchase price.

    With an appraisal contingency, the buyer may have options such as renegotiating the price, requesting another appraisal, bringing additional funds to closing, or potentially canceling the contract according to its terms.

    Why Would a Buyer Waive an Appraisal Contingency?

    In a competitive market, sellers may receive multiple offers. A buyer who is waiving appraisal contingency can make their offer appear more certain because the seller has less concern about a low appraisal disrupting the transaction.

    This approach may be especially appealing when several buyers are competing for the same property. However, making an offer more attractive to the seller does not eliminate the financial risk for the buyer.

    What Are the Risks of Waiving Appraisal Contingency?

    The biggest risk is having to cover the difference between the purchase price and the appraised value.

    Consider a $500,000 purchase that receives a $475,000 appraisal. If your lender limits the mortgage based on the lower value, you could potentially need to provide an additional $25,000, depending on your financing and contract terms.

    Another concern is that you may have fewer options if the appraisal is significantly below the purchase price. Your ability to renegotiate or walk away without financial consequences may be limited once the contingency has been waived.

    When Might Waiving Appraisal Contingency Make Sense?

    There is no universal answer. The decision depends on your financial position, the property, local market conditions, and how much flexibility you have after closing.

    A buyer with substantial cash reserves may be better positioned to handle an appraisal gap. However, using a large portion of your savings to cover the difference could leave less money available for closing costs, moving expenses, repairs, or unexpected homeownership costs.

    Before waiving appraisal contingency, buyers should understand exactly what the contract requires and discuss the potential consequences with their real estate and mortgage professionals.

    Make an Informed Homebuying Decision

    Waiving an appraisal contingency can help make a purchase offer more competitive, but it should not be treated as a simple way to win a bidding war. The potential financial exposure can be significant if the home’s appraised value falls below the purchase price.

    Understanding your financing, available cash, and overall homebuying budget can help you determine whether this strategy fits your circumstances.

    Ready to Make a Confident Homebuying Decision?

    Considering waiving an appraisal contingency to strengthen your offer? Shaleen Mahtani can help you understand your financing options and evaluate the potential impact of an appraisal gap before you make a decision. Contact Shaleen at 201-745-3426 or shaleenmahtani@gmail.com to discuss your mortgage needs and take the next step toward homeownership.

  • How a Low Down Payment Mortgage Can Help You Buy a Home

    How a Low Down Payment Mortgage Can Help You Buy a Home

    Homeownership remains an important goal for many Americans. Owning a home can provide stability, opportunity and a foundation for building long-term wealth. However, saving enough money for a traditional 20% down payment can be one of the biggest obstacles for prospective buyers. A low down payment mortgage can help qualified borrowers overcome that barrier and purchase a home sooner.

    Why Saving 20% Can Be Difficult

    The cost of buying a home has changed significantly over the years. According to the source article, the median U.S. home price was about 2.5 times the median annual household income in the 1950s. By the 1980s, that figure had increased to 3.1 times household income. Today, the median home price is nearly five times the median household income.

    As home prices have increased faster than incomes, saving a 20% down payment can take many years. U.S. Mortgage Insurers reported that a household earning an average annual income of $80,610 could need approximately 26 years to save a 20% down payment, plus closing costs, for a median-priced single-family home valued at $412,500.

    How a Low Down Payment Mortgage Helps

    A low down payment mortgage allows qualified buyers to purchase a home without first saving 20% of the purchase price. Private mortgage insurance (PMI) can make these lower-down-payment options possible by helping reduce the risk to lenders.

    For buyers who can comfortably afford the monthly mortgage payment but have not accumulated a large down payment, this can provide an opportunity to enter the housing market sooner. Instead of waiting decades to reach a 20% down payment, a buyer may be able to purchase a home with a smaller amount saved.

    The Cost of Waiting to Buy

    Waiting to save a larger down payment may seem like the safer choice, but delaying a home purchase can also have financial consequences. Home prices may continue to rise, potentially increasing the amount needed for a future down payment. Buyers who continue renting also spend years making payments without building home equity.

    The source article highlights another potential impact of delaying homeownership. An economic analysis of Panel Study of Income Dynamics data found that purchasing a home by age 30 was associated with a 22.5% higher net worth at age 50—approximately $119,000 more—compared with purchasing a home in one’s 40s.

    A Path Toward Building Wealth

    Homeownership can be an important part of long-term financial growth. Over time, homeowners can build equity as they make mortgage payments and benefit from changes in home value. Earlier homeownership may also provide more time to build that equity.

    For mortgage-ready buyers who can afford a home but are waiting solely to save a 20% down payment, a low down payment mortgage may offer another path forward. PMI can help make this option available to qualified borrowers.

    Is a Low Down Payment Mortgage Right for You?

    A low down payment mortgage is not the right choice for everyone. Buyers should consider their income, monthly expenses, savings, credit profile and overall financial situation before deciding to purchase a home.

    For those who are financially prepared but lack a 20% down payment, however, a low down payment mortgage can help turn homeownership from a distant goal into a more achievable opportunity. By allowing qualified buyers to purchase sooner, these mortgage options can help more families access the stability and long-term wealth-building potential of owning a home.

    Ready to Take the Next Step Toward Homeownership? 

    If you’re considering a low down payment mortgage or want to learn which home financing option may fit your goals, Shaleen Mahtani is here to help. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your homeownership goals and explore your options. Lending services are available in all 50 states.

  • 15-Year Fixed vs. 30-Year Fixed Mortgage: Which Is Right for You?

    15-Year Fixed vs. 30-Year Fixed Mortgage: Which Is Right for You?

    When choosing a mortgage, one of the most important decisions is selecting the right loan term. Two of the most common options are a 15-year fixed-rate mortgage and a 30-year fixed-rate mortgage. Both provide predictable monthly payments and a fixed interest rate, but they differ significantly in payment amount, total interest, and how quickly you build home equity.

    Understanding these differences can help you choose a mortgage term that fits your financial goals and long-term plans.

    What Is a 15-Year Fixed Mortgage?

    A 15-year fixed mortgage allows you to repay your home loan over 15 years while keeping the interest rate fixed throughout the loan term. Because you are paying off the loan in half the time compared with a 30-year mortgage, your monthly principal and interest payments are generally higher.

    However, you typically pay substantially less interest over the life of the loan. You also build equity faster because a larger portion of each payment goes toward reducing the principal balance.

    A 15-year mortgage may be advisable for borrowers who have a stable income, can comfortably manage the higher monthly payment, and want to become mortgage-free sooner.

    What Is a 30-Year Fixed Mortgage?

    A 30-year fixed mortgage spreads repayment over three decades. The longer repayment period generally results in lower monthly principal and interest payments, making this option more affordable for many homebuyers.

    The trade-off is that you may pay more total interest over the life of the loan. You also build equity more slowly during the early years compared with a 15-year mortgage.

    A 30-year fixed mortgage may be advisable if keeping monthly payments manageable is a priority, especially for first-time buyers, families with other financial commitments, or borrowers who want greater flexibility in their monthly budget.

    15-Year Fixed vs. 30-Year Fixed Mortgage: Which Should You Choose?

    The right choice depends on your income, savings, financial goals, and comfort with monthly payments. A 15-year mortgage can help you pay off your home faster and reduce lifetime interest costs, but the higher payment can put more pressure on your budget.

    A 30-year mortgage offers lower monthly payments and can leave more room in your budget for emergency savings, investments, home improvements, or other expenses. Some borrowers may also choose a 30-year mortgage while making additional principal payments when their finances allow.

    Before deciding, consider not only the monthly payment but also your overall financial picture and how long you expect to stay in the home.

    Get Guidance Before Choosing Your Mortgage Term

    Choosing between a 15-year and 30-year fixed mortgage is an important financial decision. The best option depends on your individual circumstances, not simply on which loan has the lower interest cost.

    Planning to buy a home or considering your mortgage options? Shaleen Mahtani can help you understand available loan options, compare payment structures, and choose a strategy that aligns with your financial goals. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your mortgage needs and take the next step with confidence.
  • The True Cost of Homeownership: Expenses Beyond the Down Payment

    The True Cost of Homeownership: Expenses Beyond the Down Payment

    Buying a home is an exciting milestone, but the Cost of Homeownership does not end when you make your down payment. As a new homeowner, it is essential to plan for the ongoing and unexpected expenses associated with owning a property. Keeping some money in savings after closing can give you valuable financial flexibility when expenses arise.

    Why You Should Keep a Financial Cushion

    It may seem like a good idea to put as much money as possible toward your down payment, especially if you have saved enough for 20% or more. However, using all your available cash could leave you unprepared for unexpected expenses.

    A financial cushion can help you handle both planned and surprise costs without putting additional pressure on your budget. From home repairs to rising property taxes, having reserve funds can make homeownership more manageable.

    Property Taxes Can Increase

    Property taxes are an important ongoing cost of owning a home. As property values increase over time, your property assessment may also rise, which can result in higher property taxes.

    Although a higher tax bill can affect your monthly expenses, an increase in your home’s value can also be a positive sign. Planning for potential changes in property taxes can help you avoid surprises in your household budget.

    Repairs and Maintenance Are Part of Homeownership

    When you rent, you can generally contact a property manager when something breaks. As a homeowner, repairs and maintenance become your responsibility.

    A leaky faucet, broken garage door, malfunctioning air conditioner, or other unexpected issue can require immediate attention and money. Setting aside savings for these situations can make unexpected repairs less stressful.

    Don’t Forget Homeowners Insurance

    Homeowners insurance is another cost to consider. Since your home is one of the largest investments you may make, insurance protects if something happens to the property. It may also be required by your lender.

    Insurance premiums can vary and may be higher in certain high-risk areas. Understanding this expense before buying can help you create a more realistic estimate of your total housing costs.

    Home Improvements and Yard Maintenance Add Up

    After moving in, you may want to make improvements that personalize the property, such as refinishing floors, updating a bathroom, or making other upgrades. These projects can become expensive, especially when the scope expands beyond the original plan.

    Yard maintenance is another consideration. Whether you hire a service or handle the work yourself, lawn equipment, tools, seasonal maintenance, and outdoor furnishings can add to your expenses.

    Consider Your Financing Options

    If you do not have sufficient reserve funds after closing, discuss financing options with your lender that may allow you to put down less moneywhile keeping more cash available for future expenses. Private mortgage insurance may allow some borrowers to purchase with less than 20% down, depending on their loan program and qualifications.

    The key is to look beyond the down payment and consider the full Cost of Homeownership, including monthly payments, property taxes, insurance, maintenance, and unexpected repairs. By planning for both expected and unexpected expenses, you can enter your new home with greater financial confidence.

    Ready to Plan for the True Cost of Homeownership?

    Whether you’re buying your first home, moving to a new property, or exploring your financing options, we can help you understand your down payment, monthly costs, and overall homeownership expenses. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your goals and find the mortgage solution that’s right for you.

  • How Can a Renovation/Construction Loan Work?

    How Can a Renovation/Construction Loan Work?

    Buying a home that needs repairs or building improvements to an existing property can be challenging when you need to finance both the property and the work. A renovation or construction loan can help combine these costs into one financing solution, making it easier to manage a major home improvement project.

    What Is a Renovation or Construction Loan?

    A renovation or construction loan is designed to help borrowers finance the purchase, construction, or renovation of a property. Depending on the loan program, you may be able to use the funds for projects such as kitchen and bathroom upgrades, structural improvements, additions, or other qualifying renovations.

    Instead of paying for the entire project out of pocket, the loan can provide financing based on the property’s value and the planned improvements. Some programs are structured to include renovation costs in the overall mortgage.

    How Does the Process Work?

    The process typically starts with determining your project goals, estimated costs, and financing needs. You may need to provide contractor estimates, renovation plans, and other documentation required by the lender.

    The lender then evaluates your financial qualifications, the property, and the proposed improvements. In many cases, an appraisal considers the property’s expected value after the renovations are completed. If approved, the loan funds may be distributed in stages as the work progresses rather than all at once.

    This structure can help ensure that funds are available when needed while allowing the lender to monitor the project’s progress.

    What Can the Loan Cover?

    The eligible expenses depend on the specific loan program and lender. Renovation financing may cover improvements such as remodeling kitchens and bathrooms, replacing roofing, upgrading electrical or plumbing systems, making structural changes, or improving the property’s energy efficiency.

    Construction financing may also help cover costs associated with building a new home, including certain labor, materials, and other approved construction expenses.

    Because requirements vary, it is important to understand exactly which expenses are eligible before starting your project.

    Why Consider This Type of Financing?

    One potential advantage is convenience. Instead of managing separate financing for the property and renovation, a suitable loan may allow you to combine qualifying costs into one financing arrangement.

    It can also make it possible to purchase a property that may not otherwise meet your needs because of its condition. Rather than looking only for a move-in-ready home, you may have the flexibility to consider a property with renovation potential.

    However, renovation and construction loans can have additional requirements, documentation, timelines, and inspections. Careful planning is important before committing to a project.

    Plan Your Financing Before You Start

    A renovation or construction loan can be a useful option when you want to purchase, build, or improve a home while financing the project. Understanding the loan requirements, estimated costs, contractor process, and potential monthly payments can help you make a more informed decision.

    Planning to buy, build, or renovate a home in the United States? Get expert guidance on renovation financing, mortgage options, and the homebuying process. Call 201-745-3426 or email shaleenmahtani@gmail.com to speak with Shaleen Mahtani and explore financing options that fit your goals.

  • Understanding Common Self-Employed Business Types When Applying for a Mortgage

    Understanding Common Self-Employed Business Types When Applying for a Mortgage

    Being self-employed can provide flexibility and independence, but applying for a mortgage may require a closer look at how your business income is structured and reported. For mortgage borrowers, understanding your business structure can help you better prepare the financial documents lenders may need when evaluating your income.

    Self-employed borrowers can operate under several different business structures. The most common include sole proprietorships, partnerships, S corporations, corporations, and limited liability companies (LLCs). Each structure handles business income and tax reporting differently, which can affect the documentation used during the mortgage process.

    Sole Proprietorship

    A sole proprietorship is a business owned and operated by one person without a separate legal business entity. The owner receives the business profits directly and reports the income on their individual tax return. A sole proprietor typically uses IRS Schedule C to report business income and expenses.

    Because the business is not legally separate from the owner, the owner also has unlimited liability for the business.

    Partnership

    A partnership involves two or more people who own and operate a business together. Business profits and losses are generally passed through to the individual partners, with each partner responsible for taxes on their share of the income.

    Partners generally receive a Schedule K-1, while the partnership files IRS Form 1065. Depending on the arrangement, a partner may also receive guaranteed payments.

    S Corporation

    An S corporation is a separate legal business entity with shareholders. Its profits and losses generally pass through to the individual shareholders rather than being taxed as regular corporate income.

    A shareholder may receive income reported through a Schedule K-1 and may also receive W-2 income from the business. The business generally files IRS Form 1120-S.

    Corporation

    A corporation exists as a separate legal entity from its owners, who are shareholders. Unlike pass-through structures, the corporation pays taxes on its profits. Shareholders may receive distributions from the corporation in the form of dividends.

    Depending on how they are compensated, shareholders may receive 1099-DIV and/or W-2 income. The corporation generally files IRS Form 1120.

    Limited Liability Company (LLC)

    An LLC, or limited liability company, combines characteristics of different business structures. Its tax treatment can vary depending on how the LLC is structured for tax purposes. As a result, there is not one specific IRS tax form associated with every LLC.

    An LLC may use different IRS forms based on its tax classification and structure.

    Why Business Structure Matters for Mortgage Applications

    When applying for a mortgage as a self-employed borrower, the way your business is structured can influence how your income is documented and reviewed. Lenders may need to understand the source of your income, how business profits are reported, and which tax documents apply to your situation.

    Knowing your business structure and keeping accurate financial and tax records can make the mortgage process more organized. If you are self-employed and planning to purchase or refinance a home, preparing your documentation early can help you approach the application process with greater confidence.

    Understanding your business type is an important first step toward presenting a clear picture of your financial position to your mortgage professional.

    Ready to Navigate Your Mortgage Options as a Self-Employed Borrower?

    Whether you’re self-employed, purchasing a home, or refinancing your current mortgage, understanding how your business income is evaluated can help you prepare with confidence. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your mortgage goals and receive guidance on financing options that may best fit your needs.
  • What Is Private Mortgage Insurance?

    What Is Private Mortgage Insurance?

    Private mortgage insurance (PMI) is a type of insurance that may be required when you purchase a home with a conventional mortgage and make a down payment of less than 20% of the home’s purchase price. While PMI protects the lender if the borrower stops making mortgage payments, it can also help buyers purchase a home without waiting years to save for a larger down payment.

    How Does Private Mortgage Insurance Work?

    PMI is designed to reduce the lender’s risk when a borrower has less equity in the home. If you make a smaller down payment, the lender has less financial protection if the loan goes into default. PMI helps offset some of that risk.

    The cost of PMI varies based on factors such as your loan amount, down payment, credit history, and lender. Depending on your mortgage, PMI may be included in your monthly mortgage payment. In some cases, other payment arrangements may be available.

    For example, if you purchase a home for $300,000 and put down 10%, your down payment would be $30,000, leaving a $270,000 mortgage. Because your down payment is less than 20%, your lender may require PMI.

    Who Needs PMI?

    PMI is generally associated with conventional mortgages when the borrower has less than 20% equity in the home. However, mortgage insurance requirements can vary depending on the type of loan and the lender.

    Government-backed mortgage programs may have their own insurance requirements. For this reason, it is important to understand the specific terms of your mortgage before assuming that PMI will apply to your loan.

    How Much Does PMI Cost?

    The cost of PMI is not the same for every borrower. Your lender or mortgage professional can provide an estimate based on your financial situation and loan details.

    Although PMI adds to your housing costs, it may allow you to purchase a home sooner rather than waiting until you have enough savings for a 20% down payment. For some buyers, that flexibility can make homeownership more accessible.

    Can PMI Be Removed?

    In many cases, PMI on a conventional mortgage can eventually be removed when you build sufficient equity in your home. This may happen as you make mortgage payments and reduce your loan balance or as your home’s value increases, depending on the applicable requirements.

    The rules for removing PMI can vary, so homeowners should review their loan documents and communicate with their mortgage servicer to understand when they may qualify.

    Is PMI Right for You?

    PMI is not necessarily something to avoid at all costs. For some buyers, paying PMI may be worthwhile if it allows them to purchase a home with a smaller down payment and begin building equity sooner.

    If you are considering buying a home, understanding PMI can help you estimate your total monthly housing costs and compare different financing options. A mortgage professional can help you review your loan choices, explain potential insurance requirements, and determine which option may best fit your financial goals.

    Ready to Explore Your Mortgage Options?

    Planning to buy a home in the United States? Get personalized guidance on private mortgage insurance, down payment options, and mortgage solutions that fit your financial goals. Call 201-745-3426 or email shaleenmahtani@gmail.com to speak with Shaleen Mahtani and move forward with your home purchase with confidence.
  • Exploring the Different Mortgage Products Available to Homebuyers

    Exploring the Different Mortgage Products Available to Homebuyers

    Buying a home is one of the biggest financial decisions you may make, and choosing the right mortgage can be just as important as finding the right property. With several mortgage options available, understanding how each product works can help you make a more informed decision based on your financial situation and long-term goals.

    Here are some of the mortgage products available to homebuyers and what you should know about each.

    Conventional Mortgages

    Conventional mortgages are among the most common home financing options. These loans are not insured or guaranteed by the federal government and are generally available to borrowers who meet specific credit, income, and debt requirements.

    Depending on the lender and your financial profile, you may be able to qualify with a down payment as low as 3%. Conventional loans can be a good option for borrowers with stable income and solid credit who want flexible financing terms.

    FHA Loans

    FHA loans are insured by the Federal Housing Administration and are designed to make homeownership more accessible to borrowers who may not qualify for conventional financing.

    These loans can offer lower down payment requirements and more flexible credit guidelines. However, FHA loans typically include mortgage insurance costs, which can affect your overall monthly payment. Buyers should consider both the upfront and ongoing costs when evaluating this option.

    VA Loans

    For eligible veterans, active-duty service members, and certain surviving spouses, VA loans can provide valuable home financing benefits. These government-backed loans may offer competitive terms and, in many cases, no down payment requirement.

    VA loans also generally do not require private mortgage insurance. Eligibility requirements apply, so qualified borrowers should discuss their options with a mortgage professional to determine whether a VA loan is appropriate for their needs.

    USDA Loans

    USDA loans are designed to help eligible buyers purchase homes in qualifying rural and suburban areas. One of their notable features is the potential for 100% financing, meaning qualified borrowers may not need a down payment.

    Income and property eligibility requirements apply. For buyers who meet the program guidelines and are considering homes in eligible areas, a USDA loan may provide an alternative to traditional mortgage financing.

    Fixed-Rate Mortgages

    A fixed-rate mortgage keeps the interest rate the same throughout the loan term. This can make monthly principal and interest payments more predictable and easier to budget for over time.

    Common terms include 15-year and 30-year mortgages. A shorter loan term may help you pay off the mortgage faster and reduce the amount of interest paid over the life of the loan, while a longer term may provide lower monthly payments.

    Adjustable-Rate Mortgages

    An adjustable-rate mortgage, or ARM, typically starts with a fixed interest rate for a specific period before the rate can adjust according to the terms of the loan.

    ARMs may be worth considering for borrowers who expect to move or refinance before the adjustment period begins. However, future payments can change after the initial period, so it is important to understand the adjustment schedule, caps, and potential payment changes before choosing this option.

    Choosing the Right Mortgage Product

    The best mortgage product depends on several factors, including your credit profile, income, down payment, financial goals, expected time in the home, and comfort with potential payment changes.

    Comparing loan options carefully can help you understand both the short-term and long-term costs of homeownership. It is also important to consider more than just the interest rate. Loan fees, mortgage insurance, closing costs, and other expenses can affect the overall cost of borrowing.

    A mortgage professional can help you review the different mortgage products available and determine which options may fit your circumstances. Taking the time to understand your choices before making an offer can help you move forward with greater confidence.

    Ready to Explore Your Mortgage Options?

    Choosing the right mortgage begins with understanding your options and finding a solution that aligns with your goals. Contact Shaleen Mahtani for personalized guidance on your home financing options. You can reach Shaleen at 201-745-3426 or shaleenmahtani@gmail.com to discuss your mortgage needs. Lending services are available throughout the United States.

  • How Can You Best Compete in a Tight Inventory Market?

    How Can You Best Compete in a Tight Inventory Market?

    Buying a home can be challenging when there are fewer properties available and more buyers competing for the same homes. In a tight inventory market, desirable properties may receive multiple offers soon after listing. This can make the home-buying process feel stressful, especially for first-time buyers.

    However, limited inventory does not mean you have to overpay or settle for a home that does not meet your needs. With the right preparation and strategy, you can make your offer more competitive while staying within your financial limits.

    Get Mortgage Pre-Approved Early

    One of the most important steps you can take is getting pre-approved for a mortgage before you begin seriously shopping for a home. A pre-approval gives you a clearer idea of how much you may be able to borrow and helps demonstrate to sellers that you are a prepared buyer.

    Having your financing ready can also help you move quickly when you find the right property. In a competitive market, delays can mean losing an opportunity to another buyer.

    Know Your Budget and Limits

    Competition can make buyers feel pressured to increase their offers, but it is important to establish a realistic budget before making an offer. Consider not only the purchase price but also your potential monthly mortgage payment, property taxes, homeowners insurance, closing costs, and other expenses.

    Knowing your maximum comfortable price can help you make confident decisions rather than getting caught up in a bidding war.

    Make a Strong, Well-Prepared Offer

    Price is important, but it is not always the only factor sellers consider. A well-structured offer can make your proposal more attractive.

    Depending on your situation, factors such as a flexible closing timeline, a strong earnest money deposit, or fewer unnecessary contingencies may strengthen your offer. However, buyers should never remove important protections without understanding the potential risks.

    Working with an experienced real estate professional can help you determine which terms make sense for your situation.

    Be Ready to Act Quickly

    When inventory is limited, desirable homes may not remain available for long. Being prepared to make decisions quickly can give you an advantage.

    Keep your important financial documents organized, stay in communication with your lender, and know what you are looking for before you start touring properties. When the right home becomes available, you will be in a better position to act without unnecessary delays.

    Consider More Than Just the Perfect Home

    In a tight inventory market, flexibility can open up more opportunities. Consider homes in nearby neighborhoods or properties that may need minor updates. Expanding your search can help you find options that other buyers may overlook.

    You may also want to prioritize your must-have features and separate them from preferences that could be changed or added later.

    Ready to Compete With Confidence in a Tight Market?

    When inventory is limited, having your financing prepared can help you move quickly when the right home becomes available. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your mortgage options, understand your budget, and prepare for your next home purchase.

  • Best Negotiation Tactics for Homebuyers

    Best Negotiation Tactics for Homebuyers

    Buying a home is one of the biggest financial decisions you’ll make, and getting the right price can make a meaningful difference in your overall costs. While sellers set an asking price, that doesn’t always mean it is the final price. Knowing how to negotiate effectively can help you make a competitive offer while protecting your budget.

    Whether you’re a first-time buyer or an experienced homeowner, these negotiation tactics for homebuyers can help you approach the process with greater confidence.

    1. Understand the Local Market

    Before making an offer, research the housing market in the area where you want to buy. Look at recently sold homes with similar features, prices of comparable properties, and how long homes typically stay on the market.

    In a buyer-friendly market, you may have more room to negotiate on price and terms. In a competitive market, you may need to make a stronger offer to stand out. Understanding local conditions helps you determine what is reasonable instead of relying solely on the seller’s asking price.

    2. Get Pre-Approved Before Negotiating

    A mortgage pre-approval can strengthen your position when making an offer. It shows the seller that you have already taken steps to understand your financing and may be prepared to move forward.

    Being pre-approved can also help you establish a realistic budget. When you know how much you may be able to borrow, you can negotiate with a clear understanding of what you can comfortably afford.

    3. Avoid Making an Emotional Offer

    It’s easy to become emotionally attached to a home, especially when you find one that checks all your boxes. However, emotions can sometimes lead buyers to offer more than they originally planned.

    Set a budget before negotiations begin and determine the highest amount you are comfortable paying. Having a clear limit can help you stay focused and avoid making a decision that could create financial stress later.

    4. Look Beyond the Purchase Price

    Negotiation isn’t always about lowering the home’s price. Other terms can also affect the overall value of the deal.

    Depending on the situation, you may be able to negotiate seller concessions, closing costs, repairs, appliances, the closing date, or other terms included in the purchase agreement. A slightly higher offer with favorable terms could sometimes be more attractive than a lower offer with fewer benefits.

    5. Use the Home Inspection Wisely

    A home inspection can uncover issues that may not be obvious during a showing. If significant repairs are identified, you may have an opportunity to negotiate repairs, credits, or other adjustments, depending on the terms of your contract and local practices.

    Focus on meaningful issues rather than minor cosmetic imperfections. A reasonable approach can make negotiations more productive and keep the transaction moving forward.

    6. Know When to Walk Away

    One of the most important negotiation tactics for homebuyers is knowing your limits. If the seller will not agree to terms that fit your budget or financial goals, it may be better to walk away.

    There will always be other opportunities. Protecting your long-term financial well-being is more important than winning a negotiation on one particular property.

    Ready to Make a Stronger Home Offer?

    Whether you’re buying your first home or searching for your next property, having the right financing strategy can help you negotiate with confidence. Call 201-745-3426 or email shaleenmahtani@gmail.com  to discuss your homebuying goals, understand your financing options, and prepare for your next offer.
  • Mortgage Market Outlook: What Homebuyers Should Expect in 2026

    Mortgage Market Outlook: What Homebuyers Should Expect in 2026

    The housing market is entering a new phase in 2026, bringing both opportunities and challenges for prospective homebuyers. While mortgage rates remain higher than the record lows seen in previous years, experts expect the market to become more balanced as housing inventory grows and home price increases slow down.

    If you’re planning to buy a home this year, understanding the latest mortgage market outlook can help you make informed decisions and prepare for a successful home purchase.

    Mortgage Rates May Remain Stable

    Mortgage rates continue to be one of the biggest factors affecting affordability. Although rates may fluctuate throughout the year due to inflation, employment data, and economic conditions, many analysts expect them to remain relatively stable in 2026.

    Stable rates provide buyers with more confidence when budgeting for a home purchase. Since even a small change in interest rates can impact your monthly payment, it’s important to monitor market trends and lock in a competitive rate when the timing is right.

    Home Prices Are Growing at a Slower Pace

    After several years of rapid appreciation, home prices are expected to increase more gradually in 2026. This slower growth gives buyers more time to evaluate properties and negotiate offers without feeling pressured by intense competition.

    While prices will continue to vary depending on the local market, a slower pace of appreciation can improve affordability and make it easier for buyers to enter the housing market.

    Housing Inventory Is Improving

    One of the most encouraging trends for homebuyers is the increase in available homes. More homeowners are listing their properties, and new construction is helping expand inventory in many parts of the United States.

    A larger selection of homes offers several advantages:

    • More choices that fit different budgets and lifestyles
    • Less competition from multiple buyers
    • Greater negotiating power during the buying process
    • More time to compare homes before making an offer

    Although inventory levels differ by region, many buyers are finding more options than they did over the past few years.

    Financial Preparation Remains Essential

    Even in a more balanced market, lenders continue to review mortgage applications carefully. Preparing your finances before applying for a loan can improve your chances of approval and help you qualify for better loan terms.

    Before applying for a mortgage, consider:

    • Reviewing your credit score
    • Paying down existing debt where possible
    • Saving for your down payment and closing costs
    • Avoiding large purchases that could affect your credit
    • Organizing income and financial documents in advance

    Being financially prepared can make the mortgage approval process smoother and reduce unexpected delays.

    First-Time Homebuyers May Have More Opportunities

    First-time buyers may find 2026 to be a more favorable time to purchase a home. With increased inventory and slower home price growth, buyers have more flexibility and less pressure to make rushed decisions.

    Many lenders also continue to offer mortgage programs designed specifically for first-time buyers, including low down payment options and flexible financing for qualified applicants. Exploring these programs with a knowledgeable mortgage professional can help you find a loan that fits your budget and long-term goals.

    Ready to Buy a Home?

    Whether you’re purchasing your first home, moving to a new property, refinancing your current mortgage, or exploring home equity solutions, Shaleen Mahtani is here to help. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss mortgage options that align with your financial goals.

  • Home Affordability Tips in a High-Rate Market

    Home Affordability Tips in a High-Rate Market

    Buying a home when mortgage rates are high can feel challenging, but it doesn’t mean homeownership is out of reach. While higher interest rates increase monthly mortgage payments, buyers who plan carefully can still find affordable opportunities. In fact, many homebuyers are adjusting their strategies instead of waiting for rates to drop, especially since no one can predict exactly when borrowing costs will decrease.

    If you’re planning to purchase a home in today’s market, these practical affordability tips can help you stay within your budget while achieving your homeownership goals.

    Understand What You Can Truly Afford

    Before you begin house hunting, take an honest look at your finances. It’s easy to focus only on the maximum amount a lender may approve, but that doesn’t always reflect what fits comfortably into your monthly budget.

    Consider your:

    • Monthly income
    • Existing debt payments
    • Savings
    • Emergency fund
    • Expected homeownership costs such as property taxes, homeowners insurance, maintenance, and utilities

    Buying below your maximum budget can provide more financial flexibility, especially if interest rates remain elevated.

    Improve Your Credit Score

    Your credit score plays a significant role in determining the mortgage interest rate you receive. Even a modest improvement in your credit score may help you qualify for a lower rate, potentially saving thousands of dollars over the life of your loan.

    Before applying for a mortgage:

    • Pay bills on time.
    • Reduce credit card balances.
    • Avoid opening new credit accounts.
    • Review your credit report for errors and dispute any inaccuracies.

    A stronger credit profile can improve both your loan options and monthly affordability.

    Save for a Larger Down Payment

    Making a larger down payment reduces the amount you need to borrow, resulting in lower monthly mortgage payments. A higher down payment may also help you avoid private mortgage insurance (PMI) on conventional loans.

    While a 20% down payment isn’t required for every loan, increasing your savings before buying can make a noticeable difference in long-term affordability.

    Compare Multiple Loan Options

    Not every mortgage is the same. Different loan programs offer varying interest rates, down payment requirements, and qualification guidelines.

    Some buyers may benefit from:

    • Conventional loans
    • FHA loans
    • VA loans (for eligible military members and veterans)
    • USDA loans (for eligible rural properties)
    • Adjustable-rate mortgages (ARMs), depending on individual financial plans

    Comparing several loan options with a mortgage professional can help you identify the most cost-effective solution.

    Shop Around for Mortgage Rates

    Interest rates and lender fees vary between lenders. Even a small difference in your mortgage rate can significantly impact your monthly payment and total interest paid over the life of the loan.

    Obtaining quotes from multiple lenders allows you to compare:

    • Interest rates
    • Closing costs
    • Loan fees
    • Available mortgage programs

    Taking time to compare offers may lead to meaningful savings.

    Expand Your Home Search

    If homes in your preferred neighborhood exceed your budget, consider broadening your search area. Nearby communities may offer similar amenities at more affordable prices.

    You might also consider:

    • Smaller homes
    • Townhomes
    • Condominiums
    • Homes needing minor cosmetic updates
    • Newly developing neighborhoods

    Being flexible with location or property type can improve affordability without sacrificing your long-term goals.

    Consider Buying Now and Refinancing Later

    Many buyers postpone purchasing while waiting for lower interest rates. However, delaying your purchase could mean facing higher home prices or increased competition if rates eventually decline.

    If today’s payment fits comfortably within your budget, buying now may allow you to build equity sooner. Should mortgage rates fall in the future, refinancing may provide an opportunity to reduce your monthly payment.

    Reduce Other Monthly Debt

    Lowering your debt before applying for a mortgage can improve your debt-to-income (DTI) ratio, which lenders use to evaluate your ability to manage monthly payments.

    Paying down:

    • Credit card balances
    • Auto loans
    • Personal loans

    may improve your borrowing power and increase your chances of securing better loan terms.

    Take Advantage of Homebuyer Assistance Programs

    Many first-time and repeat homebuyers may qualify for local, state, or employer-sponsored assistance programs. These programs can help with:

    • Down payments
    • Closing costs
    • Low-interest financing
    • Grants for qualified buyers

    Exploring available assistance could make purchasing a home more affordable than expected.

    Work with an Experienced Mortgage Professional

    Navigating a high-rate market can be complex, but an experienced mortgage professional can help you evaluate your financing options and develop a strategy that aligns with your financial goals. From selecting the right loan program to identifying ways to improve affordability, expert guidance can simplify the homebuying process.

    Explore Your Mortgage Options

    Whether you’re buying your first home, upgrading to a larger property, refinancing your current mortgage, or exploring home equity solutions, Shaleen Mahtani can help you navigate today’s market with confidence. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss mortgage solutions tailored to your financial goals.
  • How to Prepare for a Mortgage Before House Hunting

    How to Prepare for a Mortgage Before House Hunting

    Buying a home is exciting, but jumping into house hunting before preparing for a mortgage can lead to disappointment. Many buyers find their dream home only to discover they don’t qualify for the loan they need or that the monthly payments are higher than expected.

    Getting mortgage-ready before you start searching gives you a clear budget, improves your confidence, and makes you a stronger buyer in a competitive market. Here’s how to prepare before you begin your home search.

    1. Check Your Credit Score

    Your credit score plays a major role in determining whether you qualify for a mortgage and what interest rate you’ll receive. A higher score can help you secure better loan terms, potentially saving thousands of dollars over the life of your loan.

    Before applying:

    • Review your credit reports for errors.
    • Pay all bills on time.
    • Reduce outstanding credit card balances.
    • Avoid opening new credit accounts.

    Improving your credit score before applying can increase your borrowing power.

    2. Understand Your Budget

    Just because a lender approves you for a certain amount doesn’t mean you should spend the maximum.

    Create a realistic monthly budget that includes:

    • Mortgage payment
    • Property taxes
    • Homeowners insurance
    • HOA fees (if applicable)
    • Utilities
    • Maintenance costs

    Knowing what you can comfortably afford helps narrow your home search and reduces financial stress after closing.

    3. Save for Your Down Payment

    A down payment is one of the biggest upfront expenses when buying a home. While some loan programs require as little as 3% down, putting more money down may reduce your monthly payment and eliminate private mortgage insurance (PMI) in some cases.

    It’s also important to keep your down payment funds in a documented account, as lenders typically require proof of where the money came from.

    4. Build Your Savings for Closing Costs

    Many first-time buyers focus only on the down payment and forget about closing costs.

    These may include:

    • Loan origination fees
    • Appraisal fees
    • Title insurance
    • Attorney or escrow fees
    • Recording fees
    • Prepaid taxes and insurance

    Having extra savings prevents last-minute financial stress during the closing process.

    5. Organize Your Financial Documents

    Mortgage lenders will ask for documentation to verify your income, assets, and employment.

    Gather these documents early:

    • Recent pay stubs
    • W-2s or tax returns
    • Bank statements
    • Employment information
    • Government-issued identification

    Having everything ready can speed up your mortgage approval.

    6. Avoid Major Financial Changes

    Once you’re preparing for a mortgage, it’s best to keep your finances stable.

    Avoid:

    • Financing a new car
    • Opening new credit cards
    • Making large purchases
    • Changing jobs without discussing it with your lender
    • Missing loan or credit card payments

    Lenders often review your financial situation again before closing.

    7. Get Pre-Approved

    A mortgage pre-approval is one of the most valuable steps before house hunting.

    During pre-approval, a lender reviews your finances and estimates how much you may be able to borrow. A pre-approval letter also shows sellers you’re a serious buyer, which can make your offer more competitive.

    Keep in mind that pre-approval is different from pre-qualification because it involves a more thorough review of your financial information.

    8. Learn About Your Mortgage Options

    Not every mortgage is the same. Different loan programs are designed for different financial situations.

    Depending on your needs, you may qualify for:

    • Conventional loans
    • FHA loans
    • VA loans
    • USDA loans
    • Fixed-rate mortgages
    • Adjustable-rate mortgages

    Understanding these options before shopping for a home helps you choose financing that fits your long-term goals.

    9. Work with an Experienced Mortgage Professional

    Buying a home involves many financial decisions, and having expert guidance can make the process much easier.

    An experienced mortgage professional can:

    • Explain available loan programs.
    • Estimate your monthly payments.
    • Help improve your approval chances.
    • Answer questions throughout the buying process.
    • Guide you from pre-approval to closing.

    Starting the conversation early gives you time to prepare and avoid unexpected obstacles.

    Ready to Start Your Homebuying Journey?

    Preparing for a mortgage before house hunting helps you shop with confidence and avoid unnecessary delays. From improving your credit and saving for upfront costs to getting pre-approved, every step brings you closer to homeownership.

    Whether you’re buying your first home, upgrading to a new property, or exploring your mortgage options, Shaleen Mahtani is here to help. Call 201-745-3426 or email shaleenmahtani@gmail.com  to discuss the mortgage solutions that best fit your financial goals.

  • Mortgage Pre-Approval Checklist for First-Time Buyers

    Mortgage Pre-Approval Checklist for First-Time Buyers

    Buying a home is exciting, but getting ready for a mortgage can feel overwhelming. One of the best ways to simplify the process is by getting pre-approved before you start house hunting. A mortgage pre-approval helps you understand how much you may be able to borrow and shows sellers that you’re a serious buyer.

    Use the printable checklist below to stay organized and make sure you have everything ready before applying for mortgage pre-approval.

    Mortgage Pre-Approval Checklist

    Follow this simple checklist to make sure you have everything ready before submitting your mortgage pre-approval application. 

    Personal Information

    ☐ Government-issued photo ID (Driver’s license or passport)

    ☐ Social Security Number or Tax Identification Number

    ☐ Proof of current address

    ☐ Contact information

    Proof of Income

    ☐ Pay stubs from the last 30 days

    ☐ W-2 forms from the past two years

    ☐ Federal tax returns from the past two years

    ☐ Bonus, commission, or overtime income documentation (if applicable)

    ☐ Self-employed? Gather two years of business tax returns and profit/loss statements

    Employment Verification

    ☐ Employer contact information

    ☐ Employment verification letter (if requested)

    ☐ Documentation for additional sources of income

    Bank and Asset Information

    ☐ Bank statements from the last two to three months

    ☐ Savings account statements

    ☐ Investment account statements

    ☐ Retirement account statements (if applicable)

    ☐ Documentation for any gift funds being used for the down payment

    Debt Information

    ☐ Credit card balances

    ☐ Auto loan information

    ☐ Student loan details

    ☐ Personal loan information

    ☐ Monthly debt payment records

    Down Payment and Closing Costs

    ☐ Verify your available down payment funds

    ☐ Budget for estimated closing costs

    ☐ Review available assistance programs if eligible

    Credit Review

    ☐ Check your credit score

    ☐ Review your credit report for errors

    ☐ Avoid opening new credit accounts before closing

    ☐ Continue making all payments on time

    Before Applying

    ☐ Compare mortgage lenders

    ☐ Gather all required documents into one folder

    ☐ Prepare questions for your loan officer

    ☐ Submit your mortgage pre-approval application

    Why Getting Organized Matters

    Having your paperwork ready before applying can make the mortgage process much smoother. Lenders can review your application more quickly when your documents are complete and accurate. It also helps reduce delays and gives you confidence as you begin shopping for your new home.

    A mortgage pre-approval also gives you a better understanding of your price range, making it easier to focus on homes that fit your budget.

    Ready to Start Your Homebuying Journey?

    Whether you’re buying your first home, upgrading to a new property, or refinancing your current mortgage, being prepared is the first step toward success. If you’re ready to get pre-approved or have questions about your mortgage options, Shaleen Mahtani is here to help. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss the mortgage solution that best fits your financial goals.

  • Understanding Closing Costs: What Every Buyer Should Know

    Understanding Closing Costs: What Every Buyer Should Know

    Buying a home is one of the biggest financial decisions you’ll make, and it’s important to budget for more than just the down payment. One expense that often surprises first-time buyers is closing costs. These are the fees and expenses paid when your home purchase is finalized, and understanding them in advance can help you avoid unexpected financial stress.

    Knowing what closing costs include and planning for them in advance will make your homebuying experience smoother and more predictable.

    What Are Closing Costs?

    Closing costs are the various fees associated with finalizing your mortgage and transferring property ownership. They are typically paid on closing day, although some costs may be paid earlier in the process.

    In most cases, closing costs range from 2% to 5% of the home’s purchase price, depending on the loan type, property location, and lender requirements.

    Common Closing Costs

    While every transaction is different, buyers can generally expect to pay for several common expenses, including:

    • Loan origination fees
    • Appraisal fees
    • Home inspection fees
    • Title search and title insurance
    • Attorney or settlement fees (where applicable)
    • Recording fees
    • Credit report fees
    • Prepaid property taxes and homeowners insurance
    • Prepaid mortgage interest

    Your lender will provide a Loan Estimate early in the mortgage process, outlining the expected closing costs so you can better prepare financially.

    Can Closing Costs Be Reduced?

    Yes, there are several ways buyers may be able to lower their closing costs. Some lenders offer lender credits in exchange for a slightly higher interest rate, while certain loan programs or local homebuyer assistance programs may help cover part of these expenses.

    In some situations, buyers may also negotiate with the seller to contribute toward closing costs as part of the purchase agreement.

    Don’t Forget Prepaid Expenses

    Some items included in your closing costs aren’t lender fees at all. Prepaid expenses, such as homeowners insurance premiums, property taxes, and daily mortgage interest, are collected at closing to ensure these obligations are covered once you take ownership of the home.

    These prepaid costs can vary depending on your closing date and local tax requirements.

    Review Your Closing Disclosure Carefully

    A few days before closing, you’ll receive a Closing Disclosure that outlines your final loan terms and all associated costs. Compare this document with your original Loan Estimate to ensure there are no unexpected changes or errors.

    If you have questions about any fee, don’t hesitate to ask your lender or mortgage professional for clarification before signing the paperwork.

    Plan for a Smooth Closing

    The best way to avoid surprises is to prepare early. Set aside funds for both your down payment and closing costs, maintain open communication with your lender, and keep your financial documents organized throughout the mortgage process.

    Proper planning helps ensure you’re financially ready when it’s time to receive the keys to your new home.

    Understand Your Closing Costs with Confidence

    Planning to buy a home in the United States? Get expert guidance on closing costs, mortgage options, and every step of the homebuying process. Call 201-745-3426 or email shaleenmahtani@gmail.com to speak with Shaleen Mahtani and make your home purchase with confidence.
  • When Should You Refinance Your Mortgage?

    When Should You Refinance Your Mortgage?

    Refinancing your mortgage can be a smart financial move, but timing is everything. Whether your goal is to lower your monthly payments, reduce your interest rate, or tap into your home’s equity, refinancing at the right time can help you save thousands of dollars over the life of your loan. Understanding when it makes sense to refinance can help you make the most of this opportunity.

    Interest Rates Have Dropped

    One of the most common reasons homeowners refinance is to take advantage of lower interest rates. Even a small reduction in your mortgage rate can significantly decrease your monthly payment and the total interest you’ll pay over the life of your loan.

    If current rates are noticeably lower than the rate on your existing mortgage, refinancing may be worth considering. A mortgage professional can help you calculate whether the long-term savings outweigh the closing costs.

    Your Credit Score Has Improved

    Your credit score plays a major role in determining the interest rate you qualify for. If your credit has improved since you first purchased your home, you may now qualify for a lower rate.

    Making on-time payments, reducing debt, and improving your overall financial profile can increase your chances of securing better loan terms through refinancing.

    You Want Lower Monthly Payments

    If your monthly mortgage payment has become difficult to manage, refinancing could help reduce your financial burden. Extending the loan term or qualifying for a lower interest rate can make your monthly payments more affordable.

    While extending your loan term may increase the total interest paid over time, it can provide valuable breathing room in your monthly budget.

    You Want to Pay Off Your Loan Faster

    Refinancing isn’t only about lowering payments. Many homeowners refinance from a 30-year mortgage into a 15-year loan to pay off their home sooner and reduce the total interest paid.

    Although monthly payments may be higher, building equity faster and becoming mortgage-free years earlier can provide long-term financial benefits.

    You Need Access to Home Equity

    A cash-out refinance allows you to replace your current mortgage with a larger loan and receive the difference in cash. Many homeowners use these funds for home renovations, debt consolidation, education expenses, or other major financial needs.

    Before choosing this option, consider how increasing your loan balance may affect your long-term financial goals.

    Your Adjustable-Rate Mortgage Is Changing

    If you currently have an adjustable-rate mortgage (ARM) and your fixed-rate period is ending, refinancing into a fixed-rate mortgage can provide greater stability.

    Locking in a fixed interest rate protects you from future rate increases and makes budgeting easier with predictable monthly payments.

    Consider the Costs Before Refinancing

    While refinancing offers many benefits, it’s important to account for closing costs, lender fees, and the amount of time you plan to stay in your home. In many cases, homeowners should expect to remain in the property long enough to recover the refinancing costs through monthly savings.

    A trusted mortgage expert can help you evaluate your break-even point and determine whether refinancing is the right financial decision.

    Explore Your Refinancing Options

    Thinking about refinancing your mortgage in the United States? Whether you’re looking to lower your monthly payments, secure a better interest rate, or access your home’s equity, refinancing could help you reach your financial goals. Call 201-745-3426 or email shaleenmahtani@gmail.com  to discuss your options with an experienced mortgage professional.

  • Fed Holds Interest Rates Steady: What It Means for Homebuyers and Homeowners

    Fed Holds Interest Rates Steady: What It Means for Homebuyers and Homeowners

    The Federal Reserve has decided to keep interest rates unchanged, a move that many economists expected. While the decision doesn’t directly affect mortgage rates overnight, it provides valuable insight into the Fed’s outlook on inflation and the overall economy. For homebuyers, homeowners, and anyone considering refinancing, understanding this decision can help you make more informed financial choices.

    Why the Fed Chose to Hold Rates

    The Federal Reserve’s primary goal is to maintain stable prices while supporting a healthy job market. Although inflation has cooled compared to previous years, officials believe it remains above their long-term target. At the same time, the U.S. economy has continued to show resilience, with steady consumer spending and a relatively strong labor market.

    Because of these mixed signals, policymakers decided that keeping interest rates where they are is the best course of action for now. This allows them more time to evaluate future economic data before making any additional changes.

    Different Opinions Within the Federal Reserve

    While the final decision was to leave rates unchanged, not every policymaker agreed. Some officials believe borrowing costs should begin to come down as inflation continues to ease. Others argue that maintaining current rates is the safer approach until there is stronger evidence that inflation is fully under control.

    These differing viewpoints highlight that future policy decisions will largely depend on upcoming economic reports, including inflation, employment, and consumer spending.

    What It Means for Mortgage Rates

    Many people assume mortgage rates move in lockstep with the Federal Reserve’s benchmark rate, but that’s not always the case. Several factors, including inflation expectations, Treasury bond yields, and conditions in the financial markets influence mortgage rates.

    As a result, mortgage rates may fluctuate even when the Federal Reserve leaves its benchmark rate unchanged. Borrowers should pay close attention to market trends rather than expecting immediate changes after every Fed announcement.

    What Homebuyers Should Consider

    For prospective buyers, the Fed’s decision brings a measure of stability to the housing market. While mortgage rates remain higher than the record lows seen a few years ago, buyers have more time to evaluate their finances, compare loan options, and prepare for homeownership.

    Getting pre-approved for a mortgage can help you understand your budget and strengthen your position when making a home offer. Buyers should also remember that waiting for significantly lower rates may not always be the best strategy, especially if home prices continue to rise.

    What This Means for Homeowners

    Homeowners considering refinancing should continue monitoring mortgage rates and discussing options with a trusted mortgage professional. Even without a Fed rate cut, favorable market conditions can still create opportunities to lower monthly payments or achieve other financial goals.

    Every homeowner’s situation is unique, so it’s important to review your finances before deciding whether refinancing makes sense.

    Looking Ahead

    The Federal Reserve has indicated that future decisions will depend on incoming economic data rather than a fixed timeline. Inflation trends, job growth, and overall economic performance will all play a role in determining whether interest rates remain steady or change in the coming months.

    For buyers and homeowners, staying informed is the best way to prepare for changes in the mortgage market. Understanding how economic conditions influence borrowing costs can help you make confident decisions when financing or refinancing a home.

    Explore Your Mortgage Options

    Whether you’re buying your first home, refinancing your current mortgage, or exploring home equity solutions anywhere in the United States, Shaleen Mahtani is here to help. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss the mortgage options that best fit your financial goals.

  • Mortgage Relationship Pricing: A Smart Way to Lower Your Interest Rate 

    Mortgage Relationship Pricing: A Smart Way to Lower Your Interest Rate 

    When you’re shopping for a mortgage, even a small reduction in your interest rate can make a noticeable difference over the life of your loan. If you already have substantial savings or investments with your bank, you may qualify for relationship pricing, a benefit that rewards existing customers with lower mortgage rates.

    Understanding how relationship pricing works can help you maximize your savings, whether you’re buying a new home or refinancing an existing mortgage.

    What Is Mortgage Relationship Pricing?

    Mortgage relationship pricing is a program offered by some lenders that provides discounted mortgage interest rates to customers who maintain qualifying deposit or investment accounts with the same financial institution.

    Instead of offering the same rate to every borrower, lenders may reduce your interest rate based on the value of your banking and investment relationship. The larger your qualifying assets, the greater the potential discount on your mortgage.

    How Does It Work?

    Relationship pricing is generally based on the amount of eligible assets you have with the lender prior to your mortgage closing. These assets may include checking accounts, savings accounts, or professionally managed investment accounts.

    Some lenders also offer additional savings if you enroll in automatic mortgage payments and electronic statements. These features not only simplify your monthly payments but may also help reduce your interest rate even further.

    Who Can Benefit?

    Relationship pricing can be especially valuable for:

    • Homebuyers purchasing a primary or second home
    • Borrowers refinancing an existing mortgage
    • Individuals with significant savings or investment portfolios
    • Clients who already bank with the mortgage lender

    If you’re already working with a financial institution that offers relationship pricing, it’s worth asking whether your current assets could help lower your mortgage rate.

    Can You Still Qualify After Closing?

    In some cases, borrowers who move qualifying assets to the lender shortly after closing may still be eligible for a one-time interest rate adjustment. While eligibility requirements vary by lender, this option can be beneficial if you’re planning to consolidate your banking or investment accounts after purchasing your home.

    It’s important to discuss these opportunities with your mortgage professional before or shortly after closing to understand the available options and deadlines.

    Things to Keep in Mind

    While relationship pricing can provide meaningful savings, there are a few important considerations:

    • Not every mortgage program qualifies for relationship pricing.
    • Assets used to qualify for the discount may not be eligible to cover your down payment or closing costs.
    • Eligibility requirements and discount amounts vary by lender.
    • You’ll still need to meet all credit, income, and underwriting guidelines to qualify for the mortgage.

    Reviewing the program details with your loan officer can help you determine whether relationship pricing is the right fit for your financial situation.

    Explore Your Mortgage Savings

    Looking to buy a home or refinance in the United States? You may qualify for mortgage savings through relationship pricing and other available programs. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your options with an experienced mortgage professional.

  • Why Millions of Vacant Homes Aren’t Solving the Housing Shortage 

    Why Millions of Vacant Homes Aren’t Solving the Housing Shortage 

    If you’re actively searching for a home, you’ve likely noticed that finding the right property can still be a challenge. While it may seem like there should be more homes available, recent data tells a different story. Although millions of homes across the United States are sitting vacant, only a small percentage are actually on the market; understanding why can help buyers make sense of today’s competitive housing landscape.

    According to a recent LendingTree analysis of U.S. Census Bureau data, approximately 14.5 million homes, or 10.1% of all homes nationwide, are vacant. However, fewer than 800,000 of those homes are currently listed for sale. This means that most vacant homes aren’t available for buyers, which continues to limit housing inventory in many markets.

    Why Are So Many Homes Empty?

    A vacant home doesn’t always mean it’s abandoned or waiting for a new owner. Many properties are used as vacation homes or seasonal residences and remain empty for much of the year. Others are temporarily vacant because they’re being renovated, involved in probate or legal proceedings, or waiting for new tenants to move in.

    Some homes are also under foreclosure or require repairs before they can be sold. These situations keep properties out of the active housing supply, reducing the number of homes available for prospective buyers.

    Limited Inventory Continues To Challenge Buyers

    Even though millions of homes are vacant, the supply of homes for sale remains historically tight in many areas. This imbalance between supply and demand has kept home prices elevated, despite changes in mortgage rates.

    For first-time homebuyers and families looking to upgrade, limited inventory often means more competition, fewer choices, and less negotiating power. Buyers may also need to act quickly when desirable homes become available.

    Housing Markets Differ by Location

    Vacancy rates vary significantly from one state to another. States such as Maine, Vermont, and Alaska report some of the highest vacancy rates, largely because they have many seasonal and vacation homes. In contrast, states with lower vacancy rates often experience tighter housing markets due to strong demand and limited supply.

    That’s why national housing statistics don’t always reflect what’s happening in your local market. Factors like job growth, population trends, and new construction play a much bigger role in determining housing availability and affordability in your area.

    What This Means for Homebuyers

    The key takeaway is that vacant homes and available homes are not the same thing. While headlines about millions of empty homes may sound encouraging, most of those properties aren’t available for purchase.

    If you’re planning to buy a home, it’s important to understand your local market and be prepared before you begin your search. Getting pre-approved, knowing your budget, and working with an experienced mortgage professional can help you move quickly when the right opportunity comes along.

    Although housing inventory remains limited, buyers who stay informed and have a solid financing plan are often better positioned to achieve their homeownership goals.

    Need Help Navigating Today’s Housing Market?

    If you’re planning to buy or refinance a home in the United States, understanding today’s housing market is essential. We can help you explore your mortgage options and make informed financing decisions. Call 201-745-3426 or email shaleenmahtani@gmail.com to get started.

  • Home Price Growth Slows in 2026: What It Means for Homebuyers in the United States

    Home Price Growth Slows in 2026: What It Means for Homebuyers in the United States

    If you’ve been waiting for a better time to buy a home, 2026 may bring some encouraging news. According to the latest housing market forecast, home prices are expected to rise more slowly than previously anticipated, giving buyers a better chance to enter the market without facing the rapid price increases seen in recent years.

    While affordability challenges haven’t disappeared, slower home price growth, stable mortgage rates, and rising household incomes are creating more favorable conditions for many buyers across in the United States.

    Home Prices Are Rising at a Slower Pace

    Housing experts now expect U.S. home prices to increase by just 1.2% through the end of 2026, down from earlier projections. This marks a significant slowdown compared to the sharp appreciation experienced during the past few years.

    For buyers, this means homes are becoming more reasonably priced, allowing more time to compare properties and make informed decisions instead of rushing into bidding wars.

    Although prices are still increasing, they’re doing so at a much healthier pace, helping improve affordability across many markets.

    Mortgage Rates Remain Elevated but Stable

    Mortgage rates continue to play a major role in purchasing decisions. Current forecasts suggest rates will average around 6.3% through the remainder of the year.

    While that’s still higher than the historically low rates many buyers remember, the market has become much more predictable. Stable rates make it easier for buyers to budget and plan their financing without worrying about sudden spikes.

    If you’re purchasing in the United States, getting pre-approved and locking in a competitive rate can still make a meaningful difference in your monthly payment.

    Affordability Is Gradually Improving

    One of the most encouraging trends is that wages are expected to continue growing while home prices increase more slowly. As household incomes rise, the percentage of income needed for monthly mortgage payments is beginning to decline.

    This doesn’t mean homes are suddenly inexpensive, but it does indicate that many families may find homeownership more attainable than it was just a year ago.

    For first-time buyers especially, this gradual improvement could create new opportunities to enter the market.

    Buyers Have More Negotiating Power

    Housing inventory has been improving in many areas, giving buyers more options than they had during the extremely competitive seller’s market.

    With homes spending slightly longer on the market, buyers may have greater leverage to negotiate:

    • Purchase price
    • Seller concessions
    • Closing costs
    • Repair requests
    • Flexible closing timelines

    Instead of competing with dozens of offers, buyers may now have the opportunity to carefully evaluate properties and negotiate better terms.

    Sellers Need to Price Homes Realistically

    The market is becoming more balanced, meaning sellers can no longer rely solely on rapidly rising prices.

    Homes that are priced competitively from the beginning generally attract stronger interest than those listed above market value. Buyers today are better informed, have more inventory to choose from, and are willing to walk away if a property feels overpriced.

    For sellers in the United States, proper pricing remains one of the most important factors for achieving a successful sale.

    What This Means for Homebuyers Across the United States

    Local market conditions can differ from national trends, but the overall outlook is encouraging.

    If you’re planning to buy a home this year, you may benefit from:

    • Slower home price appreciation
    • More homes available for sale
    • Stable mortgage rates
    • Improving affordability
    • Greater negotiating opportunities

    Every real estate market is unique, so working with an experienced mortgage professional can help you understand your financing options and determine the best time to purchase.

    Ready to Explore your Home Financing Options? 

    Whether you’re buying your first home, moving to a new property, or refinancing, we are here to help you navigate today’s mortgage market with confidence. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your goals and find the mortgage solution that’s right for you.
  • Top Home Appraisal Tips to Maximize Your Property Value

    Top Home Appraisal Tips to Maximize Your Property Value

    Whether you’re planning to sell your home, refinance your mortgage, or simply want to understand its current market value, a home appraisal plays an important role. An appraisal is a professional assessment of your property’s value based on its condition, location, size, and recent sales of similar homes in the area.

    While you can’t control the local real estate market, you can take steps to make sure your home is presented in the best possible way. Here are some practical home appraisal tips that can help maximize your property’s value.

    Improve Your Home’s Curb Appeal

    First impressions matter. The exterior of your home is the first thing an appraiser sees, and a clean, well-maintained appearance can create a positive impression. Mow the lawn, trim bushes, remove weeds, and keep walkways clear. Simple updates like planting flowers, repainting the front door, or replacing worn house numbers can make your home look more inviting.

    Complete Small Repairs Before the Appraisal

    Minor issues may seem unimportant, but they can signal a lack of maintenance. Fix dripping faucets, squeaky doors, cracked windows, loose railings, chipped paint, and broken light fixtures. Taking care of these small repairs shows that the home has been properly maintained over time.

    Deep Clean Every Room

    A spotless home won’t directly increase its appraised value, but it helps demonstrate that the property has been well cared for, with clean floors, windows, kitchens, bathrooms, and appliances. Remove clutter from countertops and organize storage areas to make the home appear more spacious.

    Highlight Recent Upgrades

    If you’ve invested in home improvements, be sure the appraiser knows about them. Renovated kitchens, updated bathrooms, new flooring, energy-efficient windows, a new roof, or upgraded HVAC systems can all contribute to your home’s value.

    Prepare a simple list of improvements, including the year they were completed and any available receipts or permits. This information helps ensure valuable updates are considered during the appraisal.

    Ensure Everything Is Accessible

    The appraiser will need access to every part of the home, including the garage, basement, attic, and utility areas. Unlock gates, clear pathways, and move any items blocking access. A smooth inspection allows the appraiser to fully evaluate the property without unnecessary delays fully.

    Know Your Neighborhood

    While appraisers conduct their own research, it can be helpful to mention nearby amenities that add value, such as highly rated schools, parks, shopping centers, public transportation, or recent neighborhood improvements. These factors may positively influence the property’s overall market appeal.

    Be Present, but Give the Appraiser Space

    It’s perfectly fine to greet the appraiser and answer questions, but avoid following them throughout the inspection. Provide your list of upgrades and any relevant documents, then allow them to complete their work independently and professionally.

    Need Guidance on Your Home Appraisal?

    Preparing for a home appraisal can feel overwhelming, especially if you’re buying, selling, or refinancing. If you have questions about the appraisal process or your mortgage options, call 201-745-3426 or email shaleenmahtani@gmail.com  for personalized guidance and professional support.

  • Home Equity Loan: Everything You Need to Know Before You Borrow

    Home Equity Loan: Everything You Need to Know Before You Borrow

    A home equity loan allows homeowners to borrow money using the equity they have built in their property. Equity is the difference between your home’s current market value and the amount you still owe on your mortgage. If you have paid down a significant portion of your mortgage or your home’s value has increased, you may qualify for a home equity loan.

    Before applying, it’s important to understand how these loans work, their benefits, and the potential risks involved.

    How Does a Home Equity Loan Work?

    A home equity loan provides you with a lump sum of money that you repay through fixed monthly payments over a set period. Because your home serves as collateral, these loans often come with lower interest rates than credit cards or personal loans.

    The amount you can borrow depends on several factors, including your available home equity, credit score, income, and lender requirements. Many lenders allow homeowners to borrow up to 80% or 85% of their home’s equity, although limits vary.

    Common Uses for a Home Equity Loan

    Many homeowners use a home equity loan for large expenses that can improve their financial situation or property value. Common uses include:

    • Home renovations and repairs
    • Debt consolidation
    • College tuition
    • Medical expenses
    • Major home improvements
    • Emergency financial needs

    Using the loan for projects that increase your home’s value may provide long-term financial benefits.

    Benefits of a Home Equity Loan

    A home equity loan offers several advantages for qualified borrowers.

    One of the biggest benefits is predictable monthly payments. Since most home equity loans have fixed interest rates, you’ll know exactly how much you owe each month.

    These loans also typically offer lower interest rates than unsecured borrowing options because your home secures the loan. In addition, borrowers can often access larger loan amounts than they could with personal loans.

    Risks to Consider Before Borrowing

    Although a home equity loan can be a useful financial tool, it also comes with risks.

    Because your home is used as collateral, missing payments could put your property at risk of foreclosure. Borrowing more than you can comfortably repay may also create financial stress.

    It’s important to borrow only what you truly need and ensure the monthly payments fit within your budget. Comparing offers from multiple lenders can help you find competitive rates and favorable terms.

    How to Qualify for a Home Equity Loan

    Lenders typically review several factors before approving a loan, including:

    • Sufficient home equity
    • Good credit score
    • Stable income
    • Reasonable debt-to-income ratio
    • Strong payment history

    Preparing your financial documents and checking your credit before applying can improve your chances of approval.

    Need Help Choosing the Right Home Equity Loan?

    If you’re considering a home equity loan and want to understand your borrowing options, we’re here to help. Whether you’re planning home improvements, consolidating debt, or covering a major expense, personalized guidance can help you make the right financial decision. Call 201-745-3426 or email shaleenmahtani@gmail.com  to discuss your home equity loan options and get expert mortgage guidance.

  • What Is a HELOC? Everything You Need to Know Before You Borrow

    What Is a HELOC? Everything You Need to Know Before You Borrow

    A Home Equity Line of Credit (HELOC) is a flexible way for homeowners to borrow money using the equity they have built in their home. Whether you’re planning home renovations, paying for education, consolidating debt, or covering unexpected expenses, a HELOC can provide access to funds when you need them. Before applying, it’s important to understand how it works, its benefits, and the potential risks.

    What Is a HELOC?

    A HELOC is a revolving line of credit secured by your home’s equity. Equity is the difference between your home’s current market value and the remaining balance on your mortgage.

    Unlike a traditional home equity loan, which gives you a lump sum, a HELOC allows you to borrow only what you need, up to your approved credit limit. As you repay the borrowed amount, you can access those funds again during the draw period, making it similar to a credit card backed by your home.

    How Does a HELOC Work?

    A HELOC typically has two phases:

    Draw Period: During this period, which often lasts 5 to 10 years, you can borrow money as needed. Many lenders require only interest payments during this time, although some allow you to pay toward the principal as well.

    Repayment Period: Once the draw period ends, you can no longer borrow additional funds. You begin repaying both the principal and interest, usually over 10 to 20 years.

    Because most HELOCs have variable interest rates, your monthly payment may increase or decrease as market rates change.

    Benefits of a HELOC

    A HELOC offers several advantages for homeowners:

    • Flexible access to funds whenever you need them.
    • Interest is charged only on the amount you borrow.
    • Often comes with lower interest rates than credit cards or personal loans.
    • Can be used for a wide range of expenses, including home improvements, education, medical bills, or debt consolidation.

    When used responsibly, a HELOC can be an affordable financing option for major expenses.

    Things to Consider Before Borrowing

    While a HELOC can be useful, it isn’t the right choice for everyone. Since your home serves as collateral, failing to make payments could put your property at risk.

    You should also consider that variable interest rates may increase over time, making your monthly payments less predictable. Before borrowing, review your budget carefully and borrow only what you can comfortably repay.

    It’s also a good idea to compare offers from multiple lenders, paying attention to interest rates, fees, repayment terms, and borrowing limits.

    Is a HELOC Right for You?

    A HELOC may be a smart option if you have significant home equity, a stable income, and a clear plan for using the funds. It works especially well for ongoing expenses, such as remodeling projects, where you may not need all the money at once.

    However, if you need a fixed amount with predictable monthly payments, a home equity loan may be a better fit. Speaking with a mortgage professional can help you determine which financing option best matches your financial goals.

    Need Help Deciding if a HELOC Is Right for You?

    If you’re considering a HELOC and want to understand how it fits into your financial plans, professional guidance can make the process easier. Call 201-745-3426 or email shaleenmahtani@gmail.com  to discuss your options and find the financing solution that best meets your needs.

  • Home Equity Loan vs HELOC: Which Option Is Right for You?

    Home Equity Loan vs HELOC: Which Option Is Right for You?

    If you need extra funds for home improvements, debt consolidation, or other major expenses, borrowing against your home’s equity can be a smart option. Two of the most common choices are a home equity loan and a Home Equity Line of Credit (HELOC). While both allow you to use the equity you’ve built in your home, they work differently and are suited for different financial needs.

    Understanding the differences can help you choose the option that best fits your goals.

    What Is a Home Equity Loan?

    A home equity loan allows you to borrow a lump sum based on the equity in your home. You receive the money all at once and repay it through fixed monthly payments over a set period.

    Because home equity loans typically come with a fixed interest rate, your monthly payment remains the same throughout the life of the loan. This makes budgeting easier and gives you predictable repayment terms.

    A home equity loan may be a good choice if you’re planning a one-time expense, such as:

    • A major home renovation
    • Paying off high-interest debt
    • Covering college tuition
    • Financing a large purchase

    What Is a HELOC?

    A Home Equity Line of Credit (HELOC) works more like a credit card. Instead of receiving all the money upfront, you’re approved for a credit limit and can borrow only what you need during the draw period.

    Most HELOCs have variable interest rates, meaning your payments can change if market rates increase or decrease. After the draw period ends, you’ll begin repaying both the principal and interest.

    A HELOC is often a better fit for expenses that happen over time, such as:

    • Ongoing home improvement projects
    • Emergency expenses
    • Medical bills
    • Long-term financial flexibility

    Home Equity Loan vs HELOC: Key Differences

    Although both options use your home’s equity as collateral, there are several important differences.

    Home Equity Loan

    • Receive a lump sum upfront
    • Fixed interest rate
    • Predictable monthly payments
    • Best for one-time expenses

    HELOC

    • Borrow as needed up to your approved limit
    • Usually has a variable interest rate
    • Flexible borrowing and repayment during the draw period
    • Best for ongoing or unpredictable expenses

    Which Option Is Right for You?

    The right choice depends on how you plan to use the money.

    A home equity loan is often the better option if you know exactly how much you need and want stable monthly payments. The fixed interest rate provides peace of mind, especially when interest rates are rising.

    A HELOC may be the better choice if your expenses are spread out over time or you’re unsure how much you’ll need. It offers flexibility and allows you to borrow only what you use, which can help reduce interest costs if managed responsibly.

    Before choosing either option, consider your budget, repayment ability, and whether you’re comfortable with a variable interest rate.

    Things to Consider Before Borrowing

    Since both loans are secured by your home, failing to make payments could put your property at risk. Lenders also evaluate your credit score, income, debt-to-income ratio, and available home equity before approving your application.

    It’s also important to compare interest rates, fees, repayment terms, and borrowing limits from different lenders. Taking the time to review your options can help you make a confident financial decision.

    Need Help Choosing Between a Home Equity Loan and a HELOC?

    Every homeowner’s financial situation is different. If you’re considering tapping into your home’s equity and want expert guidance, call 201-745-3426 or email shaleenmahtani@gmail.com. You’ll receive personalized advice to help you choose the financing option that best fits your needs and long-term goals.

  • How to Qualify for a Mortgage Loan

    How to Qualify for a Mortgage Loan

    Buying a home is one of the biggest financial decisions most people make. Whether you’re purchasing your first home or planning to move into a new property, qualifying for a mortgage loan is an important step in the process. While mortgage requirements may seem complicated at first, understanding what lenders look for can help you prepare and improve your chances of approval.

    Understand Your Credit Score

    Your credit score plays a major role in determining whether you qualify for a mortgage loan. Lenders use your credit history to evaluate how responsibly you manage debt and make payments.

    A higher credit score often leads to better mortgage options and lower interest rates. Before applying for a loan, review your credit report for any errors and work on improving your score if necessary. Paying bills on time, reducing credit card balances, and avoiding new debt can help strengthen your credit profile.

    Even if your score is not perfect, many loan programs are available for borrowers with different credit backgrounds. However, improving your credit before applying can increase your chances of securing favorable loan terms.

    Maintain a Stable Income

    Lenders want to see that you have a reliable source of income to make monthly mortgage payments. When reviewing your application, they typically examine your employment history, income consistency, and overall financial stability.

    Most lenders prefer borrowers who have been employed in the same field or with the same employer for at least two years. If you’re self-employed, you may need to provide additional documentation, such as tax returns and business records, to verify your income.

    Having a stable income reassures lenders that you can comfortably manage your mortgage obligations over time.

    Manage Your Debt-to-Income Ratio

    Another key factor lenders consider is your debt-to-income ratio (DTI). This ratio compares your monthly debt payments to your gross monthly income.

    A lower DTI indicates that you have enough income available to cover a mortgage payment after meeting your existing financial obligations. Common debts included in this calculation are:

    • Credit card payments
    • Auto loans
    • Student loans
    • Personal loans
    • Other recurring debts

    Reducing outstanding debt before applying for a mortgage can improve your DTI and make your application more attractive to lenders.

    Save for a Down Payment

    A down payment is the amount of money you contribute toward the purchase price of a home. While some loan programs allow low down payments, having a larger down payment can offer several advantages.

    A higher down payment may help you:

    • Qualify more easily for a mortgage
    • Reduce your monthly payment
    • Lower your loan amount
    • Potentially avoid private mortgage insurance (PMI)

    Start saving early and create a dedicated fund for your home purchase. Consistent savings demonstrate financial responsibility and can strengthen your mortgage application.

    Build Your Savings and Reserves

    In addition to a down payment, lenders often like to see that borrowers have financial reserves available after closing. These reserves can help cover unexpected expenses, such as home repairs, medical bills, or temporary income disruptions.

    Having money saved in checking, savings, retirement, or investment accounts can provide additional confidence to lenders that you are financially prepared for homeownership.

    Gather the Necessary Documentation

    Preparing your paperwork in advance can make the mortgage process smoother and faster. Most lenders will request documents such as:

    • Recent pay stubs
    • W-2 forms or tax returns
    • Bank statements
    • Employment verification
    • Identification documents

    Providing complete and accurate information helps prevent delays and allows lenders to evaluate your application efficiently.

    Get Pre-Approved Before House Hunting

    Mortgage pre-approval is a valuable step before you start shopping for a home. During pre-approval, a lender reviews your financial information and estimates how much you may be eligible to borrow.

    A pre-approval letter shows sellers that you’re a serious buyer and can help you focus on homes within your budget. It also gives you a clearer understanding of your borrowing power before making an offer.

    Need Help Qualifying for a Mortgage?

    Have questions about qualifying for a mortgage loan? Whether you need guidance on credit scores, income requirements, or loan options, call 201-745-3426 or email shaleenmahtani@gmail.com  for personalized assistance.

  • Fixed vs. Variable Mortgage Rates: Understanding the Differences and Choosing the Right Option

    Fixed vs. Variable Mortgage Rates: Understanding the Differences and Choosing the Right Option

    Choosing a mortgage is one of the biggest financial decisions you’ll make when buying a home. Among the many choices available, one of the most important is deciding between a fixed-rate mortgage and a variable-rate mortgage. Each option has its own advantages and potential drawbacks, and understanding how they work can help you make a decision that aligns with your financial goals and comfort level.

    What Is a Fixed-Rate Mortgage?

    A fixed-rate mortgage has an interest rate that remains the same throughout the loan term. Whether market interest rates rise or fall, your mortgage rate and monthly principal and interest payments stay consistent.

    This stability is one of the main reasons many homebuyers choose fixed-rate mortgages. With predictable monthly payments, it becomes easier to budget and plan for future expenses. You won’t have to worry about unexpected increases in your mortgage payment due to changing market conditions.

    Fixed-rate mortgages can be especially appealing when interest rates are low because you can lock in that rate for the duration of your term.

    What Is a Variable-Rate Mortgage?

    A variable-rate mortgage has an interest rate that can change over time based on market conditions and benchmark interest rates. As rates move up or down, the interest portion of your mortgage payment may also change.

    One advantage of a variable-rate mortgage is that it often starts with a lower interest rate than a comparable fixed-rate mortgage. This can lead to lower initial borrowing costs and potentially greater savings if market rates remain stable or decrease.

    However, there is also a level of uncertainty. If interest rates rise, your borrowing costs may increase, which could affect your monthly budget.

    Key Differences Between Fixed and Variable Rates

    The primary difference between these two mortgage options is predictability versus flexibility.

    With a fixed-rate mortgage, you know exactly what your interest rate and payments will be for the term of your loan. This can provide peace of mind and protection from rising rates.

    With a variable-rate mortgage, your rate can fluctuate with the market. While this may offer savings during periods of lower rates, it also carries the risk of higher costs if rates increase.

    Your choice often depends on your financial situation, risk tolerance, and long-term plans.

    Which Option Is Right for You?

    A fixed-rate mortgage may be a good fit if you prefer stability, have a strict monthly budget, or want protection from future rate increases. Many first-time homebuyers appreciate the certainty that comes with fixed payments.

    A variable-rate mortgage may be worth considering if you are comfortable with some uncertainty and can manage potential payment changes. It may also appeal to borrowers who believe interest rates could remain stable or decline in the future.

    Before making a decision, consider your income, financial goals, and how long you plan to stay in the home. Speaking with a mortgage professional can help you evaluate your options and understand how different rate scenarios may impact your finances.

    Making an Informed Mortgage Decision

    There is no one-size-fits-all answer when it comes to choosing between fixed and variable mortgage rates. The best choice depends on your individual circumstances and financial priorities. By understanding how each option works and weighing the benefits and risks, you can confidently select a mortgage that supports your homeownership goals and provides the level of financial comfort you’re looking for.

    Need Help Choosing the Right Mortgage Rate?

    Not sure whether a fixed-rate or variable-rate mortgage is the best fit for your financial situation? Understanding your options can help you make a more confident home-buying decision. For personalized guidance on mortgage rates, loan options, and financing strategies, call 201-745-3426 or email shaleenmahtani@gmail.com  for expert assistance.

  • Common Reasons Mortgage Applications Get Denied

    Common Reasons Mortgage Applications Get Denied

    Buying a home is an exciting milestone, but the mortgage approval process can sometimes feel overwhelming. Many homebuyers assume that getting approved for a mortgage is straightforward, only to discover that lenders carefully review every aspect of their financial situation before making a decision.

    Mortgage denials happen more often than many people realize. Understanding the common reasons applications get rejected can help you avoid costly mistakes and improve your chances of approval when you’re ready to purchase a home.

    Low Credit Score

    One of the most common reasons mortgage applications get denied is a low credit score. Your credit score gives lenders insight into how you manage debt and whether you’re likely to make mortgage payments on time.

    A low score may signal financial risk to a lender. Late payments, collections, bankruptcies, or high credit card balances can all negatively impact your credit score.

    Before applying for a mortgage, review your credit report, correct any errors, and work on improving your score if necessary. Even a small increase in your credit score can make a significant difference.

    High Debt-to-Income Ratio

    Lenders want to ensure that you can comfortably afford your monthly mortgage payment. To determine this, they calculate your debt-to-income (DTI) ratio, which compares your monthly debt obligations to your monthly income.

    If you have significant credit card debt, auto loans, student loans, or other financial obligations, your DTI ratio may be too high for mortgage approval.

    Reducing existing debt before applying can strengthen your financial profile and improve your chances of qualifying.

    Insufficient Income

    A stable and sufficient income is essential when applying for a mortgage. Lenders need confidence that you’ll be able to make payments consistently throughout the life of the loan.

    If your income doesn’t meet the lender’s requirements, your application may be denied. This can happen if you’re applying for a loan amount that’s too large relative to your earnings or if your income has recently decreased.

    Providing accurate income documentation and applying for a mortgage within your budget can help prevent this issue.

    Employment Instability

    Lenders prefer borrowers with a stable employment history. Frequent job changes, gaps in employment, or recently starting a new position can raise concerns.

    While changing jobs doesn’t automatically disqualify you, lenders may want additional documentation to verify income stability.

    If possible, maintain consistent employment before and during the mortgage application process to avoid unnecessary complications.

    Inadequate Down Payment

    The amount of money you put down on a home can affect your mortgage approval. Some loan programs require a minimum down payment, and failing to meet those requirements can result in a denial.

    A larger down payment may also demonstrate financial responsibility and reduce the lender’s risk. Planning and saving for a down payment can improve your approval odds and potentially help you secure better loan terms.

    Problems with the Property

    Sometimes the issue isn’t the borrower it’s the property itself.

    Lenders often require an appraisal to confirm the home’s value. If the property appraises for less than the purchase price, financing may be denied or delayed. Serious structural issues or safety concerns discovered during inspections can also create challenges.

    Working with experienced real estate professionals can help identify potential property-related issues early in the process.

    Incomplete or Inaccurate Information

    Even small mistakes on a mortgage application can lead to delays or denials. Missing documents, incorrect income information, undisclosed debts, or inconsistencies between application details and supporting paperwork can raise red flags.

    Being honest, organized, and thorough throughout the application process is critical. Double-check all information before submitting your paperwork to avoid unnecessary setbacks.

    How to Improve Your Chances of Approval

    Preparation is key when applying for a mortgage. Improving your credit score, paying down debt, maintaining stable employment, and organizing financial documents ahead of time can significantly strengthen your application.

    It’s also helpful to speak with a mortgage professional who can evaluate your financial situation and recommend steps to improve your eligibility before you apply.

    Need Help Understanding Your Mortgage Options?

    Getting denied doesn’t necessarily mean homeownership is out of reach. If you have questions about mortgage qualifications, credit requirements, or loan options, professional guidance can help you understand your next steps.

    For personalized mortgage assistance, call 201-745-3426 or email shaleenmahtani@gmail.com  to discuss your situation and explore available financing options.

  • Understanding the Home Appraisal Process: What Every Buyer Should Know

    Understanding the Home Appraisal Process: What Every Buyer Should Know

    The appraisal process continues to play a critical role in residential mortgage lending, serving as an independent assessment of collateral value before a loan can move toward closing. While technology has streamlined portions of the valuation process, lenders still rely heavily on appraisals to manage risk, comply with investor requirements, and ensure accurate loan-to-value calculations.

    How the Appraisal Process Works

    A typical appraisal begins after a borrower has a property under contract and the lender orders an appraisal through an appraisal management company or directly from a licensed appraiser. The appraiser evaluates the property’s condition, size, location, and features before comparing it with recently sold properties in the surrounding market.

    Comparable sales, commonly referred to as “comps,” remain the foundation of most residential appraisals. Appraisers analyze recent transactions involving similar homes and make adjustments for differences in square footage, lot size, upgrades, condition, and other factors that may influence market value.

    What the Appraisal Report Includes

    Once the property inspection and market analysis are complete, the appraiser prepares a report detailing the estimated fair market value. The report also includes information on neighborhood trends, property characteristics, and any conditions that could affect value or marketability.

    Impact on Lenders and Borrowers

    For lenders, the appraisal serves as an important risk-management tool. A valuation that meets or exceeds the purchase price generally allows the loan process to proceed without interruption. However, when an appraisal comes in below the agreed-upon sales price, borrowers and sellers may need to renegotiate terms, increase the down payment, or pursue a reconsideration of value.

    Modernization and Alternative Valuation Methods

    The growing adoption of appraisal modernization initiatives has introduced alternatives to traditional property inspections in certain transactions. Desktop appraisals, hybrid appraisals, and automated valuation models have gained traction, particularly for low-risk loans and refinance transactions. Even so, full appraisals remain the preferred option for many purchase mortgages where market conditions or property characteristics warrant a more comprehensive review.

    Outlook for the Valuation Industry

    Industry participants continue to monitor appraisal turn times, appraiser availability, and regulatory developments as the housing market evolves. While technology is improving efficiency across the valuation ecosystem, the appraisal process remains a fundamental component of mortgage underwriting and secondary market risk assessment.

    As lenders seek to balance speed, cost, and accuracy, the appraisal process is expected to remain a central element of mortgage origination workflows for the foreseeable future.

    Have Questions About the Appraisal Process? 

    Whether you’re buying your first home, refinancing, or navigating a low appraisal, understanding how property valuations impact your mortgage is essential. Every situation is different, and the right guidance can help you avoid delays and make informed decisions. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your situation and get started. 

  • Why Your Credit Score Matters More Than You Think

    Why Your Credit Score Matters More Than You Think

    Many people only think about their credit score when they need a loan, a credit card, or a mortgage. However, your credit score plays a much bigger role in your financial life than most people realize. It acts like a financial report card, giving lenders and other organizations a quick look at how responsibly you manage money.

    Whether you’re planning to buy a home, finance a car, or simply improve your financial health, understanding the importance of your credit score can help you make smarter decisions and save money in the long run.

    What Is a Credit Score?

    A credit score is a three-digit number that reflects your creditworthiness. It is based on factors such as your payment history, outstanding debts, the length of your credit history, and how much of your available credit you utilize.

    Lenders use this score to determine how risky it may be to lend you money. A higher score generally indicates that you are a reliable borrower, while a lower score may suggest financial challenges or missed payments in the past.

    How Your Credit Score Impacts Borrowing Opportunities 

    One of the most obvious reasons your credit score matters is that it directly impacts your chances of getting approved for loans and credit cards. Banks and lenders often review your score before deciding whether to approve your application.

    A strong credit score can make it easier to qualify for mortgages, personal loans, and auto financing. On the other hand, a low score may result in applications being rejected or limited borrowing options.

    How Good Credit Helps You Save Money 

    Your credit score doesn’t just determine whether you can borrow money; it also affects how much it costs to borrow. People with higher credit scores are often offered lower interest rates because lenders view them as less risky. 

    Even a small difference in interest rates can add up to significant savings over time, especially on large loans like mortgages or car loans. For example, someone with excellent credit may pay thousands less in interest over the life of a loan compared to someone with poor credit.

    The Role of Credit Scores in Securing Housing 

    Many landlords check credit scores when reviewing rental applications. A good credit score can help demonstrate that you are financially responsible and likely to pay rent on time.

    If your score is low, landlords may require a larger security deposit, ask for a co-signer, or choose another applicant altogether.

    It Reflects Financial Responsibility

    Your credit score is often seen as a reflection of how well you manage financial obligations. Paying bills on time, keeping debt under control, and using credit wisely all contribute to a healthier score.

    Building good credit habits today can create more opportunities and financial flexibility in the future.

    How to Improve Your Credit Score

    Improving your credit score doesn’t happen overnight, but small steps can make a big difference over time. Some effective strategies include:

    • Paying bills on time every month
    • Keeping credit card balances low
    • Avoiding unnecessary debt
    • Reviewing credit reports for errors
    • Maintaining older credit accounts when possible

    Consistency is key. Positive financial habits can gradually strengthen your score and improve your overall financial health.

    Have Questions About Your Credit Score?

    Your credit score can have a major impact on your financial opportunities, from loan approvals to interest rates. If you have questions about your credit or want to explore your borrowing options, call 201-745-3426 or email shaleenmahtani@gmail.com  for personalized guidance.

  • The Complete Guide to Mortgage Lending for First-Time Homebuyers

    The Complete Guide to Mortgage Lending for First-Time Homebuyers

    Buying your first home is one of the most exciting milestones in life. It is also one of the biggest financial decisions you will ever make. For many first-time buyers, the mortgage process can feel overwhelming, filled with unfamiliar terms, paperwork, and important decisions.

    The good news is that mortgage lending does not have to be complicated. With the right guidance and preparation, you can confidently navigate the home financing process and move one step closer to owning the home of your dreams.

    What Is Mortgage Lending?

    Mortgage lending is the process of borrowing money from a lender to purchase a home. Since most people cannot pay the full purchase price upfront, lenders provide financing that allows buyers to spread payments over a set period, typically 15 or 30 years.

    In exchange for the loan, the property serves as collateral. This means the lender has a legal interest in the home until the mortgage is fully repaid.

    Mortgage lending involves more than simply qualifying for a loan. It includes evaluating your financial situation, selecting the right mortgage program, determining affordability, and securing financing that aligns with your long-term goals.

    For first-time homebuyers, understanding how mortgage lending works is the foundation for making informed decisions throughout the home-buying journey.

    Why Mortgage Pre-Approval Matters

    Before you start touring homes, obtaining a mortgage pre-approval should be one of your first steps.

    A pre-approval is a lender’s assessment of your financial profile, including your income, assets, credit history, and debt obligations. Based on this review, the lender provides an estimate of how much you may be eligible to borrow.

    Pre-approval offers several benefits:

    Strengthens Your Position as a Buyer

    In competitive real estate markets, sellers often prefer buyers who already have financing in place. A pre-approval letter demonstrates that you are serious and financially qualified.

    Helps You Set a Realistic Budget

    Many buyers begin shopping based on what they hope to spend rather than what they can comfortably afford. Pre-approval helps establish a realistic price range and prevents disappointment later.

    Identifies Potential Issues Early

    If there are concerns with your credit, income documentation, or debt levels, they can be addressed before you make an offer on a property.

    Understanding Your Credit Score

    Your credit score plays a significant role in mortgage lending. It helps lenders evaluate your borrowing history and determine the level of risk associated with approving your loan.

    A higher credit score generally provides access to:

    • Better interest rates
    • Lower monthly payments
    • More loan options
    • Reduced borrowing costs over time

    If your credit score needs improvement, consider:

    • Paying bills on time
    • Reducing outstanding debt
    • Avoiding new credit applications
    • Reviewing your credit report for errors

    Even small improvements in your credit profile can make a meaningful difference in your mortgage terms.

    How Much Home Can You Afford?

    One of the most common mistakes first-time buyers make is focusing solely on the purchase price rather than the total cost of homeownership.

    Mortgage affordability depends on several factors, including:

    • Household income
    • Existing monthly debts
    • Down payment amount
    • Property taxes
    • Homeowners insurance
    • Interest rates
    • HOA fees, if applicable

    A comfortable monthly payment should fit within your overall financial goals while leaving room for savings, emergencies, and future expenses.

    Working with an experienced mortgage professional can help you determine a realistic budget based on your complete financial picture rather than simply the maximum amount a lender may approve.

    Common Mortgage Loan Options for First-Time Buyers

    Not all mortgage loans are the same. Understanding the most common loan programs can help you choose the option that best fits your needs.

    Conventional Loans

    Conventional loans are among the most popular mortgage products available today.

    These loans typically offer competitive rates and flexible terms for borrowers with strong credit profiles. Depending on the program, down payments may be as low as 3%.

    Conventional financing is often a great option for buyers who have stable income and a solid credit history.

    FHA Loans

    Federal Housing Administration (FHA) loans are designed to help borrowers with lower credit scores or limited savings for a down payment.

    Benefits include:

    • Lower down payment requirements
    • Flexible credit guidelines
    • Easier qualification standards

    FHA loans can be especially valuable for first-time buyers entering the housing market.

    VA Loans

    Eligible military service members, veterans, and certain surviving spouses may qualify for VA loans.

    These loans offer significant advantages, including:

    • No down payment requirement
    • Competitive interest rates
    • No private mortgage insurance (PMI)

    For qualified borrowers, VA loans can provide one of the most affordable paths to homeownership.

    USDA Loans

    USDA loans support homebuyers purchasing properties in eligible rural and suburban areas.

    Advantages may include:

    • No down payment requirement
    • Competitive rates
    • Affordable financing opportunities

    Many buyers are surprised to learn that numerous suburban communities qualify under USDA guidelines.

    Mortgage Interest Rates Explained

    Interest rates directly impact the total cost of your mortgage.

    Even a small difference in rate can significantly affect monthly payments and the amount paid over the life of the loan.

    Mortgage rates are influenced by factors such as:

    • Economic conditions
    • Inflation trends
    • Credit score
    • Loan type
    • Down payment amount
    • Debt-to-income ratio

    Because rates change frequently, it is important to discuss current market conditions with your lender when planning a home purchase.

    Understanding rate options and lock strategies can help buyers make informed financing decisions.

    The Mortgage Application Process

    The mortgage process generally follows several key stages.

    Step 1: Pre-Approval

    Your lender reviews income, assets, credit, and debts to determine eligibility.

    Step 2: Home Search

    Once pre-approved, you can begin searching for homes within your approved budget.

    Step 3: Purchase Agreement

    After finding the right property, you submit an offer and negotiate terms with the seller.

    Step 4: Loan Processing

    Your lender collects documentation and verifies financial information.

    Step 5: Underwriting

    An underwriter reviews the file to ensure it meets loan guidelines.

    Step 6: Final Approval

    Once conditions are satisfied, the lender issues final approval.

    Step 7: Closing

    Closing documents are signed, funds are transferred, and ownership is officially transferred to the buyer.

    Understanding these stages helps reduce stress and creates realistic expectations throughout the transaction.

    Documents You’ll Need for Mortgage Approval

    Being prepared can help streamline the lending process.

    Common documents include:

    • Government-issued identification
    • Recent pay stubs
    • W-2 forms
    • Tax returns
    • Bank statements
    • Employment information
    • Investment account statements
    • Proof of additional income, if applicable

    Providing complete and accurate documentation helps prevent delays and keeps the transaction moving smoothly.

    Mistakes First-Time Homebuyers Should Avoid

    Many buyers unknowingly make financial decisions that can impact mortgage approval.

    Common mistakes include:

    Making Large Purchases Before Closing

    Avoid financing vehicles, furniture, or other major purchases while your mortgage is being processed.

    Changing Jobs Without Consulting Your Lender

    Employment changes may affect loan qualification and should be discussed before making a move.

    Opening New Credit Accounts

    New credit inquiries can impact your credit profile and debt-to-income ratio.

    Draining Your Savings

    Closing costs, moving expenses, and unexpected repairs can arise after purchase. Maintaining reserves is important.

    Ignoring Additional Housing Costs

    Property taxes, insurance, maintenance, and utilities should be considered when budgeting for homeownership.

    Why Working with an Experienced Mortgage Professional Matters

    Mortgage lending is not simply about securing financing. It is about finding a solution that aligns with your goals, financial situation, and plans.

    An experienced mortgage professional can help you:

    • Understand available loan options
    • Compare financing strategies
    • Navigate changing market conditions
    • Identify opportunities to save money
    • Avoid costly mistakes
    • Move through the process with confidence

    For first-time homebuyers, having knowledgeable guidance can make the difference between a stressful experience and a successful one.

    Ready to Begin Your Homebuying Journey?

    With nearly three decades of mortgage banking experience, Shaleen Mahtani helps first-time homebuyers find the right financing with confidence. Call 201-745-3426 or email shaleenmahtani@gmail.com today to discuss your options and take the first step toward homeownership. 
  • Interest Rates in NY & NJ: What Homebuyers Need to Know in Today’s Market

    Interest Rates in NY & NJ: What Homebuyers Need to Know in Today’s Market

    For homebuyers in New York and New Jersey, interest rates are one of the most important factors shaping affordability and purchasing decisions. Even small changes in rates can significantly impact monthly payments, borrowing power, and the overall cost of owning a home.

    In today’s shifting market, understanding how interest rates work and how they affect your mortgage can help you make smarter, more confident decisions, whether you’re a first-time buyer or a move-up homeowner.

    What Are Interest Rates and Why Do They Matter?

    Interest rates represent the cost of borrowing money from a lender. When you take out a mortgage, the interest rate determines how much extra you pay over time in addition to the loan principal.

    For example, two buyers purchasing the same home can end up with very different monthly payments simply because of a difference in interest rates. A lower rate reduces your monthly payment and total loan cost, while a higher rate increases both.

    This is why interest rates are often considered the “hidden driver” of housing affordability in markets like NY and NJ.

    How Interest Rates Impact Home Affordability

    Affordability is not just about home prices it is directly tied to financing costs.

    When interest rates rise:

    • Monthly mortgage payments increase
    • Buyers qualify for lower loan amounts
    • Purchasing power decreases
    • Competition may shift toward lower price ranges

    When interest rates fall:

    • Monthly payments become more affordable
    • Buyers may qualify for larger loans
    • Demand in the housing market often increases

    In high-cost areas like New York City suburbs, Long Island, Northern New Jersey, and commuter-friendly towns, even a small rate change can significantly impact what homes are realistically within reach.

    What Influences Interest Rates Today?

    Interest rates are not set randomly by lenders. They are influenced by broader economic conditions, including:

    Inflation

    When inflation is high, borrowing becomes more expensive. Lenders raise rates to protect purchasing power over time.

    Federal Reserve Policy

    The Federal Reserve’s decisions on benchmark interest rates indirectly affect mortgage pricing, although mortgage rates do not move in perfect sync with Fed changes.

    Bond Market Activity

    Mortgage rates are closely tied to U.S. Treasury yields. When bond yields rise, mortgage rates often follow.

    Economic Conditions

    Strong economic growth can lead to higher rates, while slower growth may support lower borrowing costs.

    Understanding these factors helps buyers realize that rate movements are part of a larger economic cycle, not just short-term fluctuations.

    Why NY & NJ Are Especially Sensitive to Rate Changes

    New York and New Jersey are among the most rate-sensitive housing markets in the country due to higher-than-average home prices.

    In these regions:

    • A small rate increase can significantly reduce affordability
    • Buyers often stretch budgets to remain competitive
    • Property taxes add to monthly housing costs
    • Commuter demand keeps prices relatively strong

    Because of this, even a 0.5% shift in interest rates can change a buyer’s qualification range by tens of thousands of dollars.

    This makes rate awareness especially important when planning a purchase in these markets.

    Fixed vs Adjustable Interest Rates

    Homebuyers typically choose between fixed-rate and adjustable-rate mortgages (ARMs).

    Fixed-Rate Mortgages

    A fixed-rate mortgage keeps your interest rate the same throughout the loan term. This provides stability and predictable payments, making it a popular choice for long-term homeowners.

    Adjustable-Rate Mortgages (ARMs)

    An ARM starts with a lower initial rate for a set period, after which it adjusts based on market conditions. While ARMs can offer short-term savings, they come with the risk of future payment increases.

    Choosing between the two depends on your financial goals, how long you plan to stay in the home, and your comfort level with potential rate changes.

    How Credit Scores Affect Your Interest Rate

    Your credit score plays a major role in determining the interest rate you receive.

    In general:

    • Higher credit scores = lower interest rates
    • Lower credit scores = higher borrowing costs

    Lenders view credit scores as a measure of financial reliability. Buyers with strong credit profiles are considered lower risk and are often rewarded with better rates.

    Improving your credit score before applying for a mortgage can lead to meaningful savings over the life of the loan.

    The Role of Down Payment in Interest Rates

    Your down payment also influences your mortgage rate and overall affordability.

    A larger down payment can:

    • Lower your loan-to-value ratio
    • Improve loan pricing
    • Reduce monthly mortgage insurance costs
    • Strengthen your loan application

    In competitive markets like NY and NJ, buyers often explore different down payment strategies to balance upfront costs with long-term affordability.

    Should You Wait for Interest Rates to Drop?

    Many buyers wonder if they should delay purchasing in hopes that rates will fall.

    While lower rates can improve affordability, waiting comes with trade-offs:

    • Home prices may continue to rise
    • Inventory may remain limited
    • Competition can increase if rates drop
    • There is no guaranteed timing for rate decreases

    Instead of trying to time the market, many buyers focus on whether they can comfortably afford a home under current conditions. In some cases, buying now and refinancing later can be a practical strategy if rates improve in the future.

    Strategies to Get a Better Interest Rate

    Even in a higher-rate environment, buyers have options to improve their mortgage terms:

    • Improve your credit score before applying
    • Reduce outstanding debt
    • Increase your down payment if possible
    • Compare multiple loan programs
    • Consider rate buydown options
    • Work with an experienced mortgage professional

    Small adjustments can lead to meaningful savings over time.

    Ready to Understand Your Rate Options?

    If you are planning to buy a home in the United States, I can help you understand how today’s interest rates affect your purchasing power and what loan options may fit your budget. Call 201-745-3426 or email shaleenmahtani@gmail.com  to discuss your situation and get started.

  • Mortgage Rates and Housing Affordability: What Every Homebuyer Needs to Know

    Mortgage Rates and Housing Affordability: What Every Homebuyer Needs to Know

    For many prospective homebuyers, one question dominates the homebuying journey: Can I still afford to buy a home in today’s market?

    With mortgage rates fluctuating and home prices remaining elevated across much of the Northeast and other parts of the country, affordability has become one of the biggest concerns for first-time buyers, move-up buyers, and even real estate investors. While headlines often focus on rising rates or limited housing inventory, the reality is more nuanced.

    Understanding how mortgage rates influence affordability can help buyers make smarter decisions, identify opportunities, and create realistic expectations before entering the market. Whether you’re looking for a starter home, your second home, or considering an investment property a competitive housing market, understanding the relationship between mortgage rates and affordability is essential.

    Understanding Mortgage Rates and Why They Matter

    Mortgage rates represent the cost of borrowing money to purchase a home. While buyers often focus on a property’s purchase price, the interest rate attached to the mortgage can significantly impact monthly payments and overall affordability.

    Even a small change in mortgage rates can affect:

    • Monthly mortgage payments
    • Loan qualification amounts
    • Purchasing power
    • Long-term interest costs
    • Overall housing affordability

    For example, a buyer approved for a specific monthly payment may qualify for a larger loan when rates are lower. When rates rise, that same monthly budget may support a smaller loan amount.

    This is why mortgage rates remain one of the most influential factors in the housing market.

    Why Housing Affordability Has Become a Major Concern

    Housing affordability is determined by more than just home prices. It is the combination of several factors working together, including:

    • Mortgage interest rates
    • Household income
    • Property taxes
    • Home insurance costs
    • Housing inventory
    • Local market conditions

    Over the past several years, many areas throughout New York and New Jersey have experienced significant home price appreciation. At the same time, higher borrowing costs have increased monthly mortgage payments, creating affordability challenges for many buyers.

    The result is that buyers often find themselves competing for limited inventory while facing higher financing costs than they may have expected.

    However, affordability challenges do not necessarily mean homeownership is out of reach. It simply means buyers need a strategic approach.

    The Relationship Between Mortgage Rates and Monthly Payments

    Many homebuyers underestimate how much mortgage rates affect their monthly budget.

    When rates increase, a larger portion of each payment goes toward interest, which can reduce purchasing power. Conversely, lower rates often allow buyers to qualify for more expensive homes while maintaining similar monthly payments.

    Consider two buyers purchasing similarly priced homes. The buyer securing a lower interest rate may save hundreds of dollars per month compared to someone financing the same property at a higher rate.

    Over the life of a mortgage, these differences can translate into tens of thousands of dollars in savings.

    Because of this, buyers should focus not only on home prices but also on financing strategies that can improve affordability.

    What Is Driving Mortgage Rates Today?

    A variety of economic factors influences mortgage rates. While lenders set their own rates, broader market conditions play a significant role.

    Some of the primary influences include:

    Inflation

    Inflation remains one of the biggest drivers of mortgage rates. When inflation rises, borrowing costs often increase as lenders seek to protect against reduced purchasing power.

    Federal Reserve Policy

    Although the Federal Reserve does not directly set mortgage rates, its decisions regarding interest rates can influence financial markets and lending conditions.

    Economic Growth

    Strong economic activity often contributes to higher borrowing costs, while slower economic growth may place downward pressure on rates.

    Bond Market Performance

    Mortgage rates are closely tied to bond market activity, particularly U.S. Treasury securities. Changes in investor sentiment can influence mortgage pricing throughout the market.

    Understanding these factors helps buyers recognize that mortgage rates are shaped by broader economic conditions and may change over time.

    Housing Market Trends in New York

    New York remains one of the most diverse real estate markets in the country. Housing conditions can vary dramatically depending on location.

    In many areas, buyers continue to face:

    • Limited housing inventory
    • Strong buyer demand
    • Competitive bidding situations
    • Elevated home prices

    Suburban communities surrounding New York City have remained particularly attractive due to commuting flexibility and lifestyle preferences. Many buyers continue seeking additional space while maintaining access to employment centers.

    Despite affordability challenges, demand remains relatively strong because New York continues to attract professionals, families, and long-term investors.

    For buyers, preparation and financing readiness have become increasingly important when competing in this environment.

    Housing Market Trends in New Jersey

    New Jersey continues to be one of the most sought-after housing markets in the Northeast.

    The state offers several advantages:

    • Proximity to New York City and Philadelphia
    • Strong school districts
    • Diverse housing options
    • Growing suburban communities

    Like New York, New Jersey has experienced inventory shortages in many local markets. This limited supply has helped maintain property values despite higher mortgage rates.

    Many buyers continue to find opportunities in emerging communities where affordability remains stronger compared to some of the state’s more competitive markets.

    Working with local mortgage professionals who understand regional trends can help buyers identify financing solutions that align with their goals.

    Strategies to Improve Home Affordability

    While buyers cannot control market conditions, they can take steps to improve affordability and strengthen their purchasing power.

    Improve Your Credit Score

    A higher credit score often leads to better mortgage rates and more favorable loan terms.

    Simple actions such as paying down debt, making payments on time, and correcting credit report errors can improve financing opportunities.

    Increase Your Down Payment

    A larger down payment may reduce your loan amount, lower your monthly payments, and improve your loan pricing.

    Even modest increases in your down payment can create meaningful savings over time.

    Explore Different Loan Programs

    Many buyers focus solely on conventional loans without considering other options.

    Programs such as:

    • FHA loans
    • VA loans
    • USDA loans
    • First-time homebuyer assistance programs

    may provide opportunities to improve affordability and reduce upfront costs.

    Reduce Existing Debt

    Lenders evaluate debt-to-income ratios when determining mortgage eligibility.

    Paying off high-interest debt can improve your financial profile and potentially increase your borrowing capacity.

    Why Mortgage Pre-Approval Is More Important Than Ever

    In competitive markets like New York and New Jersey, mortgage pre-approval has become an essential first step.

    Pre-approval helps buyers:

    • Understand their purchasing power
    • Establish a realistic budget
    • Identify financing issues early
    • Strengthen offers when competing against other buyers

    Sellers often view pre-approved buyers more favorably because financing uncertainty is reduced.

    In fast-moving markets, having financing already in place can provide a significant advantage.

    Should You Wait for Mortgage Rates to Fall?

    Many buyers delay purchasing because they hope rates will decrease.

    While lower rates may eventually improve affordability, attempting to perfectly time the market can be difficult.

    Several considerations are important:

    • Home prices may continue rising.
    • Inventory may remain limited.
    • Increased buyer demand could create additional competition.
    • Future rate movements are uncertain.

    Rather than focusing solely on where rates might go, buyers should evaluate whether purchasing aligns with their personal finances, housing needs, and long-term goals.

    For many households, buying the right home at the right time can be more important than waiting for a specific interest rate.

    The Value of Professional Mortgage Guidance

    Today’s mortgage market is more complex than many buyers realize. Interest rates, loan programs, affordability calculations, and changing market conditions all influence financing decisions.

    An experienced mortgage professional can help buyers:

    • Compare loan options
    • Understand affordability limits
    • Evaluate current market conditions
    • Improve financing strategies
    • Navigate the approval process with confidence

    Especially in high-cost markets like New York and New Jersey, expert guidance can help buyers make informed decisions and avoid costly mistakes.

    Ready to Navigate the NY & NJ Market?

    If you are planning to buy a home in New York or New Jersey, I can help you understand how today’s mortgage rates impact affordability and what you can realistically qualify for. Call 201-745-3426 or email shaleenmahtani@gmail.com to discuss your options and get started with confidence. 
  • What New York and New Jersey Homebuyers Should Know Right Now

    The residential real estate market in New York and New Jersey continues to reward prepared buyers. While conditions can vary by county, price point, and property type, many buyers are still navigating limited inventory, competitive offers, and affordability concerns tied to interest rates, taxes, and monthly payment planning. The good news is that strong preparation can create real advantages.

    One World Trade Center and the Lower Manhattan skyline viewed from the Hoboken, New Jersey waterfront promenade on a cloudy autumn day.

    Inventory Still Matters

    Across many New York and New Jersey communities, buyers are still seeing a market where well-priced homes can move quickly. In some areas, inventory has improved compared with the tightest periods of the past few years, but supply can still feel limited for move-in-ready homes in desirable neighborhoods. That means buyers should be ready to act when the right property appears.

    For first-time buyers, this often means narrowing priorities early. Knowing which features are must-haves and which are flexible can help you make faster, more confident decisions when competition increases.

    Monthly Payment Is the Real Decision

    In both New York and New Jersey, homebuyers need to look beyond the purchase price. Property taxes, homeowners insurance, mortgage insurance when applicable, and association fees can all have a major impact on the true monthly cost of ownership. In higher-cost markets, this payment-focused approach is often more useful than thinking only about maximum loan amount.

    A smart home search starts with a payment strategy, not just a price target.

    Pre-Approval Helps You Compete

    A strong pre-approval remains one of the most important tools for buyers in today’s market. Sellers and agents want confidence that a transaction can close smoothly. When your financing is reviewed early, you can shop with better clarity and move more quickly when you find a home you want to pursue.

    • Review income, assets, and credit before you begin shopping
    • Understand your comfortable monthly payment range
    • Estimate cash needed for down payment and closing costs
    • Discuss loan options that fit your goals, timeline, and occupancy plans

    Local Strategy Still Wins

    The New York and New Jersey markets are not one-size-fits-all. Buyer behavior can differ significantly between suburban towns, urban condos, commuter locations, and higher-end single-family markets. A financing strategy that works well in one area may need adjustment in another, especially when taxes, appraisal expectations, or co-op and condo requirements come into play.

    That is why it helps to work with a lender who can talk through the numbers clearly and help you prepare before you are under pressure to make an offer.

    How Buyers Can Prepare Now

    • Check your credit and avoid major new debt
    • Keep documentation organized for income and assets
    • Build a realistic budget that includes taxes and insurance
    • Stay flexible on timing and property features
    • Get professional guidance before you start touring homes seriously

    Ready to Talk Through Your Options?

    If you are thinking about buying in New York or New Jersey, I can help you understand your financing options and what to expect in today’s market. Call 201-745-3426 or email shaleenmahtani@gmail.com to start the conversation.

  • How to Prepare to Buy a Home in Today’s Market

    Homebuyers preparing to purchase a home

    Home Buying Tips

    How to Prepare to Buy a Home in Today’s Market

    A practical guide to getting financially and mentally ready before you start shopping for a home.

    Buying a home is one of the biggest financial decisions most people will make, and preparation can make the process smoother, less stressful, and more successful. Whether you are a first-time buyer or returning to the market, taking the right steps early can help you understand your options, strengthen your application, and move forward with confidence.
    In today’s market, it is especially important to be organized, realistic about your budget, and ready to act when the right opportunity appears. Here are the key steps to help you prepare before you buy.

    Check Your Credit Early

    Your credit profile plays a major role in your mortgage options, interest rate, and overall loan costs. Before applying, review your credit reports and make sure the information is accurate. If you notice errors, dispute them as soon as possible. If your score needs improvement, focus on paying bills on time, reducing credit card balances, and avoiding new debt.

    Even small improvements in your credit profile may help expand your financing options and improve pricing.

    Build a Realistic Budget

    Many buyers focus only on the monthly mortgage payment, but homeownership includes more than principal and interest. Property taxes, homeowners insurance, utilities, maintenance, and possible association dues should all be part of your planning. A realistic budget helps you understand what feels comfortable, not just what may be technically approved.

    • Review your monthly income and fixed expenses
    • Estimate housing costs beyond the mortgage payment
    • Leave room for savings and unexpected expenses
    • Set a target payment range that fits your lifestyle

    Save for More Than the Down Payment

    Your down payment is important, but it is not the only cash you may need. Buyers should also plan for closing costs, prepaid items, moving expenses, and early home-related purchases. Depending on the loan program, your required down payment may be lower than you expect, but having reserves can still strengthen your position.

    Understanding your total funds needed up front can help you avoid surprises later in the process.

    Gather Your Financial Documents

    Mortgage applications move more efficiently when your paperwork is ready. Lenders typically need documentation to verify income, assets, employment, and identity. Having these items organized can save time and reduce stress once you begin the loan process.

    • Recent pay stubs
    • W-2s and tax returns, if needed
    • Bank and asset statements
    • Photo identification
    • Information about current debts and obligations

    Get Pre-Approved Before You Shop

    A mortgage pre-approval gives you a clearer picture of your buying power and helps you shop with more confidence. It can also make your offer more competitive by showing sellers that you have already taken an important financial step. Pre-approval is not just about the maximum loan amount. It is also an opportunity to discuss loan options, monthly payment goals, and the best strategy for your situation.
    Understand How Interest Rates Affect Affordability

    Interest rates continue to influence affordability, which is why buyers should understand how rate changes can affect monthly payments and long-term costs. Even if rates move, there may still be strong opportunities depending on your goals, timing, and loan structure. A knowledgeable mortgage professional can help you compare scenarios and understand what makes sense for your budget.

    Avoid Major Financial Changes Before Closing

    Once you are pre-approved and under contract, consistency matters. Avoid making large purchases, opening new credit accounts, changing jobs without discussing it first, or moving money between accounts without documentation. These changes can affect your qualification and may create delays during underwriting.

    The safest approach is to keep your finances steady from application through closing unless you have spoken with your loan professional first.

    Work With a Trusted Mortgage Professional

    Every buyer’s situation is different. The right guidance can help you understand loan options, prepare your documentation, and make informed decisions from start to finish. Working with an experienced mortgage professional can bring clarity to the process and help you feel more confident at every stage.

    Ready to Take the Next Step?

    If you are thinking about buying a home and want trusted guidance tailored to your goals, contact Shaleen Mahtani to discuss your options and get prepared with confidence. Call 201-745-3426 or email shaleenmahtani@gmail.com to start the conversation.