Buying a home can feel challenging when you have limited savings or a credit history that needs improvement. FHA loans offer an option for eligible homebuyers who want to purchase a home with a relatively small down payment. Backed by the Federal Housing Administration (FHA), these mortgages are designed to make homeownership more accessible for qualified borrowers.
Understanding FHA loan requirements, benefits, and costs can help you decide whether this mortgage option fits your financial situation.
What Are FHA Loans?
FHA loans are mortgages issued by approved private lenders and insured by the Federal Housing Administration, a division of the U.S. Department of Housing and Urban Development (HUD). The government does not lend money directly to borrowers. Instead, FHA insurance reduces the lender’s risk, helping eligible buyers access mortgage financing.
These loans are particularly popular among first-time homebuyers and people who may not qualify for conventional financing on favorable terms. However, you do not have to be a first-time buyer to qualify.
FHA Loan Requirements
Before applying, it is important to understand the basic FHA loan eligibility guidelines.
Credit Score and Down Payment
FHA guidelines generally allow a minimum down payment of 3.5% for borrowers with a credit score of 580 or higher. Borrowers with scores between 500 and 579 may qualify with a down payment of at least 10%, subject to FHA requirements and lender approval.
For example, a 3.5% down payment on a $300,000 home equals $10,500. You will still need to budget for closing costs and other expenses.
Keep in mind that individual lenders may establish stricter credit score requirements.
Income and Debt-to-Income Ratio
Lenders review your income, existing debts, employment history, and ability to afford monthly mortgage payments. They generally verify your financial information through documents such as pay stubs, tax returns, bank statements, and employment records.
Your debt-to-income ratio (DTI) helps lenders assess how much of your gross monthly income goes toward debt payments. FHA financing offers flexibility, but approval depends on your overall financial profile and the lender’s underwriting assessment.
Property Requirements
FHA loans generally require the home to serve as your primary residence. Eligible properties can include single-family homes, certain condominiums, and properties with two to four units, provided they meet applicable occupancy and program requirements.
The property must also satisfy FHA appraisal standards. An appraisal helps establish the home’s value and evaluate whether it meets applicable property requirements.
Benefits of FHA Loans
FHA financing offers several advantages for eligible homebuyers.
- Low down payment: Qualified borrowers may purchase a home with as little as 3.5% down.
- Flexible credit guidelines: FHA requirements may accommodate borrowers with lower credit scores than many conventional mortgage programs.
- Multiple property options: Eligible buyers can finance different types of owner-occupied residential properties.
- Accessible financing: FHA loans can help buyers who have limited savings or are building their credit history explore homeownership.
Although these benefits can make purchasing a home more achievable, borrowers should compare FHA financing with conventional mortgages before making a decision.
What Costs Should You Expect With FHA Loans?
A low down payment does not mean an FHA mortgage is free from additional expenses. Understanding the total cost is essential before committing to a loan.
Mortgage insurance premiums: FHA loans generally require an upfront mortgage insurance premium (UFMIP) and an annual premium, typically paid in monthly installments. The upfront premium is generally 1.75% of the base loan amount and may be financed into the mortgage. Annual mortgage insurance costs vary depending on factors such as the loan amount, term, and loan-to-value ratio.
Closing costs: These may include lender fees, appraisal charges, title services, prepaid taxes, and homeowners insurance. The exact amount depends on the transaction and location.
Monthly housing expenses: Your payment may include principal, interest, property taxes, homeowners insurance, and mortgage insurance. Homeowners association fees may also apply.
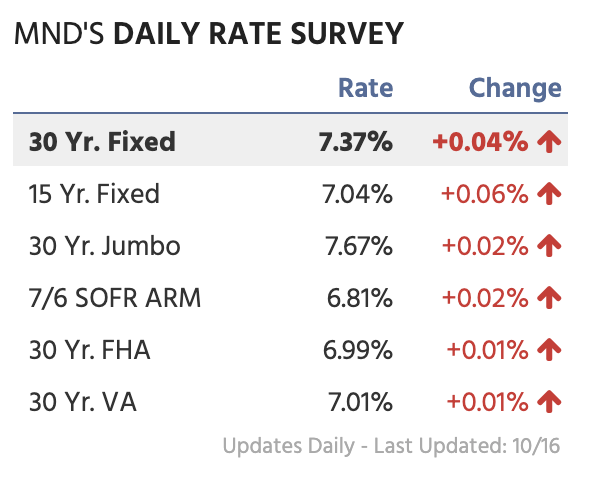
Because mortgage insurance adds to the overall cost, compare loan estimates rather than focusing only on the down payment.
Are FHA Loans Right for You?
FHA loans may be a good fit if you want to buy a home with a smaller down payment or need more flexible credit requirements. However, borrowers with stronger credit and larger down payments may find that conventional mortgages offer lower overall costs.
Before choosing, compare interest rates, mortgage insurance, closing costs, and long-term payments from multiple lenders.
Ready to Explore Your FHA Loan Options?
Finding the right mortgage starts with understanding your budget, credit profile, and available loan programs. If you are considering FHA loans, contact Shaleen Mahtani at 201-745-3426 or email shaleenmahtani@gmail.com to discuss your mortgage options, review your eligibility, and understand the costs involved. Get personalized guidance to help you take the next step toward homeownership with confidence.